Nowhere close to you both, but was an early investor in $PLTR back in 2022 / 23 when nonone cared.
Invested in HBM ( $MU, $DRAM)
Invested in photonics ($AIXA, $TSEM, $VECO, $LITE, $COHR, $CRDO)
Invested in other semis too ($SANM, $KLIC)
Very old investor in some of mag7 including Apple, $GOOGL, $AMZN
Invested in minerals mines (Gold, Copper), now thinking of tungsten
🐊 𝗡𝗲𝗯𝗶𝘂𝘀 𝗮𝗳𝘁𝗲𝗿 𝗲𝗮𝗿𝗻𝗶𝗻𝗴𝘀: 𝗪𝗵𝗮𝘁 𝗱𝗶𝗱 𝗺𝘆 𝟱 𝗶𝗻𝘃𝗲𝘀𝘁𝗼𝗿 𝗾𝘂𝗲𝘀𝘁𝗶𝗼𝗻𝘀 𝗿𝗲𝘃𝗲𝗮𝗹?
Yesterday, I posted five things I wanted to investigate as a Nebius shareholder. Not simply whether it would beat estimates, but whether AI infrastructure demand was translating into sustainable shareholder returns.
The summary: Q3 revenue beat estimates by 8% at $981M, and adjusted EBITDA reached $466M. But 2026 revenue is now expected at the low end of $3–3.4B, capex rises to $27B, and 2027 capex is projected at $40–45B.
Here’s what I found.
𝟭. 𝗥𝗲𝘃𝗲𝗻𝘂𝗲: 𝗧𝗵𝗲 𝗯𝗲𝗮𝘁 𝗻𝗲𝗲𝗱𝘀 𝗰𝗼𝗻𝘁𝗲𝘅𝘁.
$325M of Q3 revenue was non-recurring asset-light deployment revenue. Excluding this, revenue was approximately $656M, up 12.6% QoQ, not 68%.
At $3B FY revenue, Q4 must deliver approximately $1.04B. That’s roughly 58% above the underlying Q3 base. The beat is real, but so is the execution hurdle.
𝟮. 𝗠𝗶𝗰𝗿𝗼𝘀𝗼𝗳𝘁: 𝗧𝗵𝗲 𝗰𝗼𝗻𝘁𝗿𝗮𝗰𝘁𝘀 𝗿𝗲𝗺𝗮𝗶𝗻, 𝘁𝗵𝗲 𝘁𝗶𝗺𝗲𝗹𝗶𝗻𝗲𝘀 𝗱𝗼𝗻’𝘁.
Some third-party capacity is delayed into H1 2027. At the New Jersey (Vineland) site, operator DataOne began retiring temporary generation late in Q3, which reset the schedule.
More than half of the Microsoft capacity is still expected by year-end, with the remainder in Q2 2027. They gave a date; now they need to hit it.
𝟯. 𝗣𝗼𝘄𝗲𝗿: 𝗧𝗵𝗲 𝗴𝗮𝗽 𝗶𝘀 𝘀𝘁𝗶𝗹𝗹 𝘁𝗵𝗲𝗿𝗲.
Over 4GW contracted, targeting 5GW by year-end. But no updated connected-power figure was provided.
Contracted power is an option on future revenue, not revenue itself. The market needs evidence of conversion into operational capacity.
𝟰. 𝗖𝗮𝗽𝗲𝘅: 𝗖𝘂𝘀𝘁𝗼𝗺𝗲𝗿 𝗳𝘂𝗻𝗱𝗶𝗻𝗴 𝗵𝗲𝗹𝗽𝘀, 𝗯𝘂𝘁 𝗱𝗼𝗲𝘀𝗻’𝘁 𝗲𝗹𝗶𝗺𝗶𝗻𝗮𝘁𝗲 𝗿𝗶𝘀𝗸.
Prepayments now cover over 100% of capex on Q3 contract wins. Management expects prepayments and asset-backed financing to cover 75–85% of 2027 capex.
Encouraging, but Q3 capex was $7.3B against negative $273M operating cash flow.
Nine-month funding included $10.1B convertible issuance and $3.9B treasury-share proceeds. Shares outstanding rose approximately 16% YoY.
Growth is being funded, but existing shareholders are paying part of the bill.
𝟱. 𝗨𝗻𝗶𝘁 𝗲𝗰𝗼𝗻𝗼𝗺𝗶𝗰𝘀: 𝗧𝗵𝗲 𝗻𝘂𝗺𝗯𝗲𝗿 𝗻𝗲𝗲𝗱𝘀 𝗱𝗲𝗰𝗼𝗱𝗶𝗻𝗴.
AI Cloud EBITDA margin reached 53.2%. Management’s 19-month payback sounds attractive, but this is revenue payback on comparable deals, not profit payback.
On my rough maths, applying the 53.2% margin implies roughly 36 months of EBITDA payback, before financing and other costs. This assumes new capacity achieves the same margin.
Pre-tax break-even is only expected in Q4 2027, assuming five-year GPU depreciation. Hardware replacement cycles and actual economic life matter. Accounting break-even isn’t necessarily economic break-even.
🐊 𝗧𝗛𝗘 𝗢𝗩𝗘𝗥𝗟𝗢𝗢𝗞𝗘𝗗 𝗪𝗔𝗥𝗡𝗜𝗡𝗚𝗦
▪️ RPO rose just 3%, from $37.5B to $38.7B, despite nearly $1B of revenue recognised. On a simplified basis, that implies roughly $2.2B or less of gross additions to RPO. Modest against $27B of planned annual capex.
▪️ The $7B+ ARR milestone moved from December to February. Management is also moving away from ARR as its preferred measure, focusing instead on revenue and pre-tax earnings. The timing deserves scrutiny.
🐊 𝗪𝗔𝗦 𝗧𝗛𝗘 𝗦𝗘𝗟𝗟-𝗢𝗙𝗙 𝗝𝗨𝗦𝗧𝗜𝗙𝗜𝗘𝗗?
The biggest shock wasn’t revenue; it was the capital requirement. 2027 capex of $40–45B versus expectations around $29B changes the financing and execution equation.
Part of the decline also reversed the previous day’s rally. But the underlying concerns are real.
The market is repricing the cost, timing and risk of growth, not necessarily the demand.
𝗠𝘆 𝘃𝗲𝗿𝗱𝗶𝗰𝘁: The AI infrastructure thesis remains intact. But demand alone doesn’t make this a good investment. Nebius must prove that every additional dollar invested produces attractive incremental returns.
Thats the real test. Not financial advice.
🐊 𝗡𝗲𝗯𝗶𝘂𝘀 𝗲𝗮𝗿𝗻𝗶𝗻𝗴𝘀: 𝟱 𝘁𝗵𝗶𝗻𝗴𝘀 𝗜’𝗺 𝘄𝗮𝘁𝗰𝗵𝗶𝗻𝗴 𝗮𝘀 𝗮 𝘀𝗵𝗮𝗿𝗲𝗵𝗼𝗹𝗱𝗲r - rather than just ‘beat the estimates’
Nebius reports Q3 earnings today. I’m a shareholder, so naturally I want to see the company execute. But I don’t want to confuse a good AI story with a good investment.
The AI infrastructure opportunity is enormous. The question is whether Nebius can turn that opportunity into sustainable shareholder returns.
Here are the 5 things I’ll be investigating:
𝟭. 𝗥𝗲𝘃𝗲𝗻𝘂𝗲: 𝗜𝘀 𝘁𝗵𝗲 𝗮𝗰𝗰𝗲𝗹𝗲𝗿𝗮𝘁𝗶𝗼𝗻 𝗿𝗲𝗮𝗹?
Consensus is around $917M, against $582.3M in Q2. That’s approximately 57% sequential growth. That’s a demanding hurdle.
But even if they beat revenue ( dont wanna sound too hard) I want to understand how much growth comes from newly deployed capacity versus existing operations. Is the Street getting ahead of the deployment schedule, or is Nebius genuinely accelerating?
𝟮. 𝗠𝗶𝗰𝗿𝗼𝘀𝗼𝗳𝘁: 𝗔𝗿𝗲 𝘁𝗵𝗲 𝗰𝗼𝗺𝗺𝗶𝘁𝗺𝗲𝗻𝘁𝘀 𝘁𝗿𝗮𝗻𝘀𝗹𝗮𝘁𝗶𝗻𝗴 𝗶𝗻𝘁𝗼 𝗲𝘅𝗲𝗰𝘂𝘁𝗶𝗼𝗻?
The $17.4B five-year agreement, potentially rising to $19.4B, is impressive. But contracts don’t generate revenue until infrastructure is delivered.
The Vineland facility is particularly important. I want clarity on power availability, construction, commissioning and delivery schedules. Are these commitments progressing as expected, or are deployment timelines becoming a bottleneck?
𝟯. 𝗣𝗼𝘄𝗲𝗿: 𝗧𝗵𝗲 𝗱𝗶𝗳𝗳𝗲𝗿𝗲𝗻𝗰𝗲 𝗯𝗲𝘁𝘄𝗲𝗲𝗻 𝗽𝗼𝘁𝗲𝗻𝘁𝗶𝗮𝗹 𝗮𝗻𝗱 𝗺𝗼𝗻𝗲𝘁𝗶𝘀𝗮𝘁𝗶𝗼𝗻.
This is probably my biggest operational question.
Nebius has a 5GW contracted-power ambition, but its year-end connected-power target remains 800MW–1GW.
These are two very different things. Contracted power represents potential capacity. Connected power gets the business closer to generating revenue.
How quickly can Nebius close that gap? Is this simply the normal infrastructure buildout cycle, or is monetisation falling behind the headline growth story?
𝟰. 𝗖𝗮𝗽𝗲𝘅: 𝗛𝗼𝘄 𝗲𝘅𝗽𝗲𝗻𝘀𝗶𝘃𝗲 𝗶𝘀 𝘁𝗵𝗶𝘀 𝗴𝗿𝗼𝘄𝘁𝗵?
Nebius has guided for $20–25B in FY26 capex, having already spent approximately $8.13B in H1.
That’s an extraordinary investment relative to $3–3.4B in expected annual revenue.
I want to understand how much additional capital is required, how it will be financed, and whether customer commitments and cash generation can support expansion without excessive debt or shareholder dilution.
𝟱. 𝗨𝗻𝗶𝘁 𝗲𝗰𝗼𝗻𝗼𝗺𝗶𝗰𝘀: 𝗔𝗿𝗲 𝗮𝘁𝘁𝗿𝗮𝗰𝘁𝗶𝘃𝗲 𝗺𝗮𝗿𝗴𝗶𝗻𝘀 𝘁𝗿𝗮𝗻𝘀𝗹𝗮𝘁𝗶𝗻𝗴 𝗶𝗻𝘁𝗼 𝗿𝗲𝗮𝗹 𝗿𝗲𝘁𝘂𝗿𝗻𝘀?
Q2 adjusted EBITDA margin was already 40.6%, with AI Cloud at 49.7%.
That’s encouraging, but EBITDA isn’t free cash flow. Depreciation, interest, stock-based compensation and continuous GPU investment cannot be ignored.
Management’s medium-term EBIT margin target of 20–30% is worth examining against today’s EBITDA margins. Can Nebius turn operating scale into genuine returns on invested capital?
🐊 𝗪𝗵𝗮𝘁 𝘄𝗼𝘂𝗹𝗱 𝗺𝗮𝗸𝗲 𝗺𝗲 𝗺𝗼𝗿𝗲 𝗯𝘂𝗹𝗹𝗶𝘀𝗵?
▪️ Revenue acceleration on good quality
▪️ Microsoft deployments progressing on schedule ▪️ Connected power moving towards 800MW–1GW ▪️ Margins holding up as capacity expands
🚩 𝗪𝗵𝗮𝘁 𝘄𝗼𝘂𝗹𝗱 𝗰𝗼𝗻𝗰𝗲𝗿𝗻 𝗺𝗲?
▪️ Contracted power growing much faster than connected capacity
▪️ Deployment delays
▪️ Escalating financing requirements
▪️ EBITDA growth failing to translate into stronger cash economics
🐊 𝗠𝘆 𝗰𝗼𝗻𝗰𝗹𝘂𝘀𝗶𝗼𝗻
I’m invested in Nebius because I believe AI infrastructure demand has a long runway.
But there’s a big difference between building a business that grows rapidly and building one that generates attractive returns on the capital invested.
The question isn’t how much AI infrastructure Nebius can contract. It’s how quickly it can connect, monetise and earn an attractive return on every dollar invested.
That’s what I’m looking for.
not financial advice.
The Anthropic IPO: 5 Questions the Price Has to Answer $ANT
Anthropic’s $70–78 IPO range implies up to $1.4T “fully diluted”. October run-rate revenue hit $81B; strategic partners are investing $26B.
Extraordinary growth but does the price compensate for the risks?
There are some questions that many are not asking
🐊 1. Who carries the duration risk?
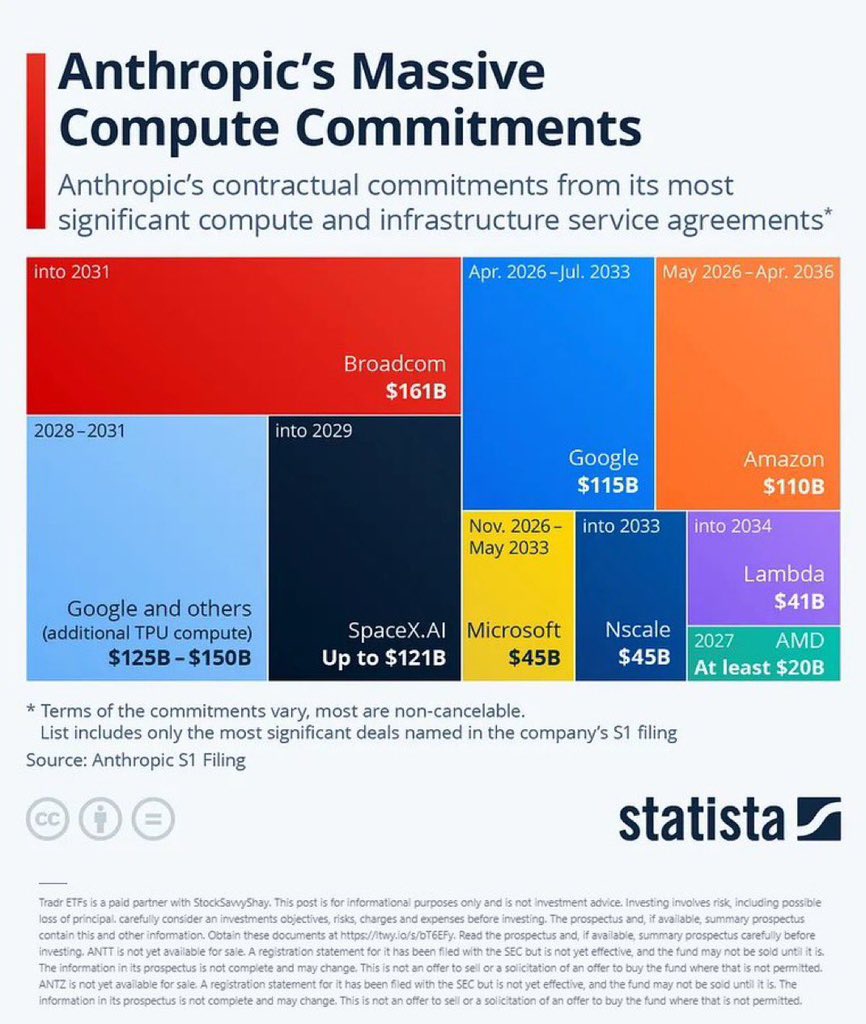
Anthropic has ~$900.9B of compute and infrastructure commitments, with ~$451.6B expected before end-2030 about $106B annually on average. Yet much of its revenue is consumption-based, not locked into long-term contracts.
To be fair, ~$186.2B of commitments have termination rights or conditions. Q3’s issue was too little compute. At Q3’s compute ratio (~58% of revenue), $106B annual spend implies ~$180B revenue. But then again this is a sensitivity, not a forecast.
( refer to attached chart)
Largest named deals from Anthropic’s Oct 26 S-1. Since amended: Google ~$121.3B; total commitments ~$900.9B (Nov 10 S-1/A). Chart: Statista, CC BY-ND.
🐊 2. Are public shareholders in control? No. Founder LLC’s single Class F share carries 50.1% of general voting power. The Long-Term Benefit Trust, with no economic stake, elects four of seven directors. Anthropic is a Nasdaq controlled company.
The Trust can be amended without trustee consent, but only with demanding cross-class approvals.
“You are buying economics, not influence.”
🐊 3. Is $26B from suppliers validation—or strategic alignment?
Google, Nvidia, AMD, Broadcom, Micron, Microsoft and TSMC are investing at the IPO price. That’s less than 3% of Anthropic’s commitments. Several of these investors also appear in the chart attached as Anthropic’s compute counterparties: Broadcom (~$161B), Google (~$121B), Microsoft and AMD.
Real skin in the game but not an independent valuation signal. Class N shares have no underwriter lock-up, though resale restrictions apply.
🐊 4. What are the economics per token?
As a finance person, this is the most imp question for me, unit economics or token economics.
Nine-month operating loss was $1.26B.
Q3’s GAAP operating loss was $567M, attributed mainly to $5B of higher-cost short-term compute and $2B of non-cash donation-matching charges.
Excluding the non-cash charge alone, Q3 would have been roughly $1.4B of operating income.
Near-term liquidity is not the immediate issue: ~$131.9B in cash and short-term investments, plus ~$84.6B estimated net IPO/placement proceeds (at the $74 midpoint, after fees).
Does cost per token fall faster than the price Anthropic can charge?
The breathtaking speed at which tech is changing, I would worry about this question the most
At the top of the range, ~17x October run-rate and ~21x annualised Q3 revenue on a fully diluted basis (~12.6x run-rate on shares outstanding).
🐊 5. How durable is demand—and who owns the channel?
More than 1,900 customers generated at least $1M of trailing revenue; no single customer exceeded 10% of nine-month revenue. Reported NRR is ~900%, using Anthropic’s own qualified-customer metric.
But 44% of nine-month revenue came through cloud marketplaces run by hyperscalers that also sell competing AI products. Quarterly growth slowed from 144% in Q2 to 47% in Q3 still rapid, but slowing sharply.
And $81B run-rate annualises 28 days of consumption fees and one month of subscriptions. It’s a snapshot, not a contract.
My takeaway: Is ~$1.3–1.4T already pricing in years of successful execution? AI may succeed spectacularly and infrastructure suppliers may still capture a disproportionate share of the economics.
Which risk is the IPO price underestimating?
Not financial advice
🐊 $ASTS Q3 Earnings: My thoughts and main question I have been asking for months now, “The technology is progressing. Are the economics?”
I am invested in $ASTS and have been vocal about the good, bad and the ugly.
Just before the earnings I said that the burden of proof had shifted from technological promise to financial delivery.
So here’s how Q3 measured up.
🐊 THE VERY GOOD
▪️ Japan: ~$1B of non-dilutive J-LEO funding. Management expects most of it in 2027, ahead of satellite and launch spend. ASTS owns 49% of the JV, and capacity not used in Japan runs through ASTS's global network for a low single-digit net revenue share to the JV.
▪️ Manufacturing: targeting 6 ASIC satellites a month from December. ASICs were pulled forward to BlueBird 34 (from 50), with ~10x the processing bandwidth of Block 1. Production is running through BB51, and BB28 is in final stages.
▪️ Government: a ~$100M Space Force contract, 16 US government awards to date, and DPAS priority rating for BB20–25 launching in Q1 2027.
🐊 THE GOOD
▪️ FY26 revenue guidance of $150–200M was maintained, and ~45 BlueBirds in orbit by mid-2027 was reiterated.
▪️ Intermittent US coverage is expected by year-end, with beta trials in early 2027 at ~25 satellites. ▪️ Caveat: in orbit isn't the same as operational, and intermittent coverage isn't commercial service.
🐊 THE BAD
▪️ Revenue miss! Revenue was $42.3M vs ~$46–48M consensus, mostly gateways and government milestones. There's still no recurring carrier or consumer satellite-service revenue. GAAP loss was $0.44/share vs ~$0.40–0.42 expected.
▪️ Hitting $150M needs ~$61M in Q4, about 45% above Q3.
▪️ Q3 capex was $310M (under the guide), but Q4 is guided at $400–500M. Q4 opex excluding cost of revenue is guided at $130–140M, up from $109M.
▪️ Cash plus restricted cash was $3.2B vs ~$3.7B pro forma in June. Reported long-term debt is $4.1B, including the $1.15B July convert.
🐊 THE UGLY
▪️ Blacklift adds "several hundred million" of capex in 2027, on top of the Firefly deal. Management declined to guide 2028.
▪️ There's no total programme cost or payback. The key number: cost per launch on Blacklift vs buying external launches. Why become a rocket company before the network proves it can earn a return?
🐊 WHAT MANAGEMENT DIDN'T ANSWER
▪️ How much carrier revenue does ASTS keep? Still undisclosed.
▪️ J-LEO accounting: "we haven't given a lot of feedback yet."
▪️ The $1.2B US "non-dilutive" pipeline is mostly first-lien or capex-support debt, and not yet secured. Non-dilutive isn't free.
▪️ Total capital needed through 2028, and annual replacement capex.
🐊 MY CHECKPOINTS
Blacklift unveiling (Thu, Nov 12): costs, milestones, funding.
December: is 6 satellites a month actually achieved?
Q4: ~$61M revenue to hit the low end of guidance.
Q1 2027: launches of BB14–25 and the beta.
Next earnings: carrier economics, J-LEO cash flows, 2028 funding.
🐊 CONCLUSION ASTS has shown it can build satellites, attract sovereign funding and secure launches. It hasn't shown that this infrastructure produces sustainable FCF after replacement capex and financing costs. That's the question: not whether ASTS can build the network, but whether shareholders make money owning it.
Still holding. Not averaging down until execution, not price, earns it.
My views only. Not financial advice.
$ASTS - Thoughts as an investor and someone covering this stock
Disclosure: I’m invested in $ASTS and I write about it. Still underwater, still holding. Q3 results are due after the US close today, Nov 9.
🐊 Where I stand
In September, I wrote that ASTS had remarkable technology, but its share price was pricing in perfection. The question was never just whether the technology works, but whether it can generate attractive returns on the capital required. I said I’d reassess at $35–45. We’re there. So, what’s changed?
🐊 What’s new?
• Rakuten: The JV is 51% Rakuten, 49% ASTS, with up to ¥148B (~$1B) of Japanese J-LEO funding going to the JV, not ASTS. ASTS supplies satellites; service targets March 2029. This validates sovereign demand, though, not ASTS’s balance sheet.
• Blacklift: ASTS plans an in-house reusable rocket for late 2028. The Firefly deal exceeds $1.3B: $400M cash plus 10–14M shares for the licence, $250M for engines and $250M for engineering.
• External launch agreements now cover 100+ satellites across 2027–28.
🐊 The cash question
ASTS had ~$3.7B pro forma liquidity at June 30, including the July convert. H1 capex was ~$860M; Q3 guidance is $350–425M. Add Firefly payments and 50+ satellites in 2027 at ~$22M each.
My assessment: 2027 looks funded; 2028 looks tight. I put the odds of avoiding a large discounted raise through 2028 at ~40%.
We will find out more in today’s earnings call.
🐊 The bottlenecks (my subjective odds)
• ~45 satellites operational, not just launched, by mid-2027: 55%.
• Attractive, disclosed carrier economics: 50%.
• Blacklift flying on time: 25%.
🐊 What investors may be missing
The ~$1.3B backlog isn’t equivalent to recurring service revenue; it includes gateways and government milestones. And satellites wear out. Replacement capex could consume much of the FCF, even if operating margins look attractive.
🐊 The contrarian view
ASTS should prove it can run a profitable satellite network before becoming a rocket company. Vertical integration may help eventually, but adds capital and execution risk today.
🐊 What does $90 require?
Bulls say its a $90 to $100 stock,
At $90, ASTS is worth roughly $35B. At 20x FCF, that’s $1.75B annual FCF. Assume $5.40 retained per subscriber monthly ($12 × 45%) and a 50% FCF margin after replacement capex. That’s ~54M paying subscribers, before government upside.
Possible, but that’s the bar, not a price target.
🐊 What I’m watching tonight
Revenue: Maintain FY26 guidance of $150–200M? H1 was ~$46M, so H2 needs $104M+.
Deployment: Firm dates for 45 operational satellites and upcoming launches.
Cash: Q3 balance, capex, 2027 spending and ATM/dilution.
Commercial: US service date and carrier revenue split.
Blacklift: Total cost and funding. Details may come Thursday, Nov 12. No detail tonight isn’t a red flag; no detail Thursday would be.
Class action and SpaceX lock-up expiry (Dec 8) remain sentiment overhangs, not fundamental risks.
🐊 Conclusion
Still holding. Not because the stock has fallen, but because the opportunity remains. Rakuten strengthens the strategic case; Blacklift adds complexity. The thesis is alive, but the burden of proof has shifted from technological promise to financial delivery.
My views only. Not financial advice.
When even gold starts behaving like a risk asset, what does that mean?
I am invested in gold / gold mines, significantly, and Thursday's Nasdaq plunged 5.5%, wiping out roughly $2.5T in market value. Gold, which had been rallying hard into the week, gave back part of that gain as the selloff intensified holding up better than equities, but still retreating from its highs at the exact moment stocks were cratering. Silver fell outright.
Gold is supposed to be the hedge. When a safe haven gives up gains while stocks are falling hardest, one explanation is forced liquidation: investors facing margin calls sell whatever's liquid to raise cash including positions that are still profitable. Gold's depth makes it collateral as much as a safe haven.
We've seen this before 2008, March 2020 correlations spiking together in the first wave of panic, then decoupling again.
Add insult to injury:
Friday's gold dip (-0.7%) was also impacted by October jobs report that pushed December rate-hike odds toward 80%, a classic reason for gold to fall on its own.
The real question isn't whether the AI trade is dead it's whether Thursday was a one-day flush or the start of broader deleveraging. And with the Fed now leaning toward a hike rather than a cut, there's less room for easy money to cushion the AI trade if this is more than noise.
Three things I'm watching:
▪️ VIX normalizing or still elevated?
▪️ Credit spreadscontained to equities, or spreading?
▪️ Cross-asset correlations back to normal, or still moving together?
🐊 THE NEW AI BOTTLENECK IS PERMITS.
For the past few years, the AI investment thesis revolved around supply chains: GPUs, HBM, networking, optics and advanced packaging.
Now another bottleneck is emerging:
the ability to actually build AI infrastructure.
Texas is the clearest example. The state has already restricted data-centre approvals, grid connections and environmental permits. Following Gina Hinojosa’s election victory, the prospect of an extended permitting freeze adds another layer of uncertainty.
The market is still deciphering what this means.
🐊 EXISTING BECOMES MORE VALUABLE
If new capacity becomes harder to approve, existing permits, secured power and operational campuses become more valuable.
This is not necessarily a demand problem. It is a supply-side constraint.
And it creates an important distinction between companies with shovel-ready infrastructure and those with ambitious development pipelines.
🐊 WHY THE SELL-OFF MAY BE TOO BROAD
Nebius is an interesting example.
Its key infrastructure projects are outside Texas, meaning it does not have the same direct exposure to the Texas permitting freeze.
Yet companies like Nebius are getting smoked alongside developers facing more immediate regulatory obstacles.
That does not make Nebius immune. Financing, construction, customer concentration and execution remain real risks.
But if the market is indiscriminately repricing AI infrastructure companies, geography and permitting exposure may matter more than investors currently appreciate.
🐊 THE THESIS IS NOT BROKEN. IT HAS AN EXTRA HOP.
AI demand still requires compute.
Compute requires data centres.
Data centres require power, grid connections, land, permits and infrastructure.
The investment thesis has not disappeared. It has become more complex.
The extra layer of permitting and regulatory risk could push timelines out, increase costs and change which companies capture the economics.
🐊 WHERE I’M LOOKING
▪️ Companies with existing permits and secured power.
▪️ Non-Texas infrastructure developers with credible execution.
▪️ Power generation, electrical equipment and grid infrastructure.
▪️ Developers whose share prices imply a much worse outcome than their underlying projects justify.
The key distinction: a permitted site with power is not equivalent to a speculative pipeline of future megawatts.
The market may be right to demand a higher risk premium.
But when it prices every AI infrastructure company as if the same bottleneck applies, it may create opportunities.
The question is no longer simply who has the best chips.
It is who can actually get the infrastructure built.
Not financial advice.
🐊 LUMENTUM ($LITE): Is getting smoked, after $MRVL deal, Is there an opportunity?
I’ve owned Lumentum and written about photonics for a while. In my previous post, I questioned whether Marvell ($MRVL) could justify the financial burden of acquiring LITE. The strategic logic made sense. The economics were my concern.
That concern has intensified.
$MRVL’s share price has come down by circa 32% and LITE has come come down circa 26% 😏
🐊 What is happening?
The definitive all-stock deal offers 4.5 MRVL shares per LITE share. The $1,132 headline value was based on MRVL’s unaffected October 28 close of $251.65.
But MRVL closed at $171.41 on November 2. That puts the implied LITE consideration at approximately $771. LITE closed at $684.40, an 11.3% discount.
The original 23.9% premium has effectively disappeared. LITE is now trading below its pre-deal reference value.
🐊 The MRVL connection
Every $10 move in MRVL changes LITE’s implied merger value by $45. This is a fixed exchange ratio, not a guaranteed cash payout.
If MRVL falls further, LITE’s implied consideration falls with it. Until closing, I’m effectively exposed to Marvell’s share price, alongside the risk that the deal fails.
🐊 What are investors worried about?
▪ Marvell’s shareholders must approve a massive acquisition after MRVL has already fallen sharply.
▪ Integration, manufacturing capital intensity and capacity capex.
▪ Regulatory approvals, including potential Chinese review and delays.
▪ Customer conflicts. NVIDIA invested $2B in Lumentum. What happens when its optical supplier becomes controlled by a custom-silicon competitor?
▪ Whether the promised $1B+ synergies and year-one EPS accretion actually materialise. These remain management targets, not guarantees.
🐊 My perspective
I bought LITE for its underlying photonics business, not a speculative takeover premium.
Lumentum’s
Q1 FY2027 revenue reached $1.26B, up 136.5% YoY. Q2 guidance points to $1.575B–$1.625B.
The business is not suddenly collapsing.
But if the deal closes, I won’t own a photonics pure-play. I’ll own approximately a third of a combined Marvell business.
🐊 What next?
I dont have a choice but to monitor
- MRVL’s valuation,
- LITE’s revenue and margins,
- shareholder votes,
- regulatory developments,
- capacity capex and
- NVIDIA’s response.
I’m not rushing to average down. The underlying business remains strong, but the financial structure of this deal has materially changed my investment thesis.
The question is no longer just how much photonics will grow. It’s who captures the economics, and at what price.
I own LITE. Not financial advice.
The market sold $APLD as just another neocloud. Perhaps it was afraid of Coreweave and overall tech bearish sentiment.
APLD owns no GPUs. It collects rent on 15-year take-or-pay leases. The question may be less about what it builds and more about who pays for it, and today that's almost entirely one tenant whose own credit is under strain.
I modelled the equity: roughly $15/share probability-weighted, a touch below the ~$18 it traded at when I wrote it. Perhaps not a bargain yet, but closer than the selloff suggests.
https://t.co/b9wir53dUY
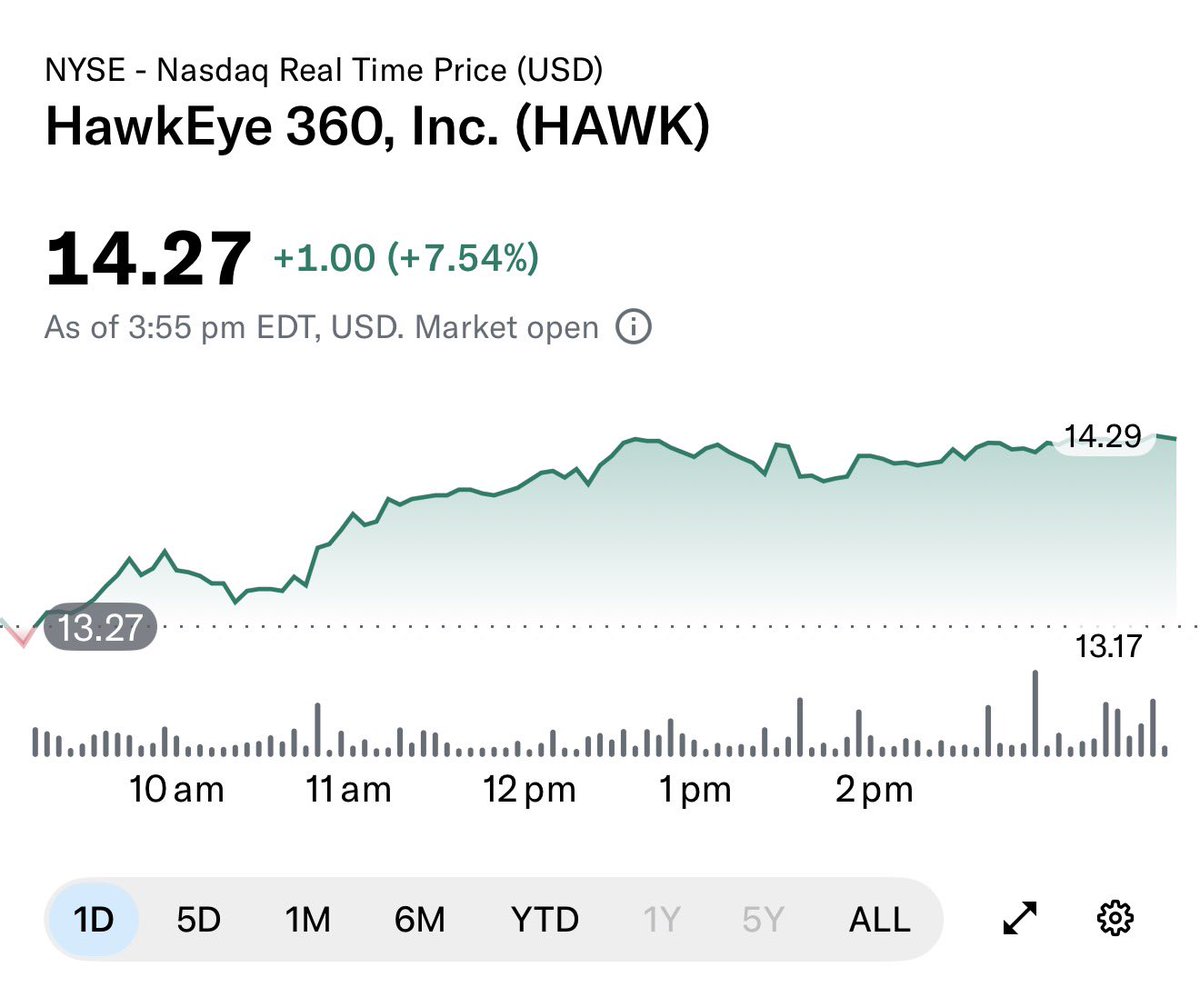
🐊 HAWK: Is the Post-IPO Selloff an Opportunity? I’m Considering a Starter Position
I prefer buying businesses when expectations reset, not when everyone is chasing the same story. HawkEye 360 ($HAWK) is now on my radar.
🟩 What I Like
HAWK operates satellite clusters that detect and locate radio-frequency signals, including radar and GPS jamming. Its customers include US intelligence agencies and allied defence ministries. It operates in a strategically important market as demand for space-based intelligence grows.
Q2 2026
revenue rose 87% year-on-year to $49.8M. International revenue hit a record $21M (+134%), and
backlog stood at $292.2M.
Free cash flow was positive at $5.4M.
Management guides FY26 revenue of $215–220M and adjusted EBITDA of $30–36M.
The reset is what interests me. The stock fell after Q2 despite strong revenue growth and reaffirmed guidance. It traded near 12x sales in August. At around $13–14, using June cash of $503M, the enterprise value is roughly $800–900M, or around 4x guided FY26 sales.
🚩 What Could Go Wrong?
Q2 still showed a $15.3M GAAP net loss, and stock-based compensation creates dilution risk.
Customers are governments, making revenue sensitive to budgets, procurement cycles and lumpy international awards.
Satellite launches carry execution risk, while the stock has shown extreme volatility.
The H2 ramp must materialise. H1 revenue was $99.6M, so H2 needs roughly $115–120M. Management expects Q3 and Q4 revenue to exceed Q1 and Q2, with Q4 higher than Q3.
🐊 My Strategy
A starter position, not a full commitment.
🟩 I add if: Q3 revenue supports the required second-half ramp, full-year guidance holds, and cash generation remains healthy.
🚩 I rethink if: guidance is cut, the H2 ramp slips, or growth fails to translate into sustainable cash flow.
HAWK could be an interesting defence-intelligence growth story at a far more reasonable entry price. But it is speculative, not a conventional value stock. I’d rather start small and earn the right to add than assume the selloff has created a bargain.
Not financial advice.
🐊 Alphabet Earnings My Thoughts As Shareholder for Years:
>AI Is Growing.
>Search Hasn’t Proved It Can Monetise AI Yet
I’ve been holding Google for years, so I look at these results as a shareholder, not just an observer. I believe in the business, but holding a stock doesn’t mean ignoring the warning signs. Here’s what stood out to me this quarter.
🐊 What happened?
▪️ Revenue reached $127.6B, up 25% year over year, but below LSEG’s $128.2B estimate. Shares fell around 10% after hours.
▪️ GAAP EPS was $2.12 versus roughly $3.02 expected. An ~$8.7B investment-related loss, primarily an unrealised loss on SpaceX, weighed on earnings. Excluding that loss, EPS would have been roughly $2.67, still below expectations.
▪️ Operating income rose 30% to $40.6B, but missed the ~$43.2B estimate. Growth remains strong; delivering below expectations is a different question.
🐊 The Search warning
▪️ Search revenue reached $63.35B, up 12% year over year, versus 17% growth in Q2. Revenue was essentially flat sequentially.
▪️ Yet management reported its fastest Search query growth in five years. More queries, but slower revenue growth: that gap deserves attention.
▪️ Management acknowledged that AI Mode currently monetises less effectively than traditional Search. However, it also cited foreign exchange as the biggest driver of the sequential slowdown, tougher comparisons with late-2025 growth, and weakness in certain advertising categories.
▪️ I don’t think this proves AI is killing Search. But Google must demonstrate that AI-driven usage can translate into comparable advertising economics.
🐊 Cloud versus cash flow
▪️ + Google Cloud revenue surged 103% to $30.7B. Operating income reached $11.1B, implying a 36.2% margin. AI is already generating meaningful commercial returns.
▪️x But capex is expected to reach $195–205B in 2026, with management signalling a significant increase in 2027.
▪️x Free cash flow was negative $9.1B for the second consecutive quarter. The $5.2B European Commission fine and inventory investment affected cash generation; excluding the fine alone, cash flow would still have been negative.
▪️x Long-term debt rose to $125.1B from $21.6B a year earlier. However, Alphabet also held $265.1B in cash and marketable securities, so this isn’t a straightforward balance-sheet distress story. Some securities are volatile equity investments, including the SpaceX exposure that hurt earnings.
🐊 What I’m watching next
▪️ Q4 Search growth faces additional FX headwinds and tougher comparisons. A further slowdown alone won’t prove AI disruption.
▪️ Google is expanding AI Mode ads to 10 additional markets, including Australia, and introducing ads in US follow-up queries. The test is whether monetisation improves.
▪️ Cloud margins may face near-term pressure as third-party computing capacity ramps up.
🐊 My conclusion
As a long-term holder, I’m not abandoning the Google thesis because of one quarter. Cloud has demonstrated that AI can generate substantial revenue and profits. Search hasn’t yet proved that its new AI experiences can preserve traditional advertising economics.
Meanwhile, infrastructure spending keeps rising. These risks compound: Google must protect its core cash engine while funding its next one.
For me, the question is whether the current valuation adequately reflects that challenge. I’ll be watching monetisation and cash returns, not AI adoption headlines alone.
Not financial advice. Past performance does not guarantee future results.
🐊 I Own LITE. Here are my thoughts About a Potential Marvell Deal.
I’ve owned Lumentum ($LITE) and written about photonics for a while now. Bloomberg’s report that Marvell ($MRVL) is in advanced talks to acquire LITE. LITE rose roughly 9% after hours; MRVL fell more than 8%. No deal has been confirmed.
Here’s how I’m thinking about it.
🐊 1. First principles: What is Marvell actually buying?
Marvell brings DSPs, networking silicon and custom chips.
Lumentum brings the lasers and optical components that help move data.
Owning both sides of the connection makes strategic sense. But there’s a catch: Marvell is moving from a relatively asset-light chip business into a much more manufacturing-intensive business. The capital requirements, margins and operational risks are different.
Strategic fit doesn’t automatically mean financial fit.
🐊 2. Second-order thinking: Who stops buying?
Lumentum supplies components used in optical systems built around other companies’ technology.
If LITE becomes a Marvell subsidiary, will customers tied to competing platforms reconsider how much they source from it?
Nvidia is particularly interesting: it has invested $2B in Lumentum and also has a commercial relationship with it. Would customers become more cautious about depending on a supplier controlled by Marvell?
Coherent ($COHR) could benefit if customers diversify, but that possibility is already attracting attention. The question is whether the market has priced it in.
🐊 3. Inversion: How could this destroy value?
Marvell has about $3.92B in cash. Lumentum’s reported market value was around $83B, versus roughly $221B for Marvell.
This is likely to require substantial stock issuance, financing or both.
The failure scenario is straightforward: Marvell pays a premium for scarce laser capacity, capacity eventually catches up with demand, pricing power fades, and shareholders absorb dilution.
The market’s initial reaction suggests investors are already asking whether the price is too high.
🐊 4. What does this mean for me as a LITE holder?
If the deal is predominantly stock, I’m not simply being bought out. I’m exchanging my exposure to Lumentum for exposure to Marvell, including its other businesses, risks and capital-allocation decisions.
When terms emerge, I’ll focus on the cash/stock mix, premium to the undisturbed price, any collar, break fee, customer reactions and regulatory timeline.
My take: Look I like the strategic logic, but I’m not automatically celebrating. A premium matters, but so does the value of the shares I receive. I’d rather own a great business at a sensible price than accept a deal simply because the headline sounds bullish.
The real question isn’t whether photonics has a future. It’s who captures the economics, and how much we pay for them.
Not financial advice. I own LITE. Past performance does not guarantee future results.
🐊 THE FED PAUSED. THE REAL TEST IS WHAT HAPPENS NEXT. MY SEPTEMBER FRAMEWORK STILL HOLDS
In a note earlier this week, I argued that predicting the Fed matters less than understanding what markets have already priced in. Today's decision reinforces that framework.
🐊 1. What did the Fed decide?
🔹 Rates held at 3.75–4.00%, 10–2.
🔹 Lisa Cook and Beth Hammack dissented, favouring a hike. Cook's dissent, her first ever, was unexpected, and some economists read it as raising questions about Fed independence.
🔹 Growth was upgraded to "strong"; inflation "remains elevated."
🐊 2. What does it mean?
A pause is not a pivot. With inflation still above target, December remains live. But the Fed needs more data before committing to another move.
🐊 3. What are bonds saying?
🔹 Most of the yield rise came before the announcement. Post-decision, the 2-year was near 4.78% and the 10-year near 5.05%.
🔹 The announcement barely moved the 2-year. Markets had largely priced in a hawkish hold.
🔹 My September thesis still matters: the long end reflects inflation expectations, government borrowing and term premium, not just the Fed.
🐊 4. Why should equity investors care?
🔹 AI and semis: A 10-year yield around 5% raises the hurdle rate for expensive growth stocks and debt-funded data-centre investment.
🔹 Earnings matter more now: Microsoft and Alphabet's cloud growth and capex guidance may tell us more about semiconductor demand than the Fed statement.
🔹 Energy and inflation: Higher energy costs can keep inflation sticky, even when rate hikes cannot directly fix the supply shock.
🐊 5. What am I monitoring?
🔹 Next few days: US Q3 GDP and September PCE inflation, plus the read-through from Microsoft and Alphabet's results (reported after the US close on 28 October).
🔹 November: Jobs, wages, inflation and energy prices.
🔹 Treasuries: Does the 10-year remain above 5%, and do 2-year and 10-year yields diverge?
🔹 Credit spreads: Is higher borrowing cost beginning to stress companies?
🔹 December: The next Fed decision.
🐊 6. What are the December odds?
If inflation stays sticky and growth strong, yields and valuations could face pressure for weeks before December. If inflation cools, the market may reverse that trade.
There's also a risk scenario: if conflict in the Middle East escalates after the midterms and oil prices rise, that would add further pressure on inflation and complicate the Fed's path.
My takeaway:
The Fed sets the short-term rate. The bond market helps set the price of everything else. Watch what gets repriced next.
Not financial advice.
ASTS is up today: The Thesis Is Alive. Are The Economics?
$ASTS closed ~ $42 Oct 27, up ~ 8.3%, extending its rebound from the Oct 23 low of $36.72. Short covering may be contributing, but a price bounce alone tells us little about the business.
I’ve held ASTS for some time, experienced its ups and downs and written about it in detail. Net-net, I’m underwater. I’m not exiting yet, but I’m trying to assess the investment rationally, not defend it emotionally.
What still holds from my September thesis?
🐊 Direct-to-phone satellite connectivity is a potentially transformative market.
🐊 ASTS has meaningful carrier relationships, a differentiated broadband ambition and a potential wholesale business model.
🐊 My central question remains: ASTS doesn’t ‘just’ need to work. It needs to earn attractive returns on capital. Which for those who have been reading me know that I always say, as critical for a capital intensive business like this.
🚩 However, there is always a however, What isn’t holding up as well?
🐊 Deployment has slipped. Management now targets approximately 45 satellites in orbit by early 2027, not year-end 2026.
🐊 Piper Sandler cut its end-2026 satellite forecast from 45 to 18, pushed US commercial service to H2 2027 and lowered its assumed monthly service price from $15 to $12. That directly challenges the economics.
🐊 SpaceX’s proposed $8B acquisition of nationwide 800 MHz spectrum adds a serious competitive threat, although the deal still requires regulatory approval. Competition could also make ASTS more valuable to carriers seeking alternatives.
🐊 A lower share price isn’t automatically a margin of safety. Q3 capex guidance was $350–425M, and ASTS raised $1.15B gross through convertible notes in July.
🐊 What am I monitoring next?
🐊 Revenue: H1 revenue was about $46M against FY26 guidance of $150–200M. Can management maintain that guidance on Nov 9?
🐊 Execution: Satellites actually launched, deployed and operational not just manufactured.
🐊 Capital: Cash burn, capex, dilution and funding requirements for 2027.
🐊 Unit economics: What does ASTS retain per subscriber after carrier revenue sharing?
🐊 Competition: Can ASTS maintain a meaningful advantage as Starlink expands?
My thesis hasn’t collapsed, but execution risk has risen. I’m still holding. The burden of proof has shifted from technological promise to financial delivery ( says my ex CFO brain)
My views only. Not financial advice.
Adding this stock to my watchlist! 🐊
DIODES ($DIOD): A Semiconductor Recovery the Market May Be Underestimating?
I’m looking beyond the obvious AI winners for companies that could benefit from the infrastructure buildout without needing to sell the next GPU.
Diodes Incorporated is one name worth examining.
🐊 WHAT DOES DIOD DO?
Diodes makes components that help electronics manage power, protect circuits and move signals. Its products serve automotive, industrial, computing and consumer markets.
AI servers need more than processors. They also need power-management and supporting components. DIOD has exposure to that opportunity, but it is a diversified semiconductor supplier not a pure-play AI stock.
🟢 THE NUMBERS ARE IMPROVING
Q2 2026:
• Revenue: $445.5M, up 22% YoY.
• Adjusted EPS: $0.70, versus $0.32 a year ago.
• Gross margin: 33.1%, versus 31.5%.
• Free cash flow: $34.8M.
Q3 guidance is even more striking:
• Revenue: $510M ±3%, implying 30% YoY growth at the midpoint.
• Gross margin: 35% ±1%.
• Non-GAAP EPS: $1.05 ±$0.10 a 2.8x YoY improvement, according to management.
🐊 THE CHANNEL SIGNAL
Global point-of-sale activity reportedly reached records, while channel inventory fell below Diodes’ normal 11–14-week range.
That matters. Lean inventory alongside stronger demand makes a near-term recovery more credible than a rebound driven purely by customers restocking. It doesn’t eliminate semiconductor cyclicality, but it strengthens the case.
🚩 WHAT IS WALL STREET SAYING?
On October 23, Needham initiated coverage with a Buy rating and a $110 target.
BofA also has a Buy rating and a $135 target.
Some published consensus estimates are higher still.
At roughly $81, DIOD is about 36% below its $125.99 52-week high. The opportunity is the gap between current expectations and what earnings could become not simply the gap between price and analyst targets.
WHAT DO THE OPTIONS SUGGEST?
The available October 21–22 snapshot showed puts carrying higher implied volatility than calls, with a bearish skew of around 7.7 percentage points and a reported implied move of roughly $15.63 around an $89 share price.
That points to demand for downside protection and meaningful uncertainty not a guaranteed fall.
Options can reflect hedging as well as directional bets, and this snapshot is dated.
💰 IS DIOD A BUY?
At approximately $81, annualising Q3 guidance gives $2.04B revenue and $4.20 non-GAAP EPS—roughly 19x run-rate earnings.
Those figures resemble management’s three-year targets of $2B revenue and over $4 EPS, potentially reached earlier than planned. But annualising one quarter can flatter the picture; execution must confirm it.
ElevATE adds another growth lever, with around $50M in revenue expected in its first 12 months.
KEY DATES TO WATCH
November 5: Q3 results after the US close; earnings call at 5pm ET. That is Friday morning in Sydney.
November 20: Next notable options expiry to monitor for changes in positioning.
For results, I’ll watch
revenue near $510M,
gross margin of at least 34%,
EPS against the $1.05 midpoint, and
management’s commentary on demand and inventory.
My view: DIOD is worth watching. The recovery has evidence behind it, but I want execution not analyst targets or options positioning to confirm the opportunity.
I might open a starter position and monitor / see where it goes.
Not financial advice. Past performance does not guarantee future results.
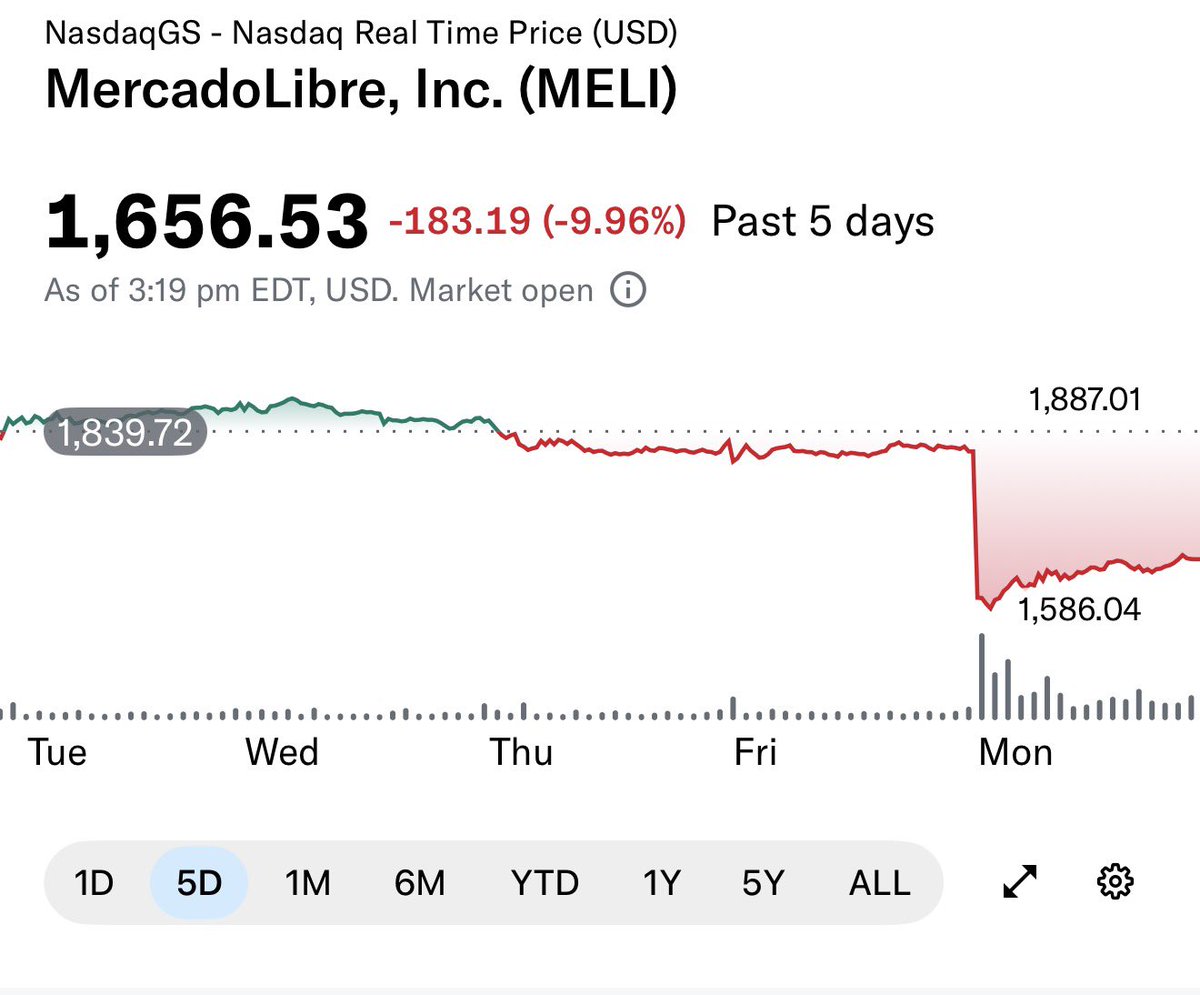
Brazil’s Political / Stock Market Shock: Is $MELI an Opportunity or Growth Trap? 🇧🇷
Lula’s comeback victory (51.75%–48.25%) jolted Brazilian markets. The Ibovespa plunged around 15% in reports of the sell-off, while the real came under severe pressure. $MELI fell sharply and closed October 26 around $1,643 roughly 32% below its October 2025 peak of $2,428.
My first thought goes to MELI which has been on my warchlist for a long time, and question for me, that if this is a good time to invest.
So these are the things I looked at;
🐊 The currency impact on MELI
Brazil generated 52.6% of MELI’s 2025 revenue and financial income. If the real’s dollar value stays roughly 11% lower, the mechanical translation sensitivity is about a 5.7% reduction in reported totals, before changes in demand or costs.
Mexico and Argentina contribute another 43%. That diversification helps, but Argentina brings its own currency and economic risks.
🚩 The biggest risk: a growth trap
At roughly 45x trailing earnings, MELI is not a value stock. It’s a growth stock.
Q2 revenue and financial income grew 50% year-on-year, yet operating income fell 17% to $683M and operating margin was 6.7%.
That divergence matters. Growth is impressive; converting it into earnings is the test.
Political uncertainty could keep Brazilian borrowing costs elevated. Mercado Pago faces funding-cost pressure, potential credit deterioration and tighter lending spreads. Tax or regulatory changes could add further risk.
Three scenarios
🔴 Bear: The real moves towards R$5.60–6.00, demand weakens and credit losses rise. If trailing EPS fell 10% to $33 and the multiple compressed to 35x, implied value would be about $1,155 roughly 30% downside from $1,643.
🟡 Base: The real remains volatile, growth continues and margins stabilise around 6.5–7%. At $36.75 EPS and 45x earnings, implied value is about $1,654 essentially flat. Upside needs earnings growth, not just better sentiment.
🟢 Bull: Fiscal concerns ease, the currency stabilises and margins recover towards 8%. If EPS grows to $40 and the market pays 50x, implied value is $2,000 around 22% upside.
These are illustrative sensitivities, not price targets. The assumptions are deliberately exposed so they can be tested.
My decision: a small starter position.
Q3 results are provisionally scheduled for November 4, following the November 3–4 Copom meeting. I can’t time the bottom, so I’m accepting limited initial exposure ahead of both events rather than making an all-or-nothing bet.
My checkpoints: Brazil FX-neutral GMV growth above ~30% (allowing deceleration from Q2’s 39%), operating margin holding around 6.5% or better, and 15–90-day delinquencies stabilising. These are my own thresholds, not consensus estimates.
If margins keep falling while credit quality deteriorates, I won’t add simply because the stock is cheaper.
The upside is a powerful regional platform bought after a major repricing. The risk is that revenue keeps growing while earnings fail to catch up.
Not financial advice. This is my personal investment decision, and I could be wrong.
The Rain Was Priced In. Did My September Fed Thesis Age Well? And What Should We Watch Now about Fed’s decision
Back in September (in my detailed post below), I predicted the Fed would raise rates. It did. But my argument was never just about getting the decision right. I believed the hike was largely priced in, and that the real signal would come from what the bond market did next.
I laid out the framework in my original piece: https://t.co/4XSYP5SOUS
The central question was whether the 2-year and 10-year Treasury yields would move together or diverge. The Fed influences the short end, but the long end reflects a much wider set of forces, including inflation expectations, government borrowing and the premium investors demand to hold long-term debt.
Looking back, the thesis was that investors needed to look beyond the headline. The rate hike was expected; the market’s reaction was where the real information lay. Long-term yields subsequently pushed higher, reinforcing why the long end deserved close attention.
🐊 Now, with another Fed decision approaching, the same framework still applies.
A hold is not automatically bullish. A hike is not automatically bearish. What matters is the gap between expectations and reality.
What is already priced in?
What could genuinely surprise the market?
Will the 2-year and 10-year yields confirm the same message, or tell us two different stories?
And what could that mean for equity valuations, particularly growth stocks?
I’m not making a prediction yet. First, I want to establish what the market expects and identify the signals that would confirm or challenge the thesis.
The lesson from September is simple: don’t just predict what the Fed will do. Understand what the market has already priced in, and watch what happens when reality arrives.
Not financial advice.
https://t.co/uMSYKmtUmS
🐊 AAOI is down ~71% from its high. Buying opportunity or value trap?
X and substack, including large influencer accounts are lamenting the sell-off, questioning why $AAOI is being punished so heavily. Well, no surprise, the immediate trigger is broader sector pressure. Broadcom and Intel’s October 12 warnings raised concerns about AI infrastructure funding, weighing on optical stocks and sentiment.
But lets not forget, AAOI also has its own baggage. Its nearly $600M ATM offering ran from August 21 to October 5 its third ATM of 2026. Shares were sold at an average $105.36. The stock now trades 36.1% below that price.
So how to cut through the noise and assess this objectively? What am I thinking?
🟢 The opportunity:
🔹Q2 revenue grew 86% YoY to $191.9M.
🔹Management expects Q3 revenue of $255M–$290M, with demand outpacing capacity through mid-2027.
🔹It is targeting roughly 650,000 units per month by year-end.
🚩 The risks:
🔹GAAP gross margin fell to 27.7%, from 30.3% a year ago and 29.1% in Q1.
🔹The net loss widened to $22.8M.
🔹Heavy capex, component shortages and production constraints make execution critical.
🐊 The dilution question: My calculations suggest the share count has increased ~13% since May. The offering raised about $588M net, but shareholders need to see whether that capital generates sufficient returns.
And valuation?
At $67.28 (October 22 close), AAOI’s market cap was roughly $6.1B. Annualising Q3 guidance midpoint implies ~$1.09B in revenue, or ~5.6x sales.
That’s a conservative lens for a company mid-ramp. May-era 2027 forecasts of ~$2.57B imply closer to 2.4x sales. Management has discussed potential annual revenue above $5B, but those older forecasts need re-examining.
At ~28% gross margin, even 2.4x sales isn’t automatically cheap. If the ramp slips or pricing weakens, the valuation can compress quickly.
The answer depends on which revenue number you believe. November 5 is the next major test.
What I’m watching: Q3 revenue of $255M–$290M, non-GAAP EPS of $0.11–$0.26, nearly 5x sequential growth in 800G revenue, improving margins and evidence that growth can translate into sustainable profits.
My view: I don’t own AAOI, and it’s worth investigating. But a 71% drawdown is not a valuation thesis. I’d rather miss the first leg of a recovery than confuse a falling share price with a margin of safety.
Would you buy before earnings, wait for results, or stay away?
Not financial advice.
ONON: Is this a Buying Opportunity or Have I Missed the Rebound?
I posted a while back when I invested in $DECK, and at same time I’ve been watching On Holding ($ONON), and the investment case is getting interesting.
🟢 What I like
🐊 Q2 revenue reached CHF 850.3M, up 21.6% at constant currency.
🐊 DTC sales grew 26%, while gross margin expanded to 65.4%.
🐊 Management’s 2029 target is CHF 5.6B+ in sales, alongside adjusted EBITDA margins above 22%.
🐊 The company has also authorised up to $1B in share repurchases through 2029.
🐊 The founders also bought 60,000 shares each at $36.64 in May.
🐊 Worth watching, although insider buying alone doesn’t make a stock cheap.
🚩 What I dont like
🐊 Wholesale growth slowed from 25.1% in Q1 to 12.7% in Q2 at constant currency.
🐊 Management says it deliberately restrained wholesale shipments, but the real test is whether underlying consumer demand remains strong, particularly in the Americas.
🐊 ONON is also moving its average price point higher. That supports premium positioning, but it raises a question: how much further can prices rise before customers push back?
💰 Would I buy at ~$34.4?
🐊 At roughly 20x consensus FY2026 EPS of $1.73, ONON isn’t obviously cheap, but it isn’t necessarily expensive if management delivers.
🐊 The 2029 targets require substantial execution: adjusted EBITDA must grow roughly 78% from the 2026 guidance midpoint.
I’d build a position in stages rather than chase the rebound.
For the next tranche, I’d look for DTC growth above 30% at constant currency, gross margins holding around 65% or better, and evidence that Americas wholesale demand is stabilising.
If wholesale weakness persists, the deliberate-restraint explanation becomes harder to defend.
🐊 My conclusion:
The market may have overreacted to ONON’s slowdown, but the rebound has raised the bar.
I’m interested, not blindly bullish. Q3 should help determine whether this is a durable premium sportswear compounder or a great brand facing tougher growth ahead.
Not financial advice. Do your own research.
A new position I’ve Invested in
🐊 Workiva ($WK). Here’s Why.
While the market worries about AI replacing software, I’m looking for businesses where AI could strengthen mission-critical workflows.
Workiva provides software for financial reporting, compliance, audit and sustainability reporting. These are areas where accuracy, traceability and control matter.
🐊 What I like
✅ Revenue grew 19% YoY to $255M in Q2 2026, with subscription revenue also up 19%.
✅ Free cash flow was $78M, versus $49M a year earlier. However, Q2 is seasonally strong; full-year FCF margin guidance is around 21%.
✅ Gross retention was 97% and net retention 111%. Encouraging numbers, although net retention also reflects pricing and expansion of existing solutions.
🟢 My thesis
Workiva has recurring revenue, sticky enterprise customers and a position in complex reporting workflows. I believe AI could enhance its value rather than simply make it obsolete.
🚩 What could go wrong?
GAAP operating margin was just 4.6%, versus 16.8% on a non-GAAP basis.
Stock-based compensation and dilution deserve close scrutiny, particularly alongside buybacks.
Competition, pricing pressure and valuation are other risks. A good business is not automatically a good investment at any price.
I’ve invested because I see a potentially durable enterprise software business but future cash generation must justify the price I pay.
The question: can Workiva turn its sticky customer relationships into durable per-share value in the AI era?
I own shares in Workiva. Not financial advice.