🔋 INDIA’S BATTERY BOOM: 6X DEMAND OPPORTUNITY BY 2030
India’s advanced chemistry cell (ACC) demand could rise from around 25 GWh in 2026 to 140–150 GWh by 2030. EVs are expected to contribute 60–70% of this demand.
🏭 Two companies building for the opportunity:
1️⃣ Amara Raja Energy & Mobility
- ₹9,500 Cr Telangana Giga Corridor
- 16 GWh lithium-cell ambition by FY30
- NMC and LFP cell manufacturing plans
- BESS and battery-pack capacity expansion
2️⃣ Exide Industries
- 6 GWh Bengaluru lithium-ion gigafactory commissioned in September 2026
- NMC and LFP cell plans
- Phase 2 expansion to be evaluated near 80% utilisation
- Automotive OEM revenue expected around February 2027 / early Q4 FY27
📈 Where demand could come from
- Electric vehicles
- Grid-scale and stationary energy storage
- Telecom and mobility battery packs
🔍 VALUE TRACK VIEW
The opportunity is structural, but capacity announcements alone do not guarantee returns.
Watch closely:
- Capacity utilisation and ramp-up
- Manufacturing cost competitiveness
- Customer qualification and order conversion
- Localisation and supply-chain depth
- Working capital and return on capital
Our view: The long-term battery opportunity is attractive. The real winners will be companies that convert capacity into competitive products, customer orders and sustainable cash flows.
▶️ YouTube: https://t.co/YAV6QVfvST
Educational content only. Not investment advice. Verify company announcements before making investment decisions.
#BatteryManufacturing #AmaraRaja #ExideIndustries #EVIndia #BatteryStorage #Gigafactory #EnergyTransition #ElectricVehicles #MakeInIndia #IndianStocks #StockMarketIndia #ValueTrackInvesting
📊 4 LOW-PRICE STOCKS SHOWING BUSINESS GROWTH — ARE THEY REALLY UNDERVALUED?
A closer look at four Indian companies featured in Financial Express:
🔹 NMDC
- Article P/E: 8.34x
- Three-year sales CAGR: 22%
- Zero debt, but FY26 ROCE of 3.2% needs attention.
- Growth ambition: 100 MT production by FY30.
🔹 Suzlon Energy
- Article P/E: 23.22x
- Three-year revenue CAGR: 41%
- ROCE: 30.6%
- Suzlon 2.0 targets expansion into solar, battery storage and energy management.
🔹 Websol Energy Systems
- Article P/E: 8.97x
- Three-year revenue CAGR: 293.5%
- ROCE: 48%
- Capacity expansion and backward integration are key growth drivers.
🔹 GK Energy
- Article P/E: 8.71x
- Three-year revenue CAGR: 81.9%
- Three-year net profit CAGR: 172.7%
- Target: Build a US$1 billion enterprise by 2030.
🧠 VALUE TRACK VIEW
Low share price does not automatically mean undervaluation.
- NMDC: Monitor capital efficiency.
- Suzlon: Monitor earnings growth.
- Websol: Monitor capacity ramp-up and solar-sector risks.
- GK Energy: Monitor EPC execution and working capital.
The real test is sustainable earnings, cash flow, valuation and execution.
📌 Article-reported prices and P/E ratios are dated 9 November 2026, not live market data.
▶️ Watch more analysis on YouTube:
https://t.co/YAV6QVfvST
Educational content only. Not investment advice.
#NMDC #SuzlonEnergy #WebsolEnergy #GKEnergy #PennyStocks #SmallCapStocks #IndianStockMarket #UndervaluedStocks #StockAnalysis #ValueInvesting #RenewableEnergy #SolarStocks #ValueTrackInvesting
☢️ MORE NUCLEAR POWER, MORE NUCLEAR WASTE — TWO ENGINEERING STOCKS TO WATCH
India’s ambition to expand nuclear power capacity to 100 GW by 2047 creates opportunities beyond reactor construction — including radioactive waste storage, handling and spent-fuel management.
🔹 Walchandnagar Industries
- Disclosed project references at Tarapur, Kalpakkam and Trombay.
- Q2 FY27 revenue: ₹93.53 Cr, up 81% YoY.
- EBITDA: ₹13.42 Cr; PBT: ₹0.47 Cr.
- Watch: Negative H1 operating cash flow and rising borrowings.
🔹 Larsen & Toubro
- Capabilities include spent-fuel casks, radioactive waste storage tanks and fuel-reprocessing equipment.
- H1 FY27 Heavy Engineering order inflows: ₹4,300 Cr.
- Nuclear-specific order book and revenue contribution are not separately disclosed.
🧠 VALUE TRACK VIEW
Walchandnagar has more direct disclosed nuclear-waste project references, but profitability, cash flow and debt need close monitoring.
L&T has broader engineering capabilities and stronger financial scale, although its nuclear-specific opportunity is not clearly quantified.
The nuclear theme is promising, but the investment case must be supported by confirmed orders, execution and revenue visibility.
Key monitorables:
- Nuclear project tender conversion
- Confirmed order inflows
- Working capital and cash flow
- Nuclear-specific revenue contribution
- Project execution timelines
▶️ Watch more analysis on YouTube:
https://t.co/YAV6QVfvST
Educational content only. Not investment advice. Verify company disclosures before investing.
#NuclearPower #NuclearEnergy #NuclearWaste #WalchandnagarIndustries #LarsenAndToubro #LT #EngineeringStocks #InfrastructureStocks #EnergyTransition #MakeInIndia #IndianStockMarket #ValueTrackInvesting
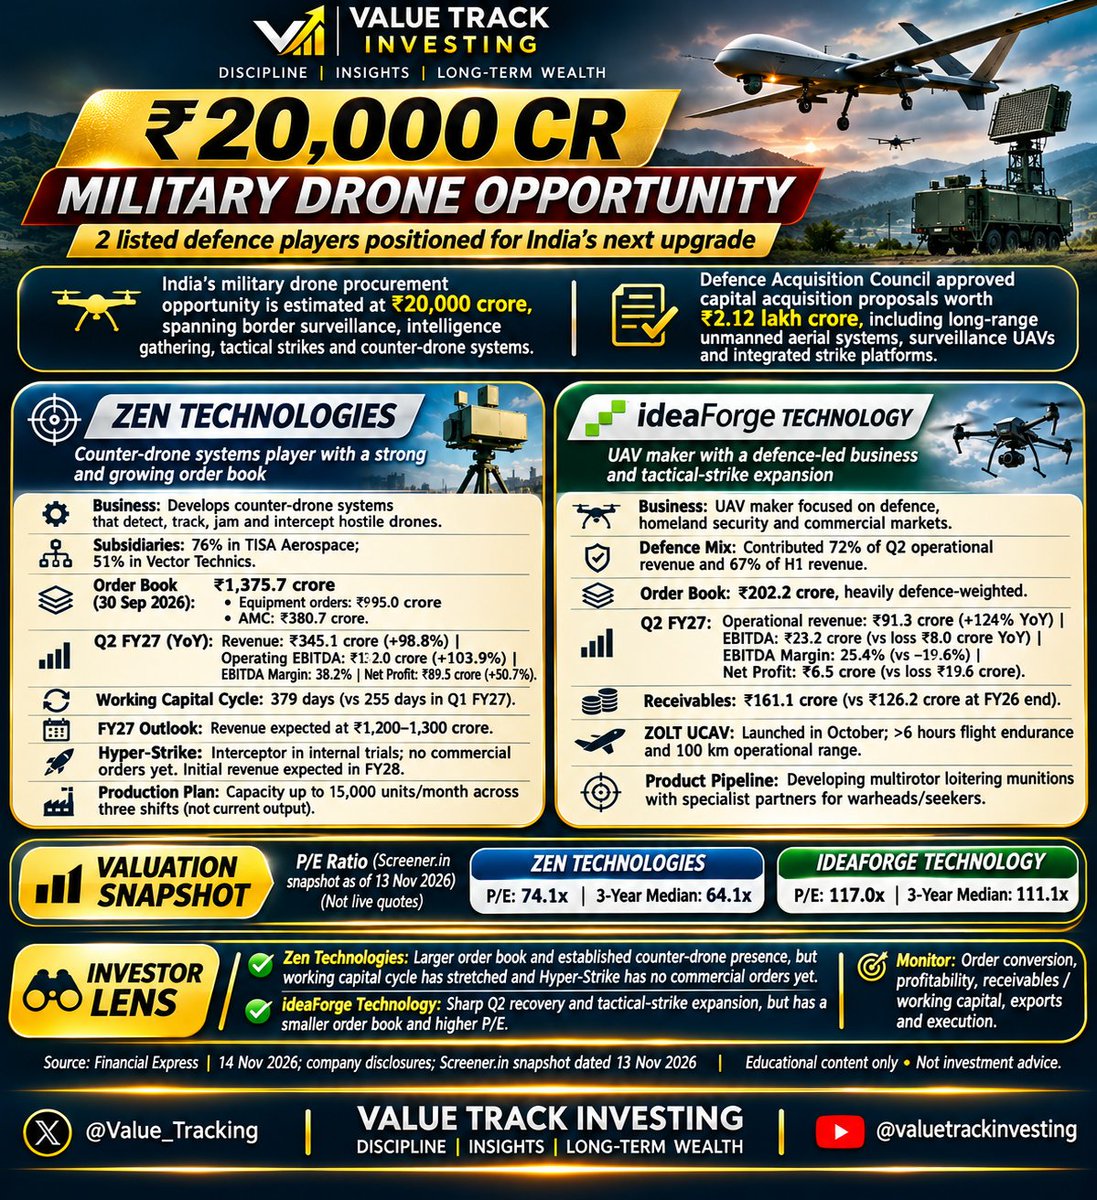
🚁 ₹20,000 CRORE MILITARY DRONE OPPORTUNITY — TWO DEFENCE STOCKS TO WATCH
India’s next military upgrade could create significant opportunities for domestic defence technology companies.
🔹 Zen Technologies
- Strong ₹1,375.7 Cr order book.
- Counter-drone systems and defence solutions.
- Hyper-Strike interceptor under development.
- Key monitorable: Order conversion and working capital.
🔹 ideaForge Technology
- Defence-focused UAV manufacturer.
- Q2 operational revenue grew 124% YoY.
- Expanding into tactical-strike drone platforms.
- Key monitorable: Order-book growth and profitability.
📊 Investor takeaway
Both companies are positioned in India's growing drone ecosystem, but valuations and execution risks remain important. Zen has a larger order book, while ideaForge is showing a recovery in operations.
A promising sector does not automatically mean an attractive stock valuation. Track execution before making investment decisions.
▶️ YouTube: https://t.co/YAV6QVfvST
Educational content only. Not investment advice.
#DefenceStocks #DroneTechnology #ZenTechnologies #ideaForge #IndianDefence #DefenceSector #MakeInIndia #MilitaryDrones #DefenceManufacturing #StockMarketIndia #Q2FY27 #ValueTrackInvesting
🚘 AUTO STOCK SHOWDOWN: Growth vs Valuation!
Which automobile stock offers the better opportunity after Q2 FY27?
📊 Key comparisons:
- M&M: Strong profit growth with the lowest P/E in this comparison.
- Maruti Suzuki: Strong sales momentum and a large order backlog.
- Hyundai Motor India: Growth continues, but margin pressure remains.
- Tata Motors PV: Consolidated net loss narrowed 14.4% YoY, but the business remains loss-making.
📈 P/E snapshot (13 Nov 2026):
- M&M: 20.58x
- Maruti: 30.19x
- Hyundai: 36.82x
- Tata Motors PV: 22.28x
⚠️ Tata's P/E needs careful interpretation because it remained loss-making. Valuation methodologies may also differ across providers.
🎯 Investor takeaway: Growth, profitability, margins and valuation must be considered together. The cheapest-looking stock is not automatically the best investment.
Which company has the strongest long-term potential?
▶️ YouTube: https://t.co/YAV6QVfvST
#AutoStocks #MarutiSuzuki #Mahindra #HyundaiMotorIndia #TataMotorsPV #Q2FY27 #IndianStockMarket #StockAnalysis #ValueInvesting #ValueTrackInvesting
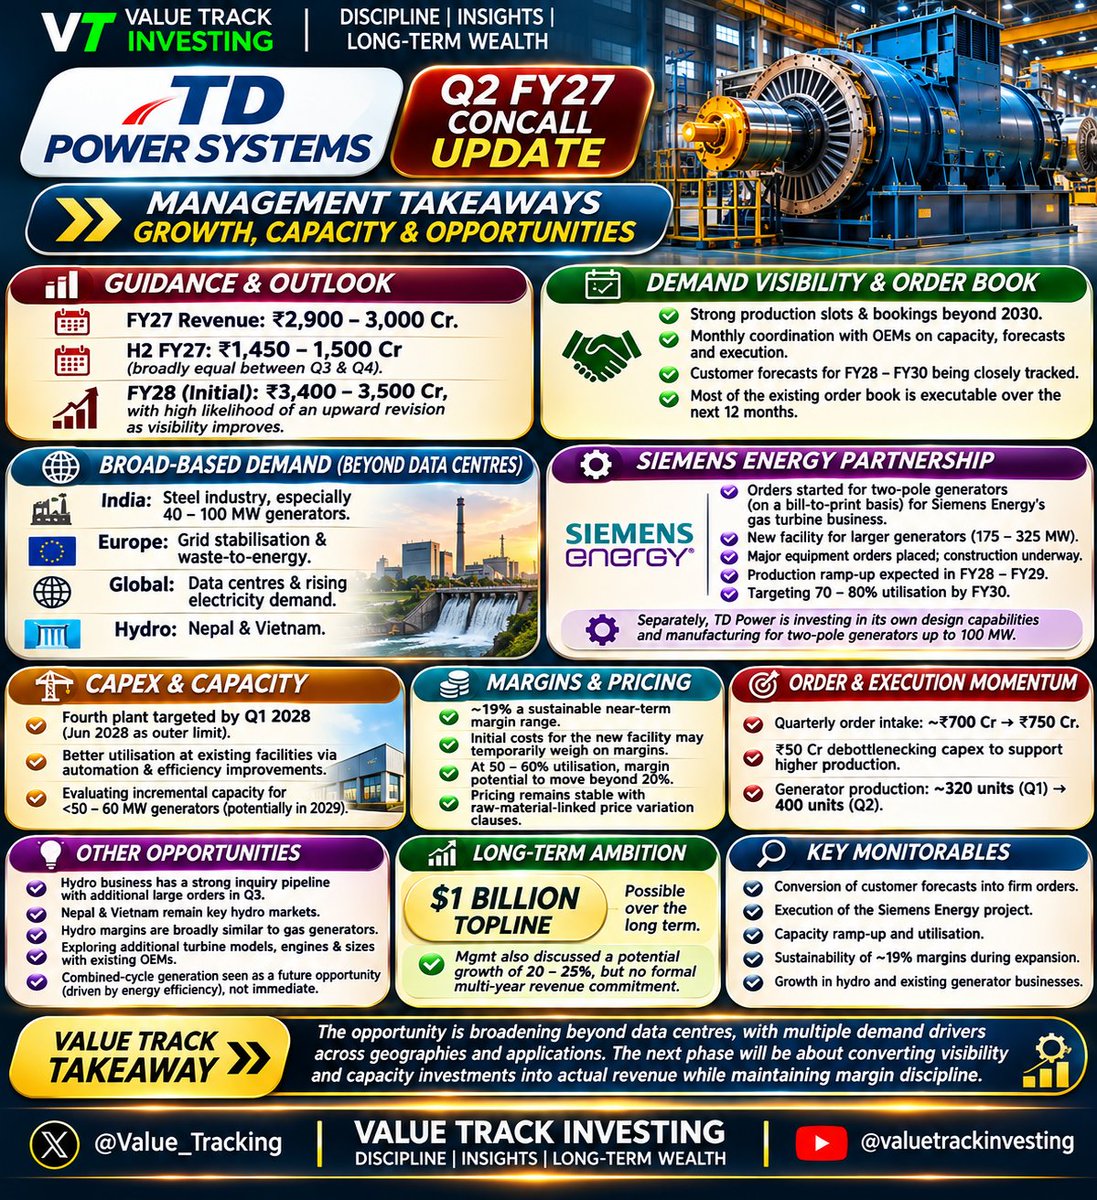
⚡ TD POWER SYSTEMS: BEYOND THE DATA CENTRE STORY!
The Q2 FY27 concall points to expanding demand across multiple industries, strong order visibility and a significant capacity expansion cycle.
📊 Management Guidance
• FY27 revenue: ₹2,900–3,000 Cr.
• FY28 initial guidance: ₹3,400–3,500 Cr.
• H2 FY27 revenue expected at ₹1,450–1,500 Cr.
• Management sees potential for an upward FY28 revision as visibility improves.
🌍 Demand Visibility
• Production slots and bookings extending beyond 2030.
• Strong demand from Indian steel, European grid stabilisation and waste-to-energy.
• Global data centre demand and rising electricity requirements.
• Hydro opportunities in Nepal and Vietnam.
🤝 Siemens Energy Partnership
• Manufacturing two-pole generators for Siemens Energy.
• New facility designed for 175–325 MW generators.
• Production ramp-up expected in FY28–FY29.
• Targeting 70–80% utilisation by FY30.
🏭 Capacity & Margins
• Fourth plant targeted by Q1 2028.
• ~19% sustainable near-term margin outlook.
• Potential to exceed 20% margins as new facility utilisation improves.
• Quarterly order intake increased from ~₹700 Cr to ~₹750 Cr.
💡 Long-Term Opportunity
Management believes a $1 billion revenue opportunity is possible, without committing to a timeline.
⚠️ Key Monitorables
• Customer forecasts converting into firm orders.
• Siemens project execution and capacity utilisation.
• Margin sustainability during expansion.
• Hydro business growth and new OEM opportunities.
🎯 VALUE TRACK TAKEAWAY
The growth opportunity is broadening beyond data centres. TD Power's next phase depends on converting demand visibility and capacity investments into revenue while protecting margins.
▶️ Watch more analysis on YouTube:
https://t.co/YAV6QVfvST
Disclaimer: For educational purposes only. Not investment advice.
#TDPowerSystems #TDPS #Q2FY27 #ConcallHighlights #PowerGeneration #DataCentres #SiemensEnergy #RenewableEnergy #ElectricalEngineering #ValueTrackInvesting
⚙️ RACL GEARTECH: MORE THAN JUST Q2 NUMBERS!
RACL is gradually transforming from a two-wheeler gear supplier into a global precision engineering partner.
📊 Q2 FY27 Highlights
• Revenue: ₹139 Cr | +11% YoY
• EBITDA: ₹36.7 Cr | +16% YoY
• PAT: ₹17.6 Cr | +46% YoY
• Operating margin: ~26%
🌍 What Makes the Story Interesting?
• Global OEM relationships: BMW, ZF, KTM and Royal Enfield.
• Europe contributes 51% of Q2 sales; North America 15%.
• Expanding into passenger cars, EVs and premium components.
• BMW programmes and ZF steering products offer future ramp-up potential.
⚠️ Key Risks to Monitor
• H1 operating cash flow: ₹14.4 Cr against PAT of ₹26.5 Cr.
• Debt increased approximately ₹37 Cr in six months.
• New programme selection must translate into regular volumes.
• Valuation around 33x P/E needs earnings growth to justify it.
🎯 VALUE TRACK VIEW
RACL's customer relationships, product complexity and global reach are encouraging. However, cash conversion, debt discipline and execution will determine whether this opportunity translates into sustained shareholder value.
▶️ Watch more analysis on YouTube:
https://t.co/YAV6QVfvST
Disclaimer: For educational purposes only. Not investment advice.
#RACLGeartech #RACL #Q2FY27 #AutoAncillary #PrecisionEngineering #AutomotiveComponents #EVComponents #MakeInIndia #IndianStockMarket #ValueTrackInvesting
🏍️ EICHER MOTORS Q2 FY27 CONCALL: WHAT MANAGEMENT IS SAYING
Royal Enfield's demand momentum remains strong, while Eicher Motors is preparing for its next phase of capacity-led growth.
🔍 Key Management Takeaways
• Strong bookings momentum with no signs of rural demand slowdown.
• UP, West Bengal and Bihar continue to show robust demand.
• Himalayan 440 received an exceptional response.
• Flying Flea C6 expands Royal Enfield's electric mobility ambitions.
• Capacity expansion targets 2 million units by Q2 FY28.
• New Andhra Pradesh plant to add 4.5 lakh units of annual capacity.
• VECV continues to see healthy commercial vehicle demand.
• Management prioritises absolute profit growth over margin guidance.
• Focus remains on the 250–750cc segment.
🎯 Value Track View
Strong demand, product innovation and aggressive capacity expansion support the long-term growth outlook. Monitor cost inflation, margin protection and execution of expansion plans.
What is your view on Royal Enfield's long-term growth opportunity?
▶️ YouTube: https://t.co/YAV6QVfvST
#EicherMotors #RoyalEnfield #Q2FY27 #ConcallHighlights #ManagementCommentary #AutomobileSector #TwoWheelers #CommercialVehicles #ElectricMobility #IndianStockMarket #ValueTrackInvesting
🇮🇳🇺🇸 INDIA–US TRADE DEAL: A POTENTIAL TARIFF ADVANTAGE FOR INDIA
The US has reportedly assured India of more favourable tariff treatment compared with competing economies.
📌 Why this matters:
- Could improve India's competitiveness in export markets.
- Potential advantage for textiles, apparel, leather, footwear and engineering goods.
- May strengthen India's position against competing suppliers such as Vietnam, Bangladesh and Cambodia.
🔍 What investors should watch:
- Final tariff rates and product coverage.
- Progress of the Section 301 investigation.
- Trade agreement negotiations and implementation timeline.
- Impact on export-oriented companies and order flows.
⚠️ Important: An assurance is not a signed trade agreement. Final terms and implementation details remain subject to negotiations.
📊 Value Track View: A potentially positive development for Indian exporters, but the actual benefit will depend on the final tariff structure.
▶️ YouTube: https://t.co/YAV6QVfvST
#IndiaUSTradeDeal #IndiaUSRelations #USIndiaTrade #IndianExports #TariffNews #TradeAgreement #TextileStocks #EngineeringExports #ExportStocks #IndianEconomy #StockMarketIndia #ValueTrackInvesting