Retirement planning for people within five years of retirement, or already retired, with $1M or more set aside. One CPA-led team designs every part of the plan.
"What's the tax rate when I sell my business?"
There isn't one.
The price gets chopped into pieces, and each piece has its own tax rule.
And here's the fun part. The split that's best for you is usually worst for the buyer. 🙃
Negotiate it.
Spent 30 years building your savings?
Then a lawsuit from one bad car accident could go after it.
Your car insurance only covers so much. An umbrella policy can cover what's above that, up to its own limit, and it usually costs less than you'd think. ☂️
"This fund was up big last year. I should get in."
You're not getting in. You're getting in late.
The gains already happened. To someone else.
Pick investments for what they'll do for you, not what they did for somebody else.
A lot of people feel a little guilty planning around taxes. Like it's cheating.
It's not. The Supreme Court said so in 1935. Lowering your taxes by legal means is your right. ⚖️
Skipping the planning doesn't make you more honest. It just means you pay more.
Retired this year? Your income may be lower now than it will be for years.
That can make moving IRA money into a Roth cost less in tax. It can also raise your Medicare premiums later, so run the whole picture first.
This year's window closes December 31.
Pop quiz: which is rarer in the stock market, a year with a dip or a year without one?
The year without one. 📉
So when it drops this year, don't panic. That's not the market breaking.
That's the market doing what markets do. 🤷
Two people. Same job, same pay, same work history.
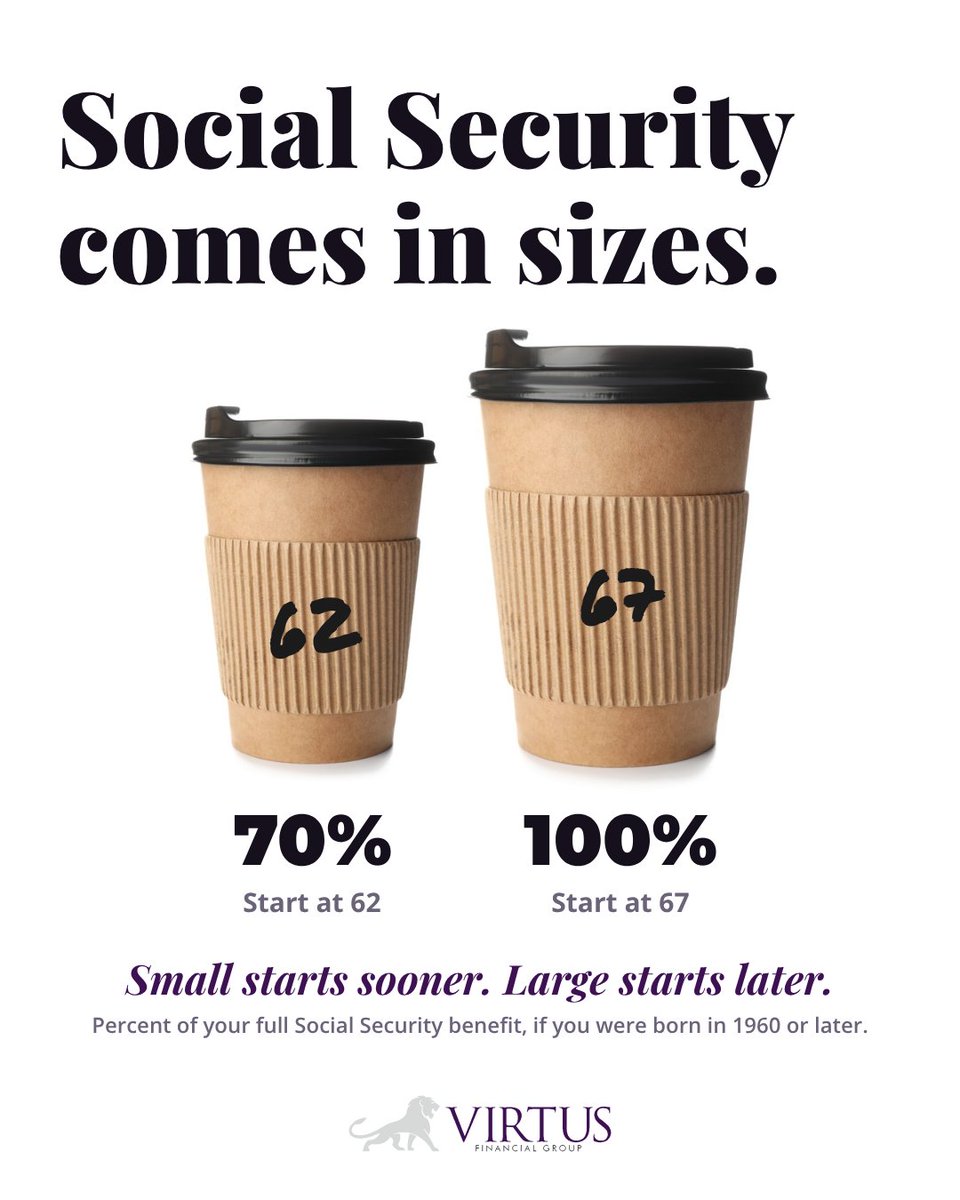
One starts Social Security at 62. The other waits until 67.
If they were born in 1960 or later, the first one gets 70% of the check. The second gets 100%.
Every month. For the rest of their lives.
For 40 years, tax came out of your paycheck without asking.
Social Security doesn't do that. It waits for you to ask.
Don't ask, and you might find out in April. 😬
Want to free up money for retirement without changing much?
Keep your car longer.
The steepest drop in a car's value comes in the first few years. Buy new, trade early, and you keep paying for that drop.
Drive it until it's paid off. Then keep driving it.
"I've put in the years, so my federal pension pays the higher rate."
Age matters too. Under FERS, the 1.1% rate generally needs age 62 and at least 20 years of service at once. Short on either, it's generally 1%.
Check both before picking a date.
"We'll do the Grand Canyon hiking trip when the market calms down".
Do the hard trips while you can.
The cruise will still be there when your knees aren't. 🦵
When did you last ask your parents what they want the next ten years of retirement to look like?
Not their balances. Not their accounts. Their plans.
Where they want to live. Who they want to spend time with. What they keep saying they’ll “get around to.”
Once you know that, the money conversation starts itself: what it will cost, what’s there to cover it, and how much they can enjoy right now instead of saving it for someday.
Start with the life. The numbers will follow.
Retiring? Some people worry about losing the title.
But how often did you use it? Mostly when you met someone new.
The calendar and the coworkers? Those filled every single day.
How (and with whom) are you spending your time when you're retired?
Sold your business? Congrats, you're the payroll department now. 🫡
Tax usually isn't withheld from a sale. So you may need to send in estimated payments yourself, on the sale and on what the money earns.
If you do, the last one for this year is usually due January 15. On your calendar yet?
Part of planning for retirement is planning to enjoy it. 🏖️
You spent decades planning the saving. Give the fun the same attention. Decide what you want to do, when, and what it costs. Then put it in the plan.
Otherwise the big trip waits for someday. And someday is famous for not showing up.
"Social Security goes up in January. A little extra to play with."
Not really. Prices already went up. The bigger check just catches you up.
Bigger check. Same cart of food.
It's not a raise. Don't spend it like one.
Got an IRA you haven't paid tax on yet? Somebody probably will. You, or whoever gets it when you're gone.
You know your tax rate. It's on last year's return.
You don't know theirs. It depends on what they make the year they inherit it.
So which one works best for your family?
Meet Walt. Walt retired from his federal job in June, at 63. That fall, the news said pensions were going up.
But Walt's first increase was cut down to match the months he'd been retired.
After that, he gets the full one. Retire halfway through the year, and expect about half the first increase.
One catch: under FERS, these increases generally don't start until 62, with some exceptions.