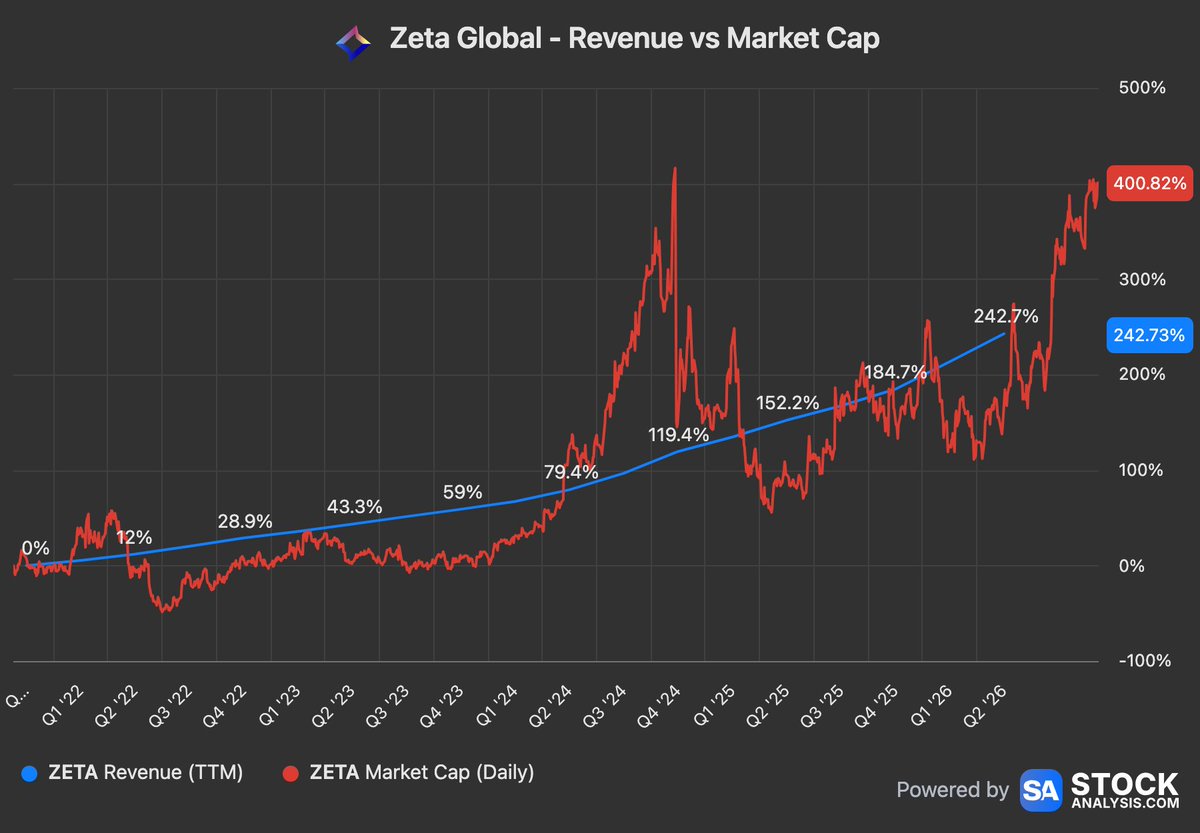
$ZETA’s 36% revenue growth is promising, but near profitability is the real test. I’d watch whether it can turn growth into sustainable earnings. @stock_analysisx $ZETA
2/6 Zeta Global is up 73% in a year and the market is finally paying attention.
Revenue grew 36% to $1.57 billion, and it is now within $2 million of profitability.
The next quarter could be its first profitable one.
$ZETA
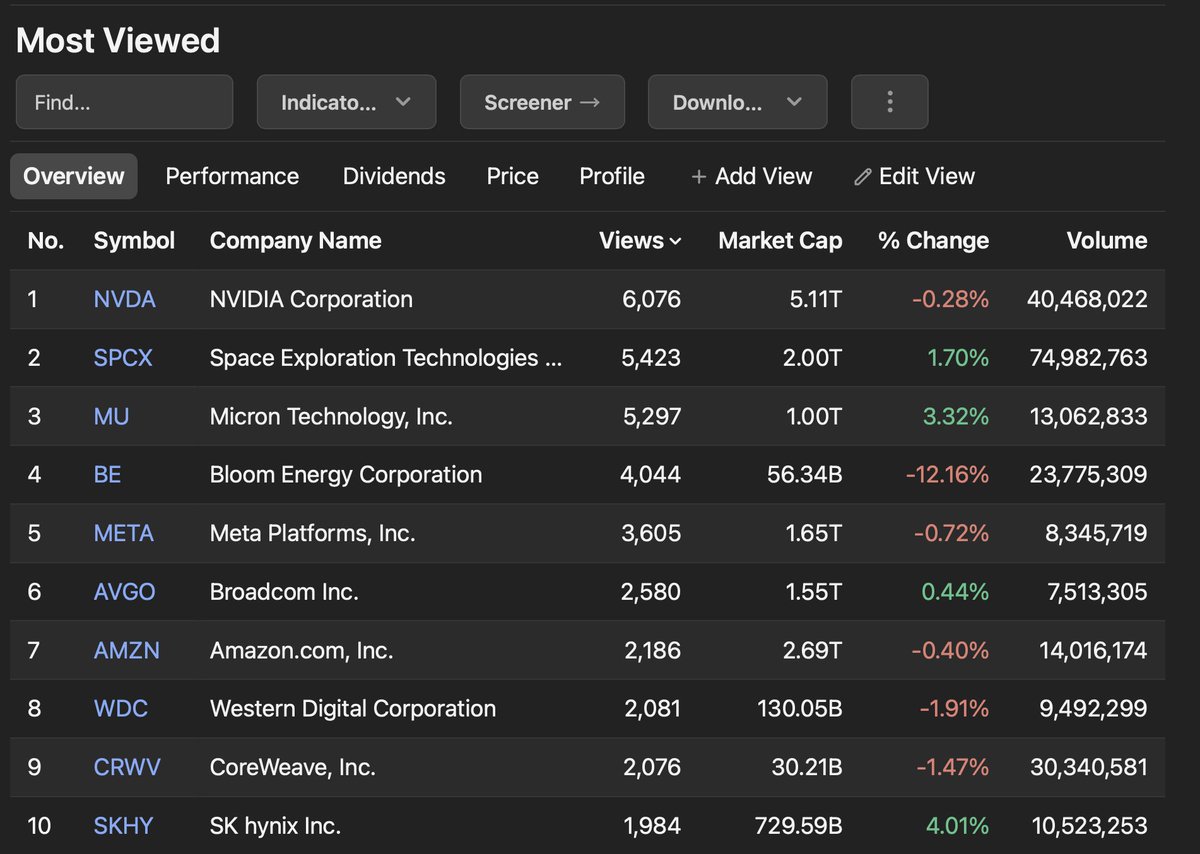
NVDA leads views, but $MU and $SKHY are gaining attention too. I’d watch whether memory demand can sustain this momentum. @stock_analysisx $NVDA $MU $SKHY
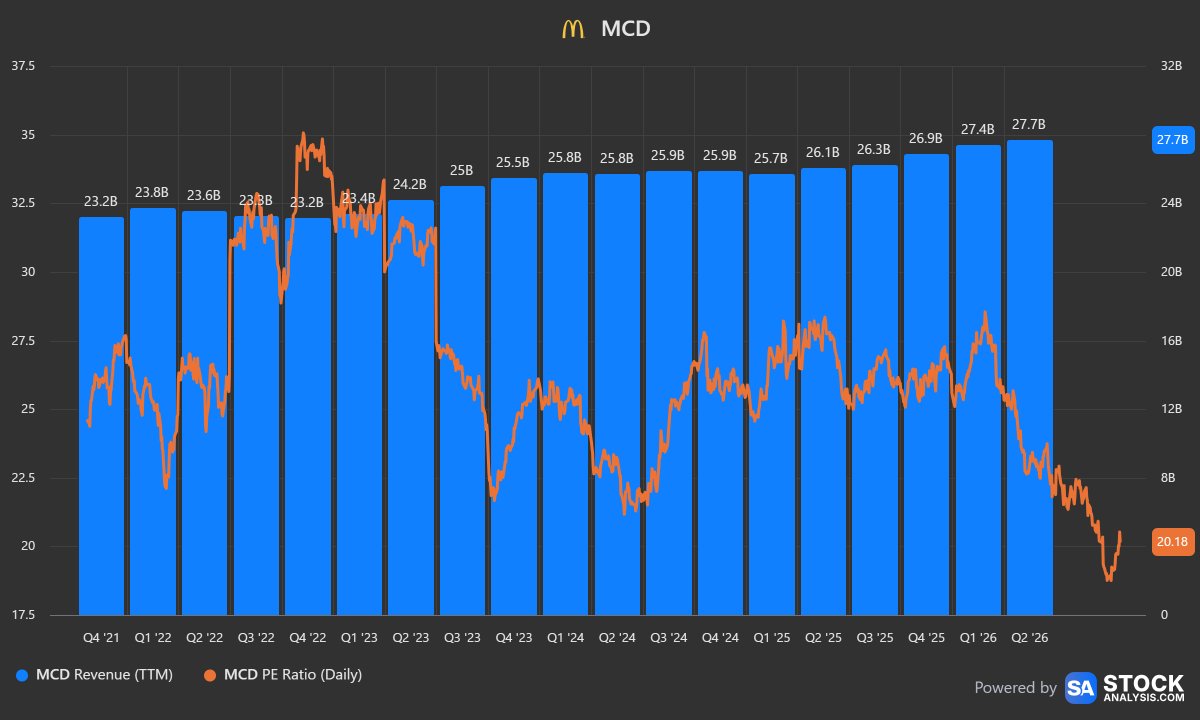
$MCD revenue has steadily climbed to $27.7B, but its PE ratio has dropped to around 20.18. I’d want to see how earnings growth compares before deciding if the stock is becoming more attractive. @stock_analysisx $MCD
One thing I noticed in $SNA: revenue has barely moved from around $4.7B over several quarters, yet its PE ratio surged in 2026 before cooling off. For me, the key question is whether earnings can deliver enough growth to support the valuation. @stock_analysisx $SNA
Revenue is accelerating at $BE: TTM revenue has climbed from $1.6B in Q2 2025 to $3.83B in Q3 2026. That’s a meaningful jump, but the P/E ratio has swung wildly. I’d be careful about judging the stock on growth alone. @stock_analysisx $BE
What I find interesting about $CRWV is that revenue keeps climbing, reaching $7.6B in Q2 2026, while the P/TBV ratio has dropped sharply. The business is growing, but I’d still want to understand the balance-sheet risks behind the valuation. @stock_analysisx $CRWV
Nearly $4.9T in TTM revenue—that’s a big jump for $TSM from its $1.6T level in 2021. The business has scaled considerably, even with valuation swings along the way. @stock_analysisx $TSM
Looking at $IREN, revenue has grown sharply, reaching $707M, but the valuation has been extremely volatile. The business is scaling fast, yet I’d want to see more stability in earnings before getting too bullish. @stock_analysisx $IREN
Looking at $NBIS, revenue has recovered to $1.36B after falling sharply from its 2023 highs. That turnaround is interesting, but the P/E ratio is extremely volatile. I’d want to see more consistent growth before getting too bullish. @stock_analysisx $NBIS
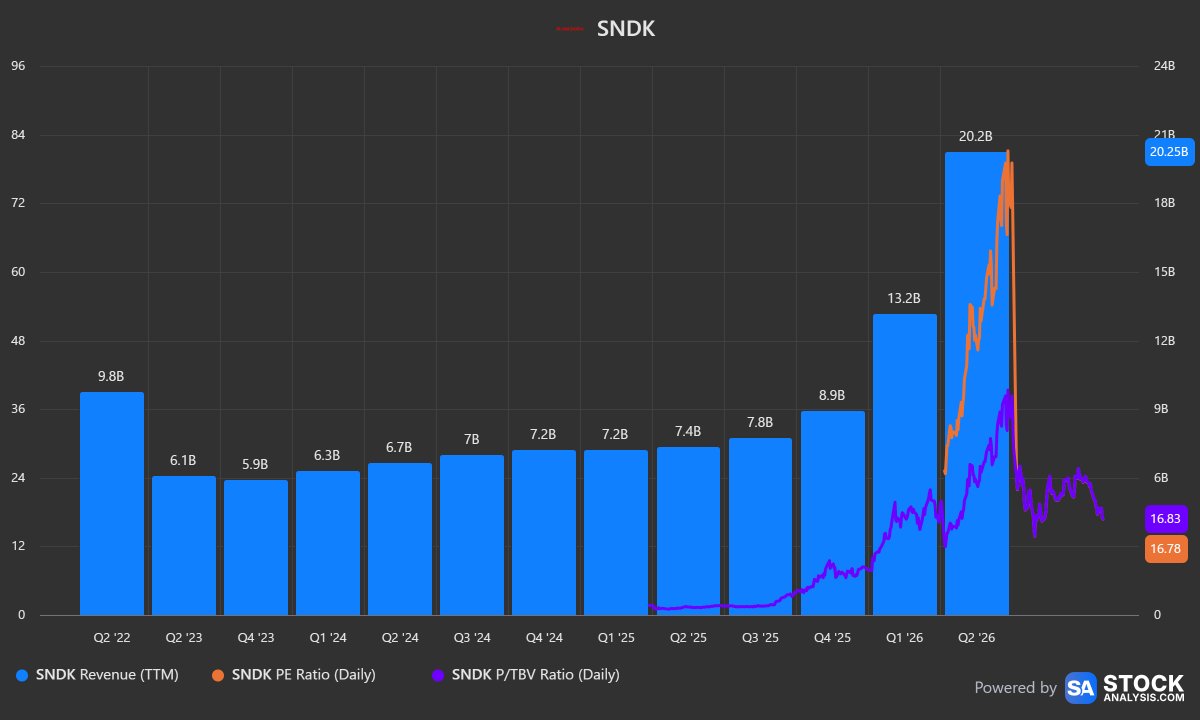
What stands out to me in $SNDK is the jump in revenue from $8.9B to $13.2B and then $20.2B across recent quarters. But the valuation ratios have pulled back sharply from their peaks. I’d watch whether growth can sustain this level. @stock_analysisx $SNDK
Looking at $AMD, revenue has climbed from $16.4B to $41.3B, while the P/E ratio is far below its 2023 peak. To me, the growth is encouraging, but I’d still watch whether earnings can justify the current valuation. @stock_analysisx $AMD
Looking at $AMZN, revenue has climbed steadily to $775.7B, but the P/E ratio has fallen to around 20. To me, that makes the stock worth watching, though I’d want to see how earnings growth supports the valuation. @stock_analysisx $AMZN
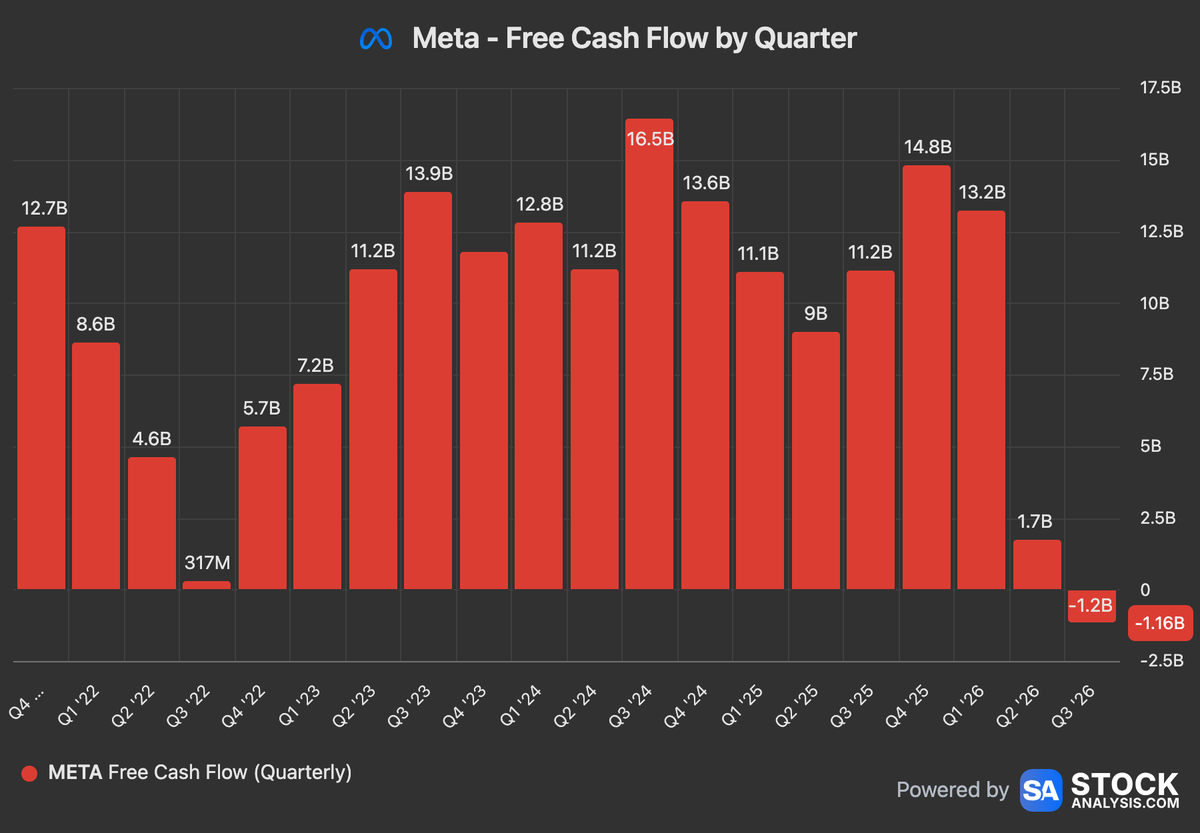
META’s cash flow trend caught my attention. Heavy AI spending may be pressuring near-term cash generation, so I’d watch whether returns justify the investment. @stock_analysisx $META
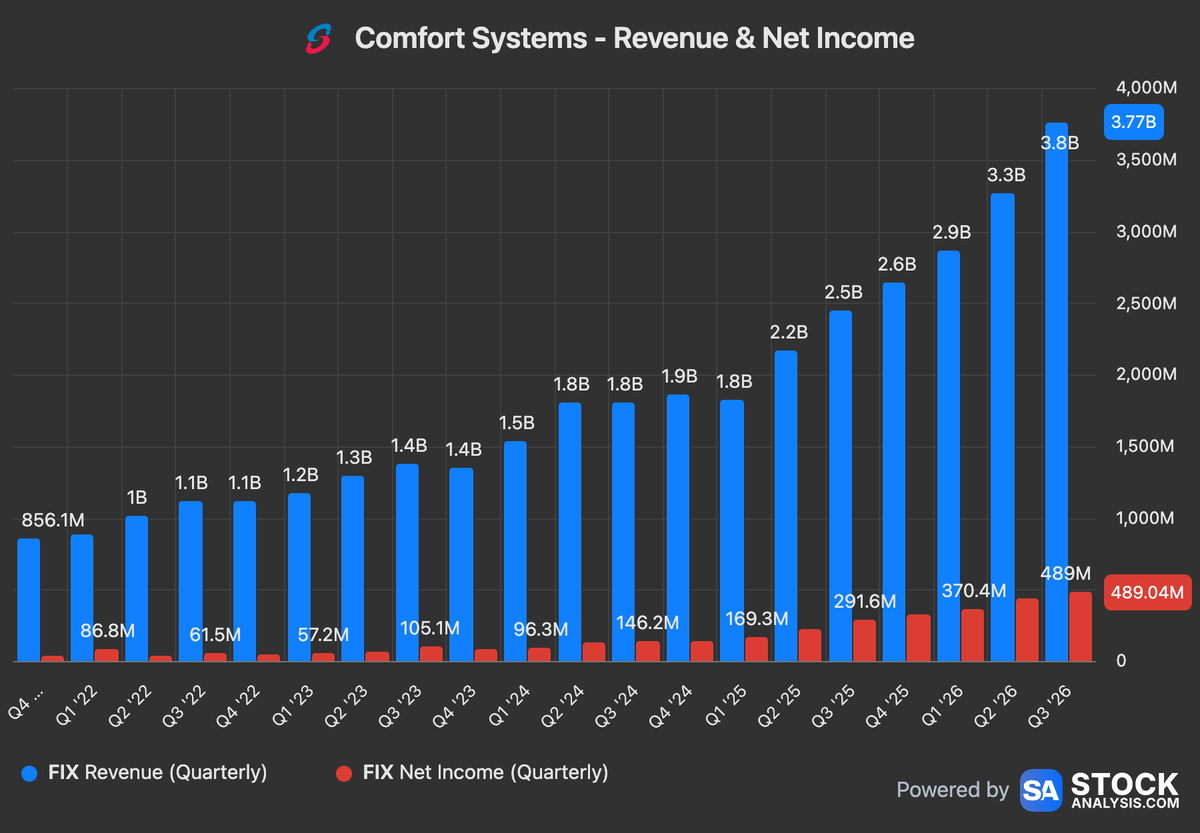
My take on $FIX: AI growth isn’t just about chips. Data centers need cooling too, and rising revenue and profits make this trend worth watching. @stock_analysisx $FIX
One of the best AI businesses this year makes air conditioners.
Comfort Systems grew revenue 54% last quarter and profit 95% over the past year.
It keeps data centers from overheating. AKA selling shovels to the gold miners...
$FIX
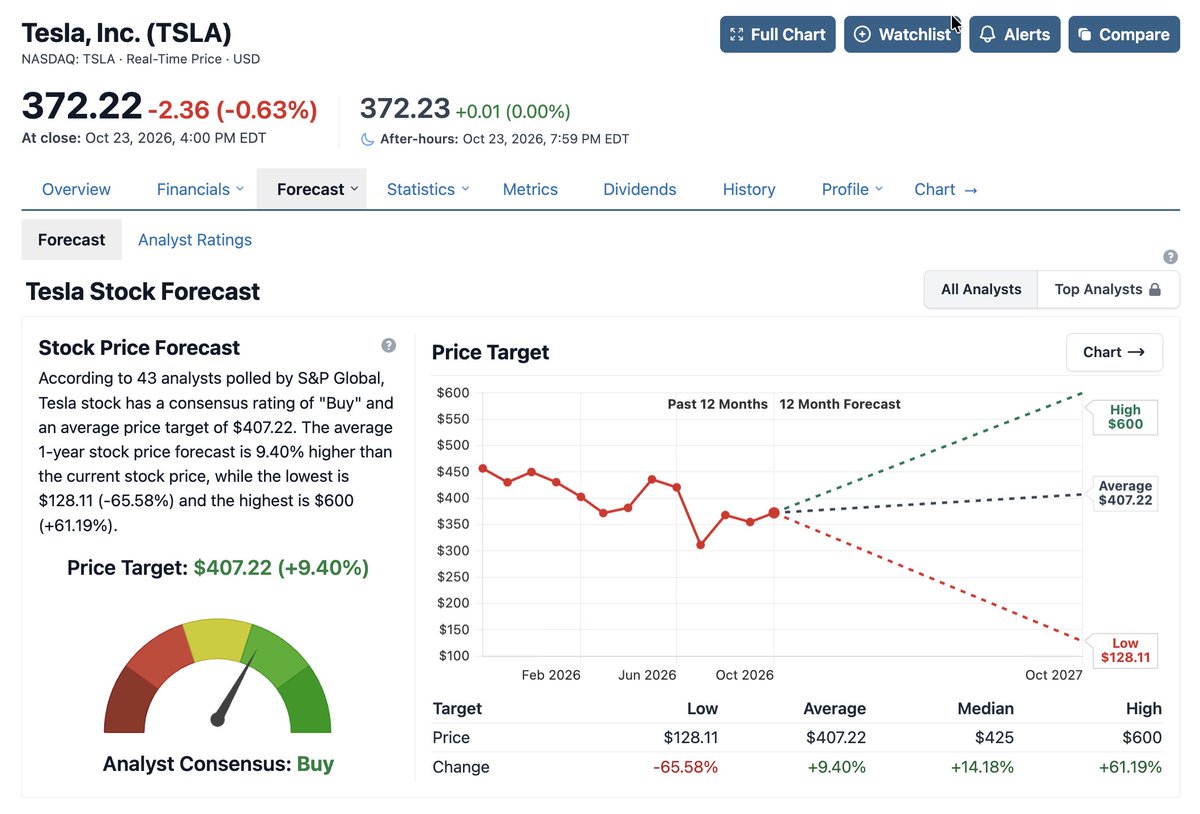
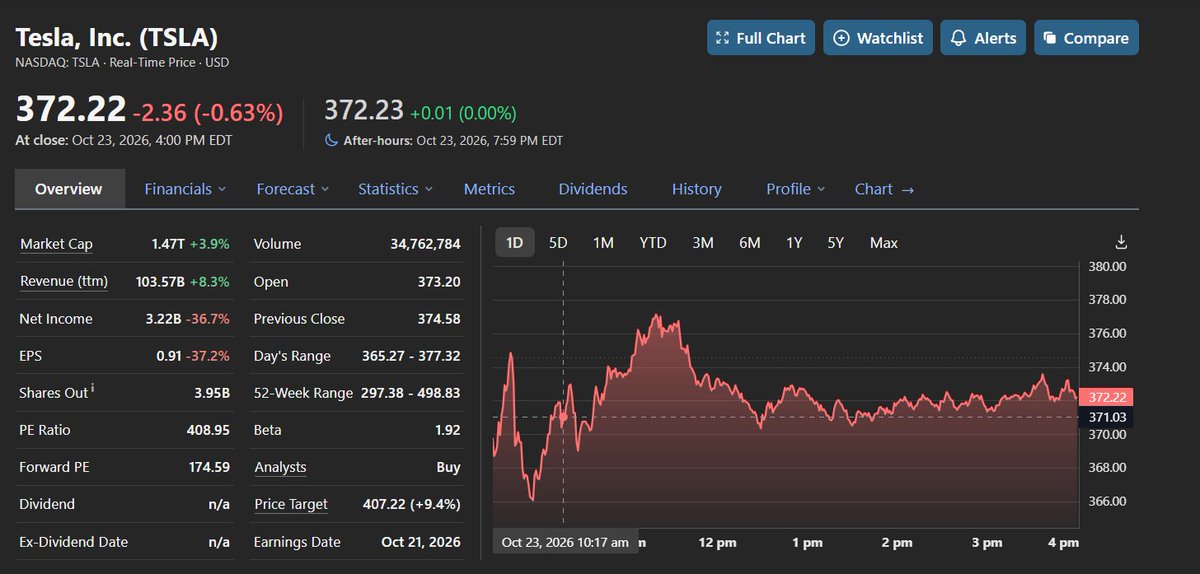
$TSLA has a Buy consensus, but the average analyst target is only $407.22 vs. $372.22 now. With forecasts ranging from $128 to $600, there’s clearly a wide gap in expectations. I’d stay cautious. @stock_analysisx $TSLA
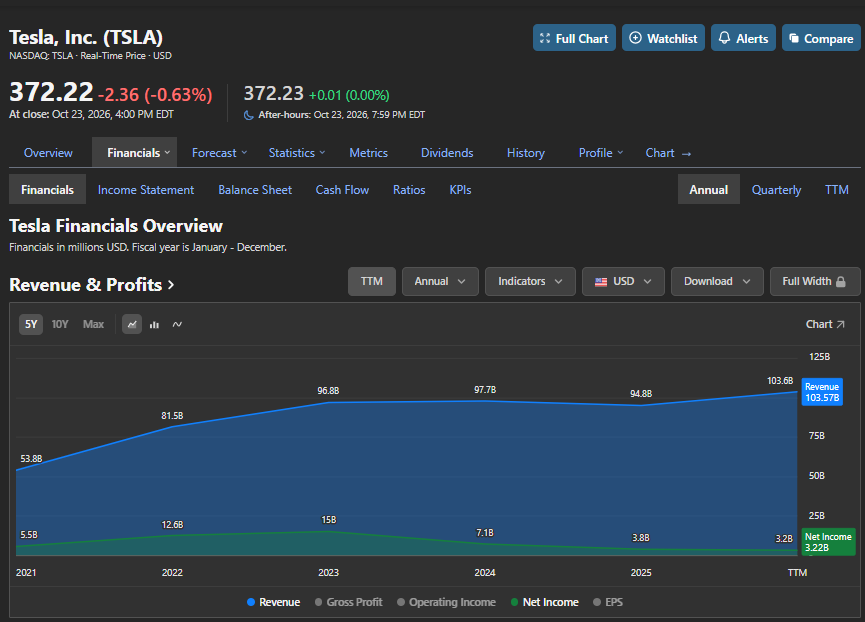
$TSLA revenue is still growing, but profits tell a different story. TTM revenue reached $103.6B, while net income fell to $3.2B from $12.6B in 2022. For me, the key question is when earnings will recover. @stock_analysisx $TSLA
$TSLA closed at $372.22, but what stands out to me is the 36.7% drop in TTM net income. With the stock still trading at a high valuation, I’d want to see earnings improve before getting too bullish. @stock_analysisx $TSLA
$MU’s FY26 revenue jumped to $133.2B from $37.4B in FY25. The growth is impressive, but I’m more interested in whether these margins can hold. @stock_analysisx $MU
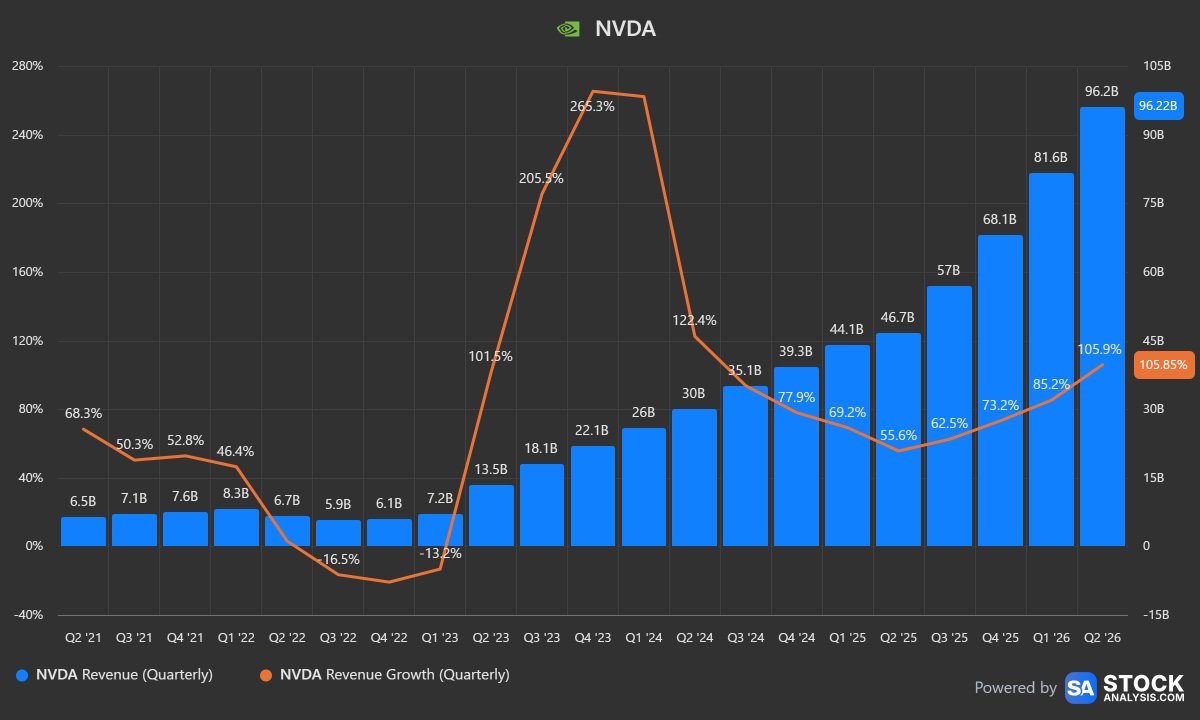
What stands out to me in $NVDA is that growth is accelerating on an already much larger revenue base. Quarterly revenue climbed from $35.1B in Q3 2024 to $96.2B in Q2 2026,while YoY growth rebounded from 55.6% to 105.9%. I’d watch how long this pace holds. @stock_analysisx $NVDA
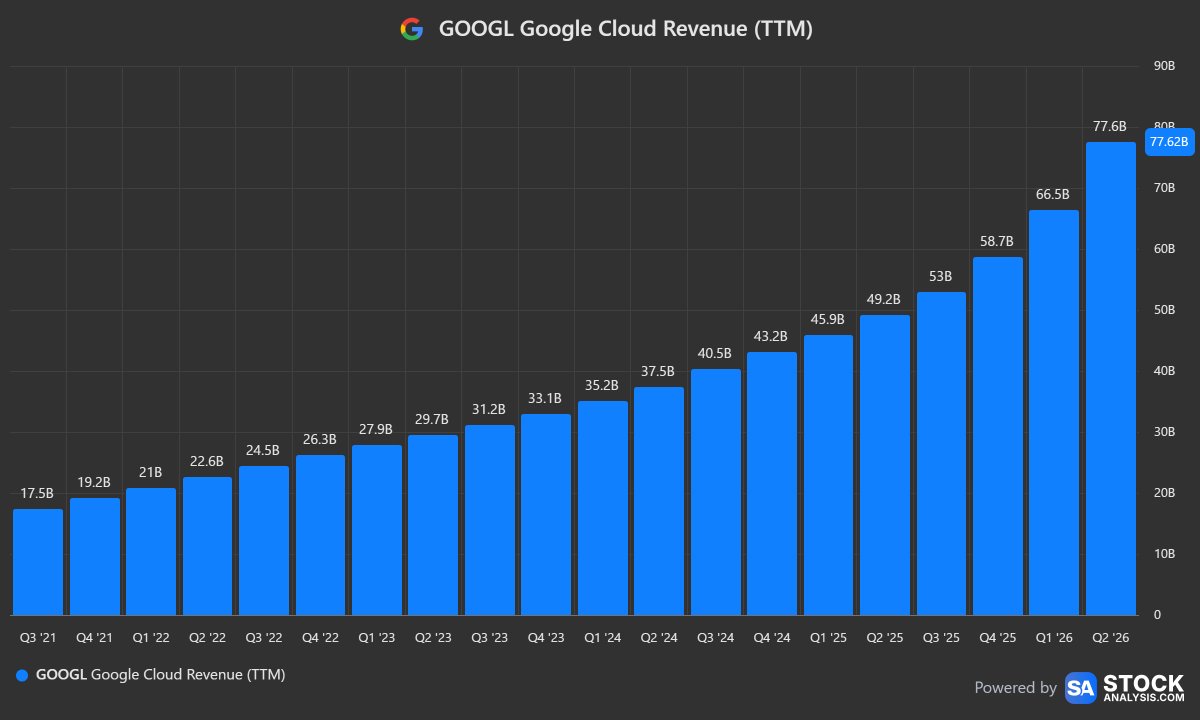
What stands out to me in $GOOGL is how Google Cloud’s growth has accelerated. TTM revenue rose from $40.5B in Q3 2024 to $77.6B in Q2 2026, nearly doubling in under two years. I’d now watch whether this pace translates into stronger profitability. @stock_analysisx $GOOGL