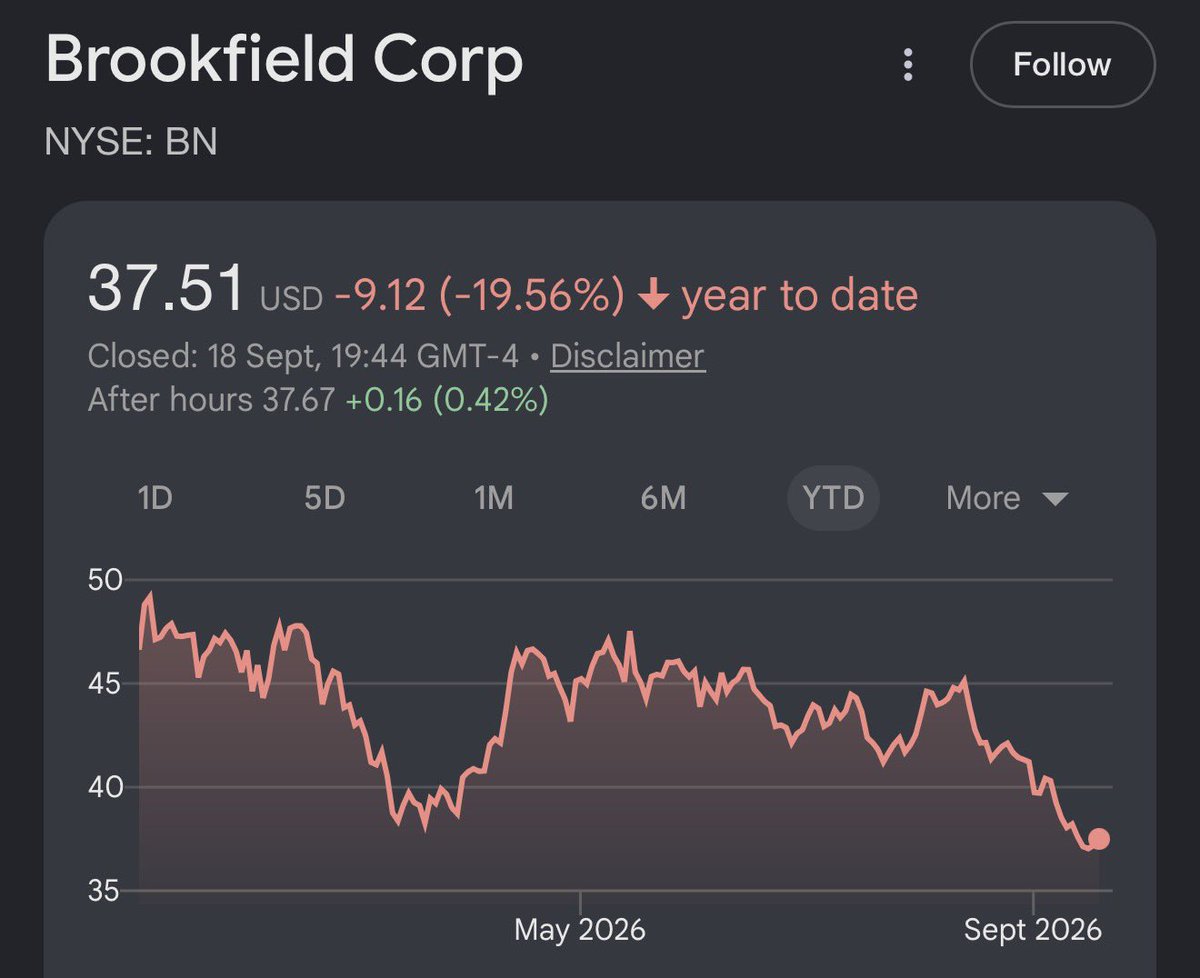
Brookfield $BN guides 24% annual distributable earnings growth for the next 5 years. That gets them to $6.63 per share.
At 15x, that's just under $100. Roughly 3x from here.
This is a BIG deal to absorb.
Q2 adjusted EPS rose 18%, but reported EPS fell 38% as acquisition-related costs hit.
I’m watching integration, cash flow and debt reduction. The enlarged business needs to produce more cash per share.
I think ITT’s most interesting customers are the ones who bought equipment YEARS ago.
Here’s how a pump sale can turn into a much longer relationship.
Full research 🧵
ITT bought SPX FLOW for $4.775B in March.
That adds processing equipment used in food, chemicals and energy, plus a large installed base.
More equipment to maintain is the attraction. Now ITT has to make that purchase price worthwhile.
I’m interested in HLI building a bigger business one good team at a time.
But the payoff has to show up in earnings PER SHARE. Hiring more bankers and paying bigger salaries only works if the fees eventually follow.
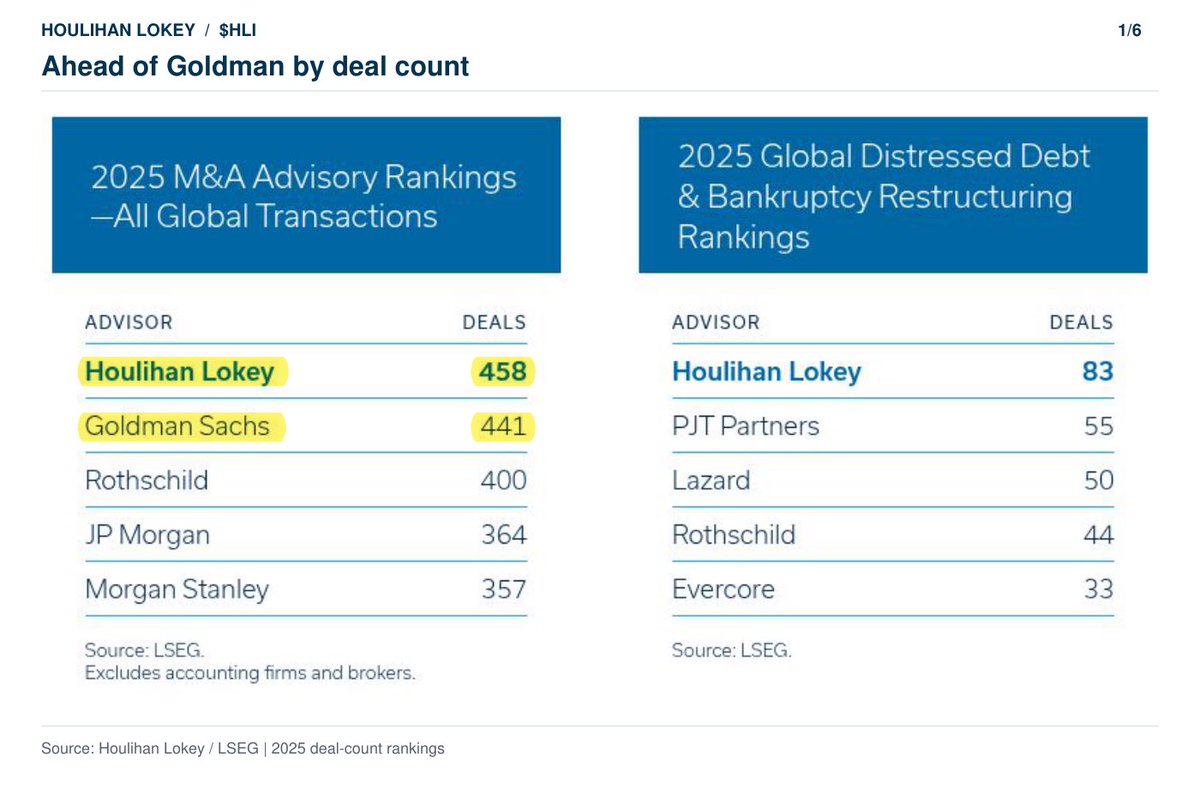
In 2025, $HLI ranked AHEAD of Goldman Sachs for M&A deal count.
The more interesting part is that it can also earn fees when companies go bankrupt.
Full research 🧵
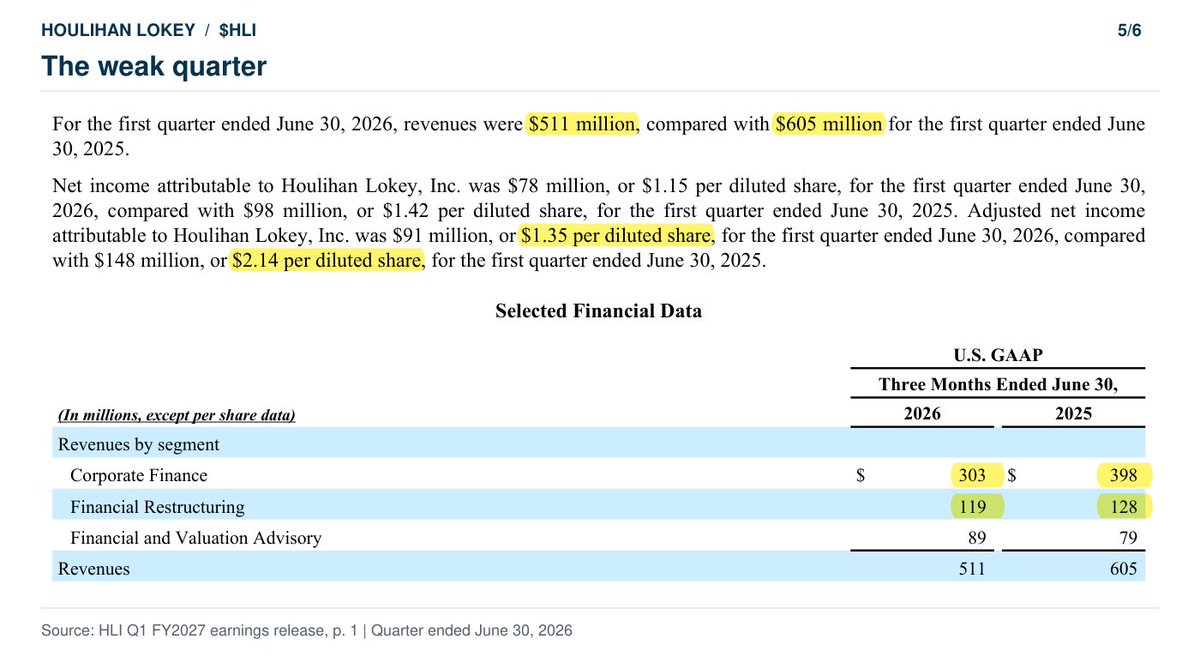
And the latest quarter was ugly…
June 2026 revenue dropped 16% to 511M. Adjusted EPS fell to $1.35 from $2.14.
Corporate finance and restructuring both declined. Restructuring won’t rescue every weak quarter.
I would build these positions gradually.
Then keep checking that the reasons I bought are still true.
The plan is to hold for decades.
Companies that keep customers, generate cash and invest it well make that possible.
IEX | IDEX | $224
Precision pumps and fluidics for scientific equipment and industrial processes.
Q2 organic orders grew 28%.
Management raised its annual outlook.
Roughly 24.5x forward earnings.
Highest multiple on the list.
I would start smaller here.