Market intelligence for discerning minds. Deep stock research, price action, and timely insights-shared selectively with trusted few. MAIN PAGE: @warrenpies
Historically, during soft landings, the S&P 500 rips in 6 months leading into a first Fed cut.
Would put the market at 5,200 by May...
First time speaking w/ the great @ScottWapnerCNBC was a blast!
FED
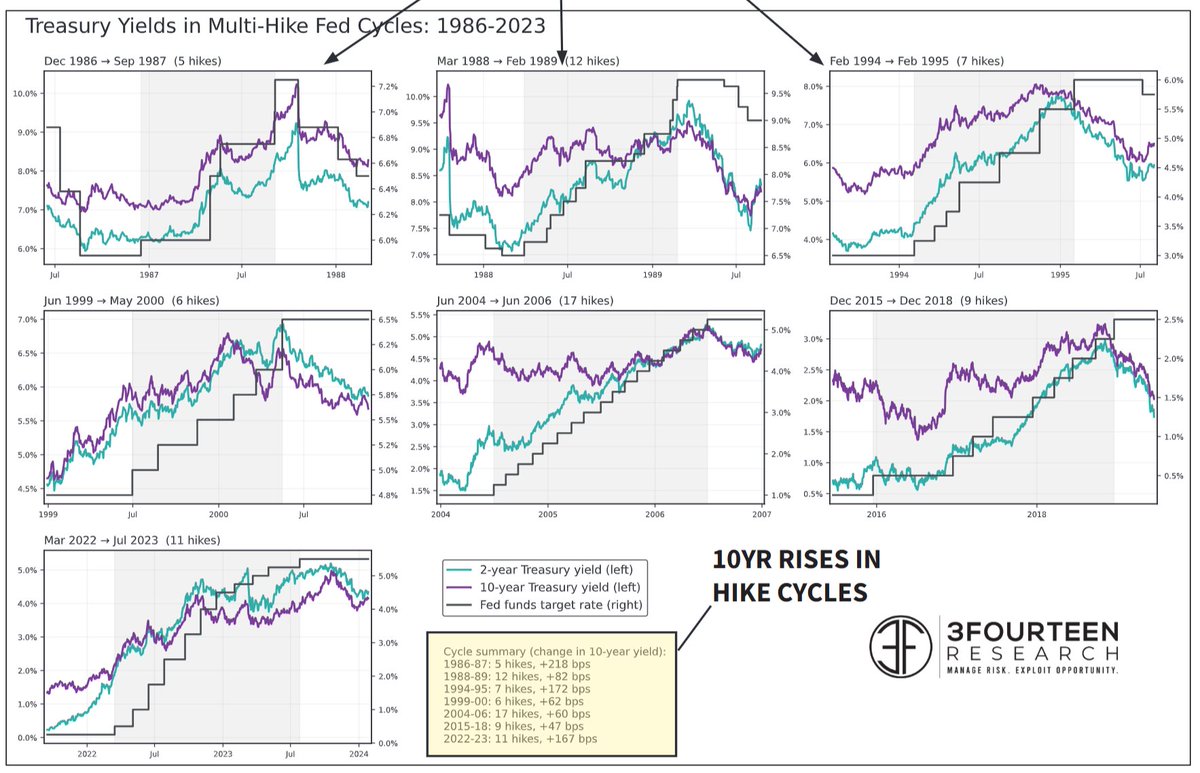
It's popular to suggest the 10y yield will fall if the Fed hikes rates this week.
Unless this is a "one and done" hike, though, history suggests the 10y will rise as the hike cycle progresses.
The 10y has risen in every modern hike cycle (especially early in the cycle).
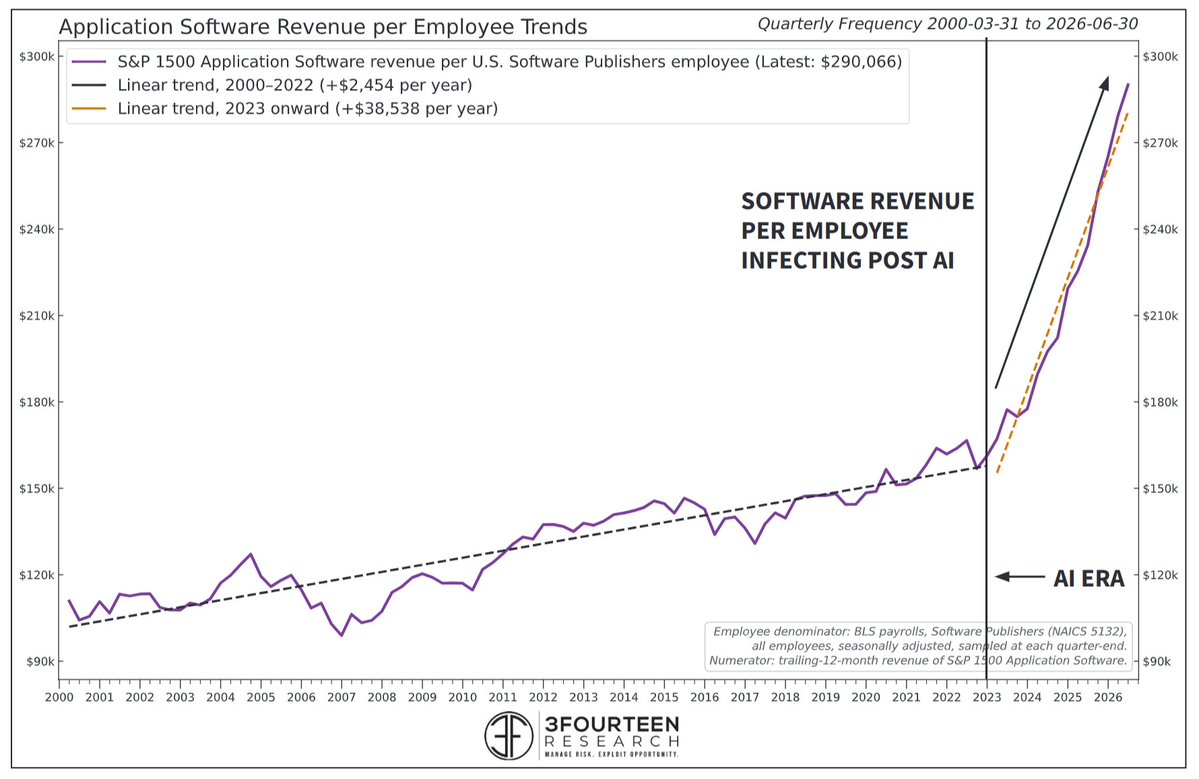
S&P 1500 Software revenue per employee has gone parabolic.
If you are looking for evidence that AI is starting to impact the real economy, this is exhibit A.
S&P 500
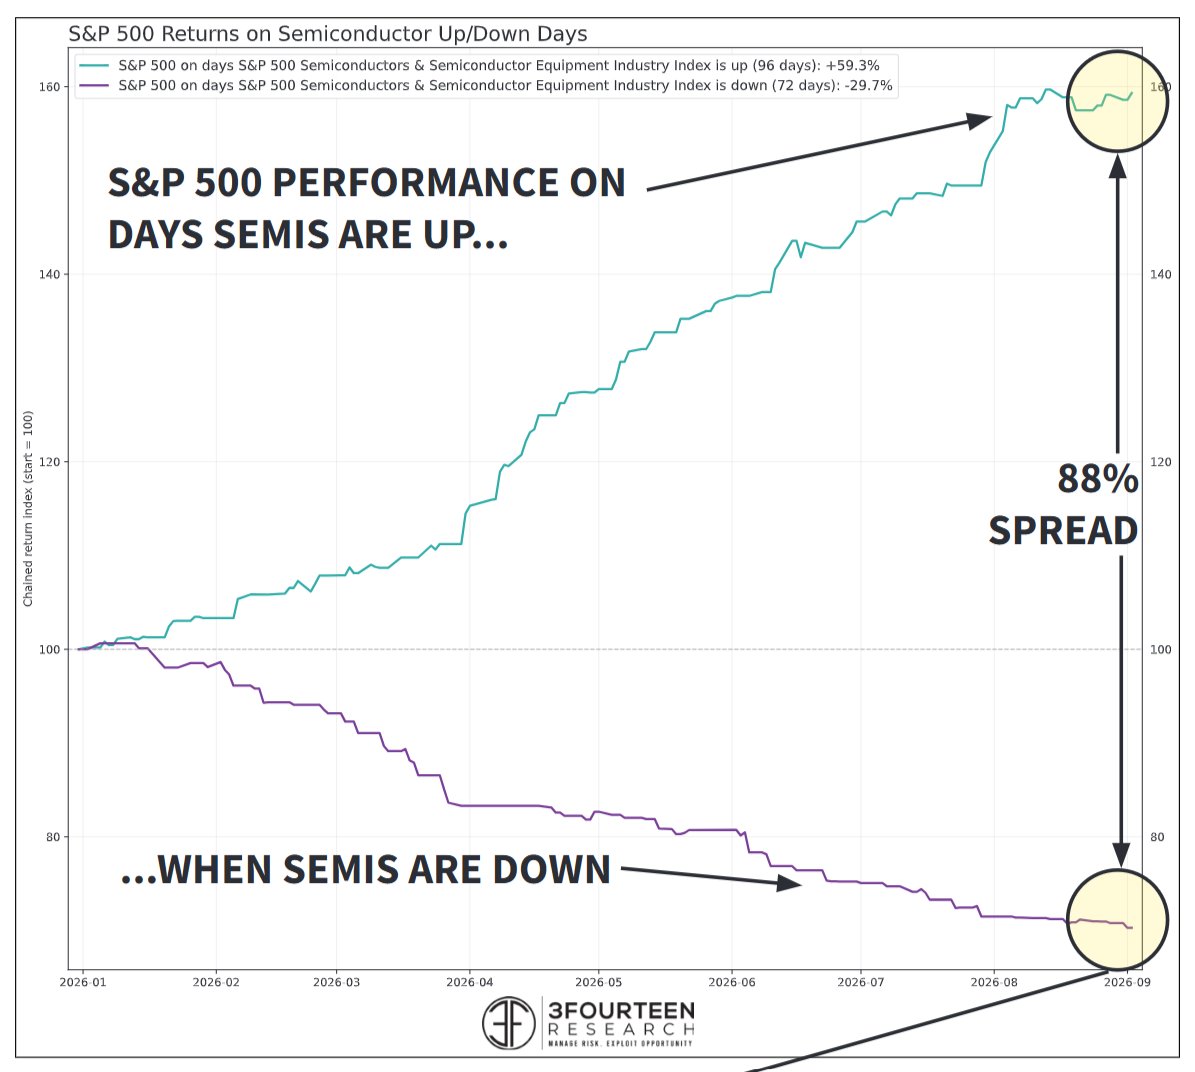
To make new highs, the market needs semiconductors to get into gear.
YTD, the S&P 500 is up ~60% on days when the semi industry is positive. But, the S&P 500 is down ~30% on days semis are down.
No other industry has had this large of an effect on the index in 2026.
OIL
-Brent futures >$100 (new post-Iran high).
-Dated Brent >$108 (DFL >$8/bbl...i.e. physical tightening).
Going back to the end of August, the paper market was starting to flash buy signals.
Below is a clip from the @3F_Research 8/27 Model Update.
OIL
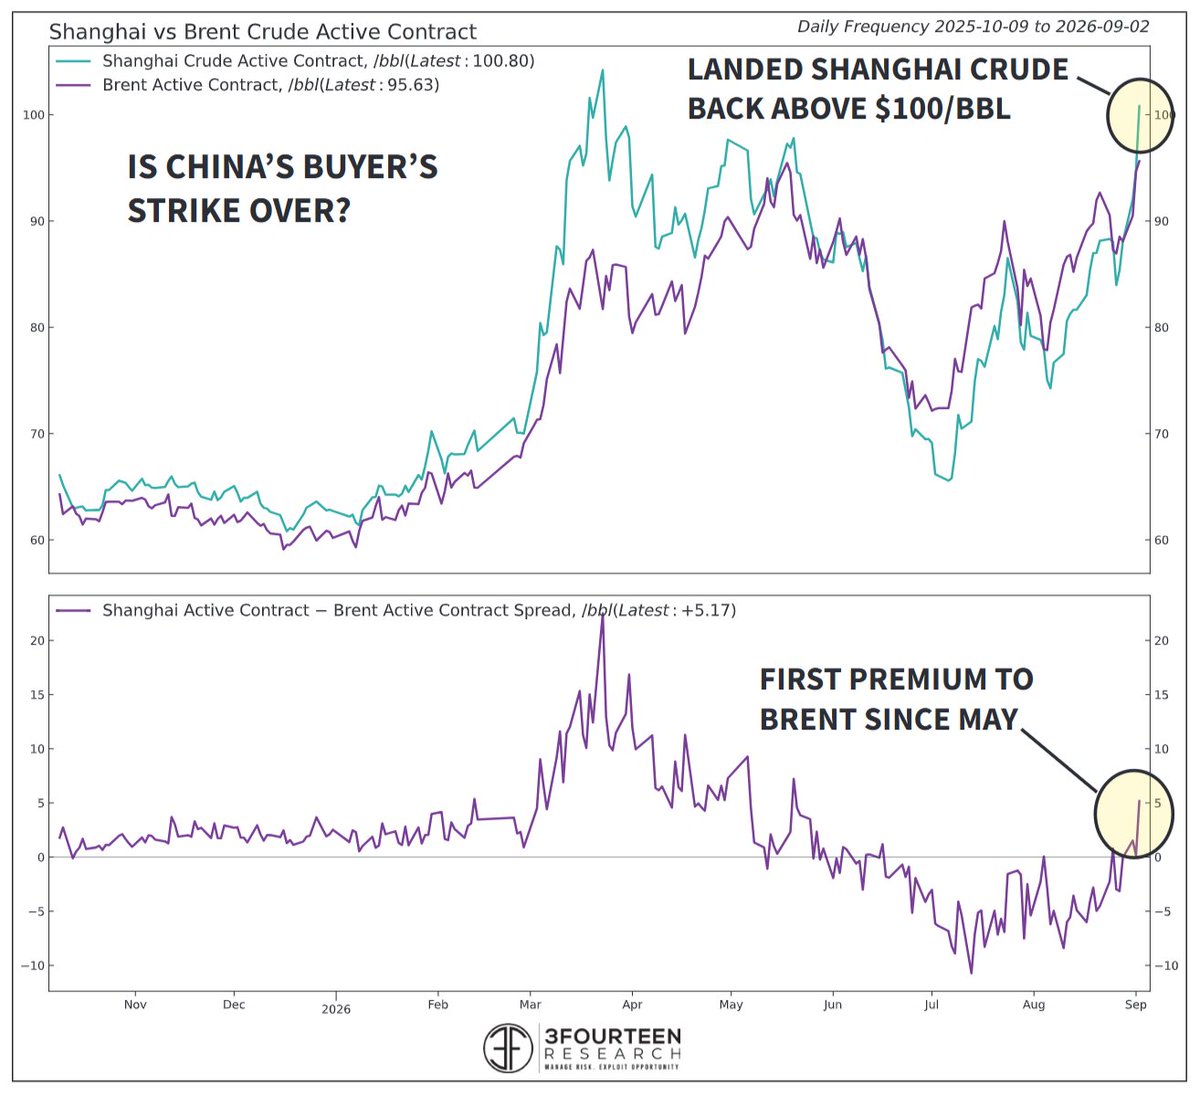
Shanghai crude futures above Brent Crude for the first time since May.
China's buyer strike has been the most important reason oil prices have remained subdued during the Iran War.
It seems China is buying again now...
This was as dovish as Waller could be.
Historically, I have liked how Waller conducts himself on the FOMC. But, hinging policy decisions on one print is a sign of how much political pressure the committee is feeling.
S&P 500 implied 1-month correlations remain in the single-digits.
Correlations have never been this low exiting a Q2 reporting season.
Of note, correlations keep moving lower in the AI age.
A few post JH macro opinions that feel out of consensus ATM:
1) The core of the FOMC - Waller, Williams, Powell - are in control. Warsh is calculating how to handle this.
2) There is little signal in the 30y yield (10y is key).
3) Hiking will be a policy mistake.
JULY PCE
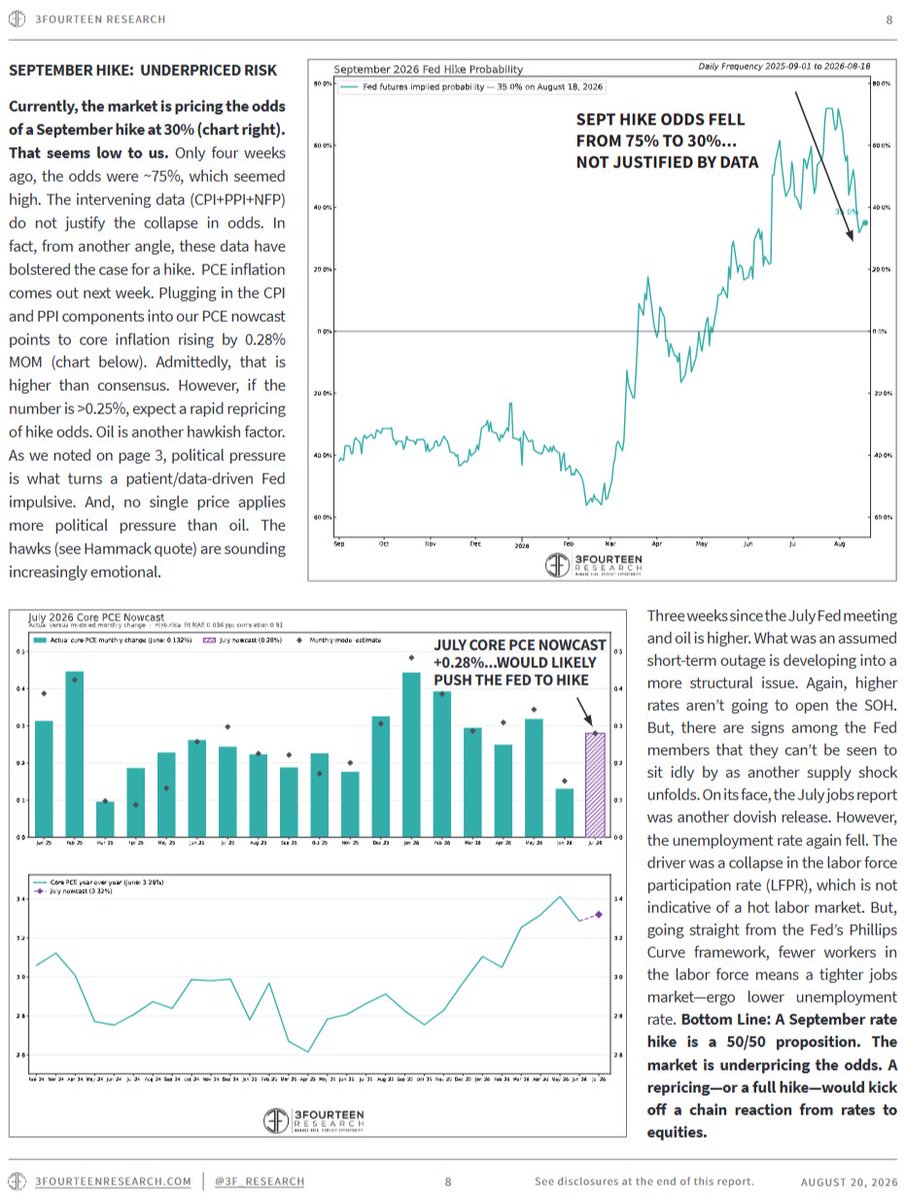
Core PCE comes in at .25% MOM...Hotter than consensus but not as hot as our nowcast predicted (.28%).
September hike odds move up from 34% before the release to 40% currently.
No one on the FOMC will say this explicitly, but there will be no stopping the momentum toward a hike if oil remains this high going into the September meeting.
Dec oil <$1 from new highs.
If oil is this high, there is no realistic CPI/PPI/NFP number that will stop a hike.