I’ve made over $50,000 in the past 3 months from using my ORB indicator
I made a FREE TRADING VIEW INDICATOR that tells you when to buy/sell based on my ORB strat. I’ve been testing it for months now
Like + Repost + Comment “SPX” and I’ll send it to you
(Must be following to DM)
$SPY $SPX
I AM OFFICIALLY RESTARTING THE $1,000 TO $1,000,000 $SPX 2026 CHALLENGE NEXT MONDAY! 💸
I’M GOING TO RESTART AND LET EVERYONE FOLLOW MY EXACT TRADES FOR COMPLETELY FREE IN A PRIVATE X GROUP CHAT! 🦅
LIKE, REPOST, & COMMENT “$SPX” TO BE ADDED! ❤️🔥
YOU MUST BE FOLLOWING ME TO JOIN! ☢️
[Barclays & Celsius]
Alright, finally listened to this tape so you don't have to. Here's my take on $CELH's actual dip, and things aren't as bad as the market believes them to be in my opinion.
The mess between $CELH & $PEP is a bit old now and based on two important factors to understand before we go further.
1. Celsius sells to Pepsi and then Pepsi sells to retailers. Meaning, Celsius' revenues come from Pepsi, not from retailers. Big distinction.
2. We know Pepsi is managing its inventory for some time now, restocking less than it used to because they still have stocks.
3. Management said during this exact same interview that sales were up 10% quarter to date, from the scanning data - meaning sales directly from retailers.
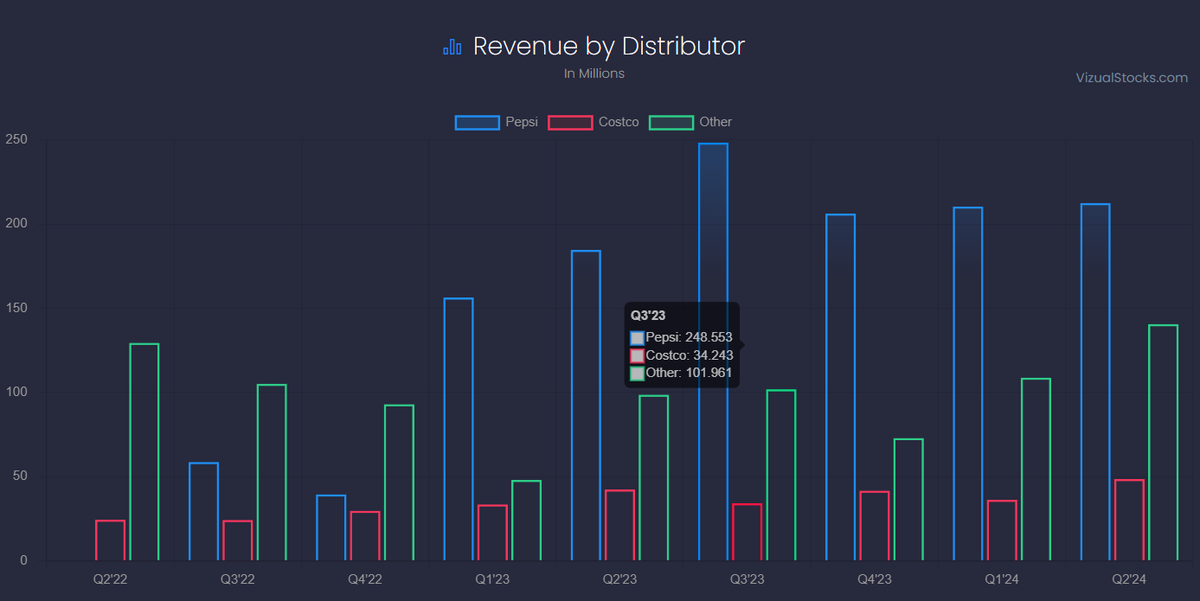
Now what management said during this interview is that so far, Pepsi bought between $100M & $120M less than Q3 last year.
Which means, as of now, they bought roughly $130M, compared to $212M last quarter. Those were the facts. Now, what do we think about it?
Parenthesis first, I am not sure if that is up to date, because september is part of Q3 and $PEP could still buy during the month.
First, Pepsi had bigger inventories than we thought and even though management said that this inventory optimization would continue through the year, I don't think many people expected something that big.
Second, if I have to rephrase what is happening, it's simply that Pepsi doesn't need to buy much more because they already have, meaning the hypergrowth of FY-23 was basically Pepsi stocking Celsius for a stronger demand than the real one.
But, data still shows that sales are up +10% QTD from retailers. Which still means that consumption is strong, customers are buying & buying more, directly in stores.
THIS. IS. ALL. ABOUT. TIMING. NOT. CONSUMPTION.
Celsius revenues are decreasing because they come from Pepsi, which still has stock and does not need to buy much yet!
But sales are growing, hence Pepsi stocks are shrinking & shrinking faster and at one point, they'll have to restock and buy from Celsius, with a much more stable rythm which should be much above $120M per quarter as this rythm is the "we already have stocks to sell" rythm.
This is when Celsius will cash its revenues.
This isn't announcing slower growth in my opinion. It's simply a timing issue, which the market sees as a lack of demand.