Institutional investor. Ex-founder (AI agents, robotics infra). Notes from both chairs on investing in AI, tokenization, longevity. Views my own. Not advice.
An $18.7Bn Market Failure: The Most Valuable Unclaimed Category in Robotics.
The global robotics market is a multi-trillion dollar opportunity, yet progress is being stifled by a massive, obvious gap: the difference between marketing hype and actual autonomy.
The industry is currently stuck in the "Demo-ware' era.
This isn't just an engineering problem… it's a form of market failure. Robotics lacks the critical, independent evaluation infrastructure that accelerated the LLM revolution.
This failure represents the most valuable unclaimed category in embodied AI.
Let's break down the problem, the blueprint, and the staggering commercial opportunity that awaits.
Markets underprice how resourceful people get when cornered. It's a game: one side plays a hand, the other finds the counter. CoreWeave's debt is stretched, so customers now prepay for capacity, some for the full contract upfront. That's financing. Management said it themselves: prepayments now beat the debt markets.
Same with stretched balance sheets. The ratios scream default. But lenders want loans performing, so they amend and extend, especially in a downturn. Incentives beat ratios.
The catch: risk doesn't disappear. It moves. The weak point now sits with the customers prepaying for compute. Equity or debt funded? Leverage in the system hasn't dropped. It continues to move.
@jukan05 my guess is the double counting is mostly in the pipeline not the backlog. LOIs and capacity holds are basically free to walk from, signed take or pay really isn't. so how much of that "10x demand" is just LOIs? first renegotiated contract will tell us a lot
Odd loop this week. Seeing reports on X that Nvidia is putting $10B into the Anthropic deal. If some of the Nvidia selling is people raising cash for the IPO, and most of what Anthropic raises goes back out as compute:
Sell the chipmaker, fund the customer, customer buys chips.
@Globalflows Wonder if it runs the other way into the 18th. The deal raises up to about $64B of fresh cash, with roughly 20% aimed at retail, and the book is reportedly already covered. That money has to come out of something, and AI megacaps are the obvious source. Supply first, pump after?
@emollick What I keep thinking about is the consultants' fix being too long for you to read, but working anyway. Fine for portal worlds. In most organizations someone has to sign off on it, so making it readable is half the job.
Did you ever ask it for the one-page version?
@MarkosAAIG@jukan05@damnang2 In the Samsung case, did the price floor still matter once the customer was reselling the extra volume below it? Trying to figure out whether these floors protect the supplier's selling price or just the invoice.
SCORE (SN44) is now a top 5 subnet on TAO
There's not many people I admire more that Max to discuss the market & their hardwork
Locked in, focused on taking Bittensor to the masses
Reading FC
AVIA
PwC France
As always, Full ep on Youtube
00:00 Market Discussion
01:08 Web2 markets
02:51 SCORE (SN44) entering $120b chocolate market
12:52 History and Evolution of SCORE (SN44)
17:33 Robotics: The Final Boss of AGI
27:45 The New Age of Compute
33:38 Visual Learning in Robotics
38:24 Closing
SCORE (SN44) is now a top 5 subnet on TAO
There's not many people I admire more that Max to discuss the market & their hardwork
Locked in, focused on taking Bittensor to the masses
Reading FC
AVIA
PwC France
As always, Full ep on Youtube
00:00 Market Discussion
01:08 Web2 markets
02:51 SCORE (SN44) entering $120b chocolate market
12:52 History and Evolution of SCORE (SN44)
17:33 Robotics: The Final Boss of AGI
27:45 The New Age of Compute
33:38 Visual Learning in Robotics
38:24 Closing
We're back on Supercycle discussing market trends
AI stocks continue to rip, $TAO and $TIG becoming leading AI names and $CHZ ushering next gen ownership for sports
Only on the Supercycle
I love speaking with @here4impact, who spent his career on Wall St prior to investing his fund in bittensor:native
Michael's #1 rule? Cashflow is King.
"At the end of the day, all that matters is cash flow...
Eventually if you don't generate cash, you are going out of business. That's just the way it works. There's no way around it."
Mitigated. Particularly on hyperscaler segment as you noted (was discussed on the last earnings call by mgmt). Segment GM is accretive to overall business.
Impact on Enterprise segment in ST but should be passed through via higher ASP over the medium term driving GM recovery for business. Would argue margin compression and NDR deceleration largely priced in drop since late '25.
Score (SN44) Founder @MaxScore shares his commitment to Bittensor:
"The switching costs aren't just technical, they're existential. Find the right incentive mechanism, get it running at the right pace, and you never touch it again. Right commodity, right price, right speed, right accuracy. You don't walk away from that."
After the Templar Covenant exit last week, the need for institutional grade risk frameworks couldn’t be more obvious
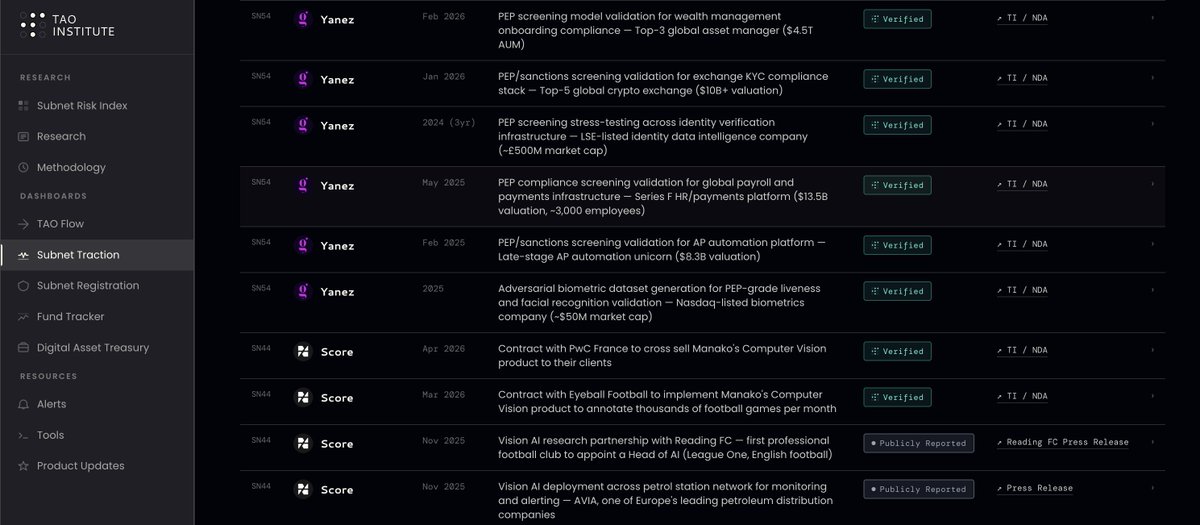
Since then we’ve seen Manako partner with PWC and multiple plans to rollout trillion parameter training runs from other subnets
Compute is being squeezed and non-AI companies are pivoting to GPU marketplaces to capture this insatiable demand (see All Birds Inc yesterday)
Capital is flowing into Bittensor subnets with minimal structure in evaluating signal. That’s how you get blindsided
@TAOInstitute_ gives institutional allocators the risk frameworks and evaluation tooling to actually underwrite these positions
Think of it as the infrastructure layer between capital and the subnet economy
We are now live; so kick the tyres on the platform and tell us what’s missing
TAO Institute brings independent research, real-time risk analytics, and subnet-level coverage to the Bittensor ecosystem.
Institutional-grade infrastructure for the open source AI economy.
Today, we launch TAO Institute
Day of celebration
Also sat down with Max from SCORE (SN44)
Walking through the contract Manako has with PwC France and this is amazing
Direct distribution to their clients, already with many clients under discussions for Manako
Never seen anything like it before from a big 4
Powered by $TAO
Participating in the open source economy
Verified first on @TAOInstitute_