$STRK is one of the very few privacy-related plays that hasn’t really had its move yet.
The privacy narrative is heating up, and $STRK is still lagging despite @Starknet now having native privacy infrastructure. That divergence is what makes me interested in it.
Definitely one I’m watching closely.
after previously hitting a portfolio ATH of $10 million on fomo three days ago
i just hit yet another portfolio ATH of $15 MILLION today — with a 30-day PNL growth of $11.6 million
i'm also officially the first-ever person to hit a $15 million portfolio on the platform
i'm also the all-time #1 trader on the platform and have gained over 450k followers on fomo
all in just a little over three months since joining the platform!
i'm up:
- $5 million in the last 24 hours
- $9.5 million in the last 7 days
from trades like:
- ethereum:0x07f5b6823751c2e2cd4560f28af75ff887102241: +9,200% on avg entry (+13,900% on first entry)
- $DELTA: +918%
- $Microduck: +1,513%
- $MARSCOIN: +205%
- solana:Dz9mQ9NzkBcCsuGPFJ3r1bS4wgqKMHBPiVuniW8Mbonk: +231% (gonna run it back to ATHs and beyond soon, God willing 👀)
and here's the part that might surprise you:
i'm trading almost exclusively on fomo these days
i've taken a dozen+ new trades on fomo in the past month, and i'm up on more than half of my trades so far!
meanwhile, i don't think i've posted more than 1-2 new trades on X or TG during that same period
so if you're only following me on X...
you're probably missing A LOT of my trades
if you want to actually follow what i'm trading, you should join fomo through my ref link:
https://t.co/J39grZN8rY
i'm currently giving away $350k to active fomo refs i.e. people who join the platform through my link, follow me, and actively use it
i would also like to reiterate, like i did in my last update:
this trade and the recent successes is NOT me
it is all GOD
only HIM!!!
ALL GLORY BE TO THE ALMIGHTY GOD AND TO HIM ALONE 🙏
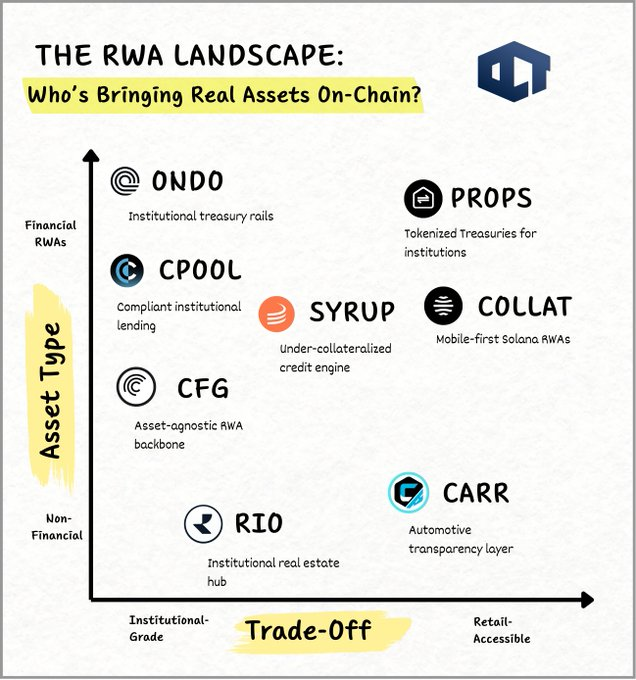
THE RWA REVOLUTION
Where Real Assets Meet Blockchain Innovation..
Who’s About to Pull the Next 50x?
→ $ONDO
→ $SYRUP
→ $CPOOL
→ $CFG
→ $CARR
→ $RIO
→ $PROPS
→ $COLLAT
Let's dive in����
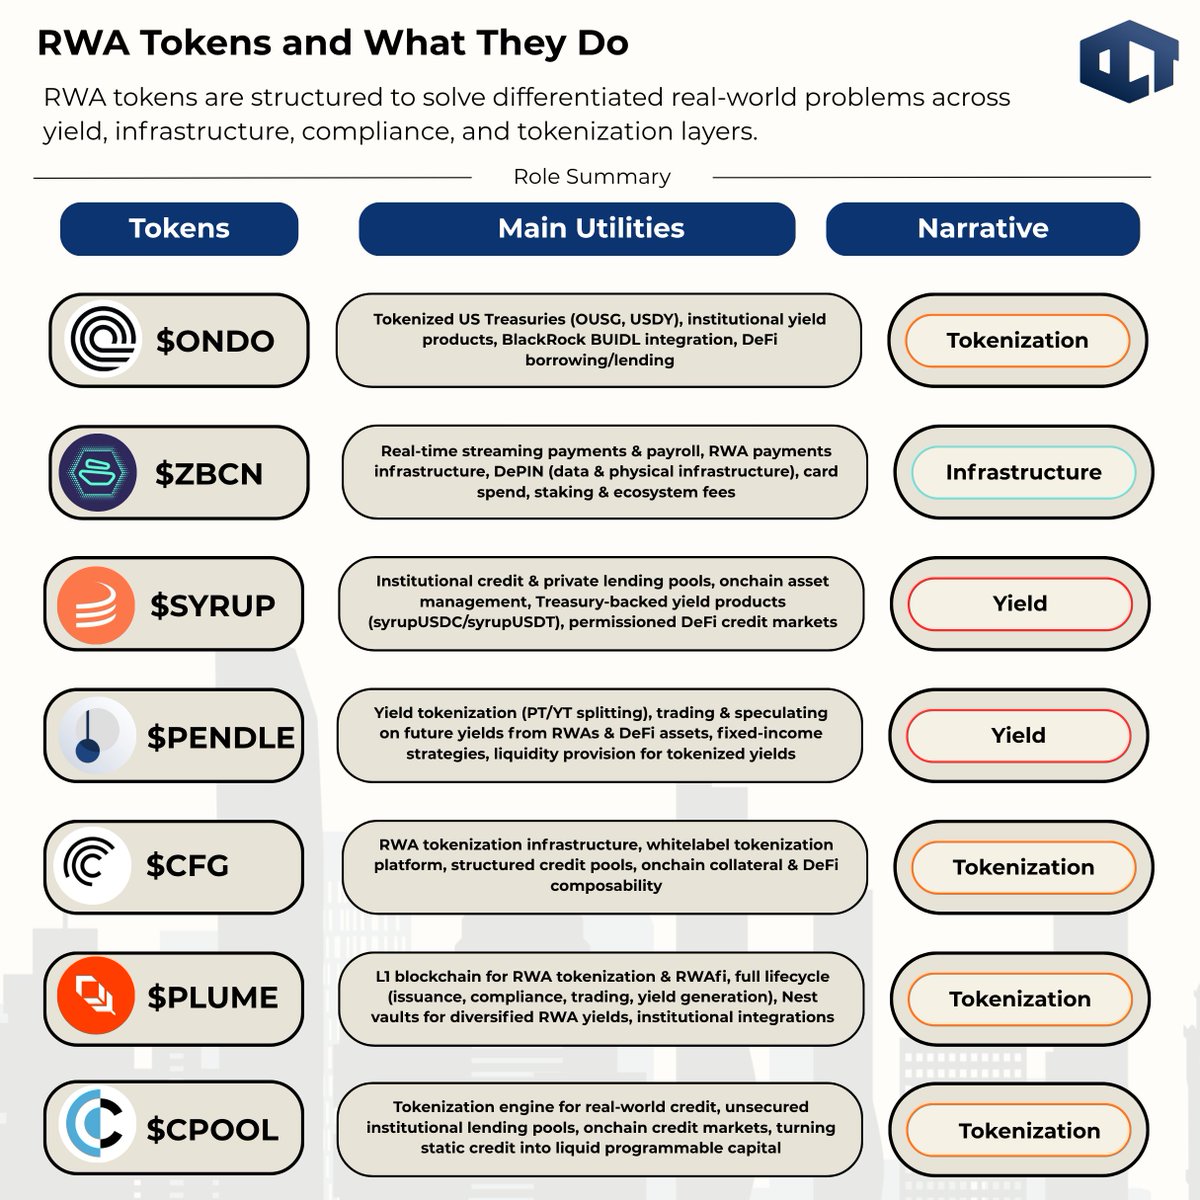
🔵 Ondo Finance ( $ONDO ): Flagship RWA rail for institutional assets
Focus / Use Case:
Tokenization of top-tier TradFi instruments Treasuries, MMFs, bonds, ETFs, and stocks with fractional access, global liquidity, and institutional-grade regulatory alignment.
Architecture:
• Ondo Chain (PoS L1 purpose-built for RWAs)
• Multi-chain footprint: Ethereum, Solana, Mantle, BNB, Sui, Manta
• Investment APIs for fintechs + asset managers
• Omnichain asset management → users move RWAs across ecosystems frictionlessly
Economics:
• $ONDO = governance, staking, fee accrual
• Fees flow into buybacks
• Vesting ensures predictable supply
• Serious projections: $30T+ RWA market by 2030 → Ondo is already positioned as a core liquidity venue
Adoption:
• Partnerships with BlackRock (BUIDL), Aon, Franklin Templeton (including tokenized ETFs), McKinsey, ABN AMRO
• Nov 2025: $25M into Figure’s YLDS stablecoin
• EU approval for tokenized US stocks
• Binance Wallet listed 250+ tokenized US stocks/ETFs → 280M+ users
• Recent: Glider partnership for automated, fee-free tokenized stock portfolios
My take:
Ondo is the closest thing to a “Bloomberg Terminal → On-chain.”
It has the partnerships, the regulatory clarity, the treasury exposure, and the institutional trust that most RWA projects wish they had.
Nothing about Ondo feels experimental it feels like the institutional layer DeFi has been missing for a decade.
When banks and asset managers eventually tokenize their portfolios, Ondo is the chain that actually fits into their compliance workflows.
In a world where RWAs go mainstream, Ondo becomes a global settlement layer for real-world capital.
To me, this is the most blue-chip RWA asset on the market not because of hype, but because every move they make screams “institution-scale infrastructure.”
🟠 Maple Finance ( $SYRUP ): DeFi-native institutional credit rebuilt and battle-hardened
Focus / Use Case:
Under-collateralized lending for institutions + yield-bearing stable assets (syrupUSDC / syrupUSDT) designed for stable, predictable returns.
Architecture:
• Ethereum core + Solana integrations
• Hybrid permissioned/permissionless model
• Composable LP tokens for yield routing
• High-quality borrower underwriting handled by delegated credit specialists
Economics:
• $SYRUP governs, stakes, earns protocol revenue
• 25% of platform fees → buybacks
• $115M+ annualized protocol fees
• TVL path targets $3B+ in 2026
• Staked $51.27M secures the network
My take:
Maple has quietly become the “Wall Street credit desk of DeFi.”
They survived defaults, rebuilt underwriting frameworks, cleaned up risk management, and came back with better transparency, stronger credit partners, and more predictable yield structures.
What I appreciate about Maple is how real the borrowers are market makers, fintech lenders, liquidity firms, not anonymous wallets.
Syrup’s yields are not DJEN APY fantasies they’re tied to actual, cash-flow-generating counterparties.
SYRUP is no longer a speculative token it’s a proxy for the growth of on-chain institutional credit.
In a space full of noise, Maple has matured into a genuine financial primitive.
🟣 Clearpool ( $CPOOL ): Credit infrastructure for compliant global lending
Focus / Use Case:
Institutional uncollateralized lending + PayFi + Treasury-backed yield strategies.
Architecture:
• Multi-chain protocol (Ethereum, Polygon, Arbitrum, Flare)
• Ozean L2 → compliance-first RWA environment
ERC-7540-native design
• cpUSD = Clearpool’s yield-bearing dollar
Permissionless + permissioned pools with modular risk profiles
Economics:
• $CPOOL staking → governance, vault security
• Revenue → buybacks & burns
• Dual token structure for risk segmentation
• Market cap: $23.3M, real-world APY ~4%+
Adoption:
• TVL: $46.29M
• Loans originated: $830M+
• Serves fintech lenders, remittance firms, and institutions
• Expanding into emerging markets where payment rails are slow
My take:
Clearpool is solving the boring-but-critical part of RWAs:
Credit infrastructure for compliant, repeatable, institution-friendly lending.
Where Maple leans into institutional credit sophistication, Clearpool leans into payments, Treasury strategies, and embedded fintech use cases.
It’s the kind of protocol that quietly grows behind the scenes because real businesses need what it builds.
As stablecoins become the de facto global settlement currency, Clearpool feels perfectly positioned to capture billions in real-world payment flows.
🟢 Centrifuge ( $CFG )
The backbone of asset-agnostic tokenization
Focus / Use Case:
Tokenizing invoices, real estate, credit, funds essentially any off-chain asset and turning them into investable, yield-bearing pools.
Architecture:
• Ethereum + Base + Avalanche + Plume
• ERC-7540 ready
• Tinlake pools with DROP/TIN tranches (institutional-grade risk structuring)
• Automated management, diversified asset onboarding pipelines
• Deep integrations with MakerDAO, Aave, S&P DJI
Economics:
• $CFG = governance, staking, fees
• Treasury + revenue share supports rewards
• Designed for large-scale fund deployment
Adoption:
• S&P DJI (S&P 500 Fund) tokenized pilot
• BlockTower, ParaFi, MakerDAO partnerships
• Caesar partnership for on-chain equity tokenization
• New Whitelabel product for institutions to deploy RWA funds quickly
• Recent: LayerZero partnership for multi-chain expansion
My take:
If DeFi ever wants to become “real finance,” it needs a backend that can onboard any type of asset not just treasuries.
Centrifuge is that backend.
The DROP/TIN model created something close to institutional credit structuring inside DeFi.
Its integrations with MakerDAO literally backstop DAI with real-world income streams.
Centrifuge has quietly built the infrastructure that asset managers will eventually rely on to deploy billions on-chain.
It’s not flashy but it’s foundational.
🟡 Carnomaly ( $CARR )
A practical RWA niche fixing the vehicle data problem
Focus / Use Case:
Vehicle history, ownership transparency, VIN-linked NFTs, dealer verification, maintenance rewards.
Architecture:
• Ethereum + Polygon
• CarrChain → stores authenticated vehicle history
• Apps for VIN scanning, odometer logs, service uploads
• Bridges real-world automotive data with on-chain verification
Economics:
• $CARR for rewards, staking, smart contracts
• Buyback + burn mechanics
• Real utility tied to user engagement
Adoption:
• v3 global app live
• International VIN decoding via Vincario + Car Check
• Growing user community
• Expanding into a $2T automotive data market
• 2026 roadmap: Europe app launch, dealer expansion, revenue sharing
My take:
Carnomaly is refreshingly practical.
Not everyone wants tokenized treasuries but everyone hates opaque, unreliable car histories.
CARR turns a messy real-world data problem into a verifiable on-chain record.
It’s not chasing institutions it’s chasing everyday consumers.
And sometimes consumer pain points create stronger adoption flywheels than institutional pilots.
This is a bet on transparency becoming default in the auto market.
🔴 Realio Network ( $RIO )
The multi-chain real estate & private equity platform
Focus / Use Case:
Tokenized real estate, private equity, fractional access, plus digital/physical convergence via their Districts metaverse.
Architecture:
• Cosmos L1 with EVM + IBC compatibility
• Multi-asset staking
• Freehold Wallet for non-custodial management (recent updates: in-app staking & cross-chain swaps)
• Reg D/S offerings → fully compliant issuance pipeline
Economics:
• $RIO for governance, fees, staking
• Supply capped at 175M
• FDV ~$25.98M → significant room for narrative expansion
My take:
Realio is doing something interesting:
Bringing institutional real estate while simultaneously building a digital twin economy.
Its multi-chain architecture and regulatory-first approach stand out in a category filled with half-compliant experiments.
RIO has a clear identity tokenized real estate, institutional-grade issuance, and liquidity frameworks
and a long-term vision through Districts.
In an industry where compliance decides winners, Realio is playing the right game.
🟤 Propbase ( $PROPS ): Fractional Southeast Asian real estate retail-friendly RWAs
Focus / Use Case:
Fractional property investing from $100 → earn rental yields → trade on a secondary marketplace.
Architecture:
• Built on Aptos (speed + cheap fees)
• Bridged to Base
• Smart contracts handle ownership, rent distribution, marketplace activity
• Mobile-first + governance via Nexus
Economics:
• $PROPS used for fees, staking, rewards
• Buybacks tied to platform use
• 443M circulating supply
Adoption:
• Aave/Compound-style P2P lending planned
• DeFAI liquidity roadmap
• Partnerships with Chainge
• Strong community and referral-based growth
• KuCoin listing + record volume momentum
My take:
Propbase is RWA for the everyday person not funds, not institutions.
SE Asia is one of the world’s hottest property markets, but access is traditionally restricted or capital-intensive.
PROPS breaks that barrier.
It feels like the “Robinhood of tokenized real estate” simple UX, low minimums, mobile-first, and relatable to users who are not crypto-native.
This is one of the most consumer-aligned RWA projects in the entire list.
🟣 Collaterize ( $COLLAT ): Solana-speed RWA onboarding
Focus / Use Case:
Tokenized real estate, art, collectibles, and more delivered through a smooth, mobile-first interface.
Architecture:
• Lives on Solana + its own Collaterize Chain
• Cross-chain aggregation
• Credit-card + crypto payments
• Gamified treasury system for compounding value creation
Economics:
• $COLLAT → governance, rewards, airdrops
• Treasury growth + 75% of launch fees → buybacks
• Retail-friendly token incentives
Adoption:
• Listed on Indodax & Bittime
• $640k+ 24h volume
• Strong push toward retail RWA pools + easy user onboarding
My take:
Collaterize is the “mobile-first RWA app” Solana has been missing.
It’s fast, simple, and built for retail accessibility rather than institutional partners.
The treasury-gamification angle is clever it turns RWA participation into a community-driven growth flywheel.
It’s early, but the UX approach positions it for fast adoption once RWA retail interest explodes.
🔚 Conclusion: The RWA Split
🏦 Fixed Income & Treasuries
$ONDO, $SYRUP
Institution-scale yield, ~$5.03B combined TVL, strong regulatory backing.
💳 Credit & Lending
$CPOOL, $CFG
Backbone of on-chain credit + diverse asset financing.
🏠 Real Estate & Niche Assets
$RIO, $PROPS, $COLLAT
Fractional ownership across property, equity, and collectibles.
🚗Automotive Innovation
$CARR
Real-world transparency layer for the $2T global auto market👇
🚨 WARNING: DO NOT LONG BITCOIN RIGHT NOW
The relief rally officially ends on Monday.
This Bull Trap is playing out exactly how I predicted.
The plan is simple:
$78K → $64K → $53K → $48K → New Cycle
Quick reminder:
I publicly called Bitcoin’s $17K bottom in 2022.
Then I publicly called the $126K top in 2025.
The next major call will be posted here first.
Follow and turn notifications on.
Dom’s response was somewhat boring and foolish. He could have simply ignored the post, but instead of directly addressing why the price has fallen so dramatically, he chose to offer 7,500 ICP as a “reward” to someone who merely pointed out an undeniable fact.
Why do this?
7,500 ICP could be put toward so many meaningful things. Hell, even if you were willing to burn it, that would at least contribute to deflation.
But look at the tokenomics right now: total supply has already reached 556 million ICP, while the amount being burned is still nowhere near the amount being minted.
It's better to spend some time doing things that actually improve the fundamentals, drive the price higher, and benefit investors instead.
internet-computer:native