In addition to news updates, I also post my views on the stock market or specific stocks every day. Here is my personal phone number:
Link: https://t.co/aSMo4nTQFn
Add me as a friend, and I’ll share the stocks I’ll be focusing on next week.
Group Benefits: The latest and most comprehensive news updates, precise stock symbols, and take-profit and stop-loss levels.
Please follow me and leave a comment or send a private message—I’ll add you to the group immediately
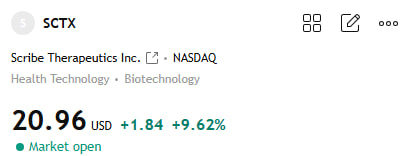
$SCTX +9.6%
Scribe Therapeutics is a clinical-stage biotechnology company focused on engineered in vivo CRISPR tools (epigenetic silencing ELXR and gene editing XE) targeting the three major lipid drivers of atherosclerotic cardiovascular disease: LDL-C, Lp(a), and triglycerides.
Single-dose, long-acting lipid-lowering therapy. Its lead product, STX-1150, is a liver-targeted PCSK9 epigenetic silencing therapy (which does not permanently alter DNA) that has entered Phase 1 trials in Australia and New Zealand, with preliminary data from the single-dose arm expected in the first half of 2027.
Data from non-human primates are robust (LDL-C reductions of up to 68% with a single dose; reductions of >50% at relevant doses sustained for two years). Subsequent candidates STX-1200 (Lp(a)) and STX-1400 (APOC3) have received approximately $25.7 million in non-dilutive funding from CIRM and are advancing toward clinical trials.
The company raised approximately $155.5 million through an IPO and a private placement with Sanofi, providing cash reserves through the first half of 2029.
Short-term (until the data window): Target price range of $18–24; if Phase 1 shows positive safety and lipid-lowering signals, there is significant upside potential in the medium term. Risks include clinical translation, competition, and execution.
#QQQ #STOCK #SCTX
$SWMR
Short term (until the next acquisition or order update): Expect a range of $9–12; if revenue growth becomes evident, there is potential for event-driven gains in the medium term. Risks include dilution, losses, and execution issues.
TSMC beat and still got sold with the group. Sixth straight record quarter, strong margins, advanced nodes dominant. Cautious tone on 2027. The print answered demand; the multiple is answering valuation.
$NNNN
Anbio Biotechnology is an in vitro diagnostics company focused on biomarker testing products for infectious diseases, cancer, and other conditions. With revenue of approximately $8.6 million projected for FY2025 and high gross margins, its stock price has fallen sharply.
Valuations for small-cap diagnostics stocks are being reset. High gross margins and product portfolio are the foundation, but the market is focused on growth realization and cash burn.
Short-term (until the next earnings report or product update): Expect a range of $3.2–4.2; if order growth or channel expansion materializes, a recovery is possible in the medium term. Risks include competition, regulation, and execution.
If you’d like to track the commercialization of diagnostic products, leave a comment or send a private message.
#QQQ #STOCK #NNNN
$CRUS
Withdrawal from the bid for Synaptics removes the risks of dilution and integration. The price barely moved today and remains near its 52-week low. It closed at 107.99 yesterday. Today, it opened at 107.09, hit a low of 106.24, a high of 108.57, and closed at 108.34, up 0.3%.
The 105–120 trading range remains intact. The market will digest this news ahead of the earnings report in early November. Market cap is approximately $5.4 billion. The P/E ratio is about 13x. The median analyst price target is around 165. The 52-week low is 105.77, and the high is 180. Cirrus manufactures audio and high-performance mixed-signal chips, with core clients including consumer electronics companies such as Apple.
The company confirmed that it had previously approached Synaptics (referred to as “Party A” in SEC filings) with an acquisition proposal but is no longer pursuing it and will not comment further. ON Semiconductor changed its offer for Synaptics from a stock-for-stock deal to an all-cash offer of $123 per share, valued at approximately $5.7 billion; after evaluation, the board selected ON Semiconductor. For CRUS, the exit eliminates significant dilution and integration risks, allowing the market to refocus on the core business.
Recently, Q1 FY27 revenue hit a record of approximately $460 million, with double-digit year-over-year growth and robust profit margins. Risks include customer concentration and industry cycles. The $460 million figure demonstrates that the core business remains strong. The $108 valuation reflects a return to core fundamentals following the withdrawal from the bidding war—not because Apple orders have already been confirmed for the full year. Earnings report is on November 4.
Stay tuned for earnings reports, customer orders, and capital allocation updates—feel free to comment or send a private message.
This is not investment advice.
#QQQ #STOCK #CRUS
$CRUS
Cirrus Logic is an audio and high-performance mixed-signal chip company whose core customers include consumer electronics manufacturers such as Apple.
The company confirmed that it had previously submitted an acquisition proposal to Synaptics (referred to as “Party A” in the SEC filing), but is no longer pursuing the transaction and will not comment further.
Previously, onsemi changed its offer for Synaptics from a stock-for-stock deal to an all-cash offer of $123 per share (approximately $5.7 billion), and after evaluation, the board selected onsemi’s proposal.
For CRUS, withdrawing from the competition eliminates potential risks of significant dilution and integration, allowing the market to refocus on its core business. Recently, Q1 FY27 revenue hit a record high of approximately $460 million (double-digit year-over-year growth), with robust profit margins.
The stock price is near its 52-week low, with a relatively reasonable valuation (approximately 13x P/E), and the median analyst price target is around $165.
In the short term (until the earnings report in early November): Expect the stock to consolidate within the $105–120 range as the market digests the news; if Apple-related orders and the mixed-signal business remain robust, there is room for a recovery in the medium term.
Risks include customer concentration and industry cycles. If you’d like to track earnings reports, customer orders, and capital allocation, please leave a comment or send me a private message.
#CRUS #CirrusLogic #Semiconductors #Synaptics #MAndA #AppleSupplyChain
Q1 FY27 revenue recently hit a record high of approximately $460 million (double-digit year-over-year growth), with robust profit margins. The stock price is near its 52-week low, and the valuation is relatively reasonable (approximately 13x P/E), with the median analyst price target at around $165.
https://t.co/umLaJm9OMA
$CRUS
Cirrus Logic is an audio and high-performance mixed-signal chip company whose core customers include consumer electronics manufacturers such as Apple.
The company confirmed that it had previously submitted an acquisition proposal to Synaptics (referred to as “Party A” in the SEC filing), but is no longer pursuing the transaction and will not comment further.
Previously, onsemi changed its offer for Synaptics from a stock-for-stock deal to an all-cash offer of $123 per share (approximately $5.7 billion), and after evaluation, the board selected onsemi’s proposal.
For CRUS, withdrawing from the competition eliminates potential risks of significant dilution and integration, allowing the market to refocus on its core business. Recently, Q1 FY27 revenue hit a record high of approximately $460 million (double-digit year-over-year growth), with robust profit margins.
The stock price is near its 52-week low, with a relatively reasonable valuation (approximately 13x P/E), and the median analyst price target is around $165.
In the short term (until the earnings report in early November): Expect the stock to consolidate within the $105–120 range as the market digests the news; if Apple-related orders and the mixed-signal business remain robust, there is room for a recovery in the medium term.
Risks include customer concentration and industry cycles. If you’d like to track earnings reports, customer orders, and capital allocation, please leave a comment or send me a private message.
#CRUS #CirrusLogic #Semiconductors #Synaptics #MAndA #AppleSupplyChain
$SCTX +9.6%
Scribe Therapeutics is a clinical-stage biotechnology company focused on engineered in vivo CRISPR tools (epigenetic silencing ELXR and gene editing XE) targeting the three major lipid drivers of atherosclerotic cardiovascular disease: LDL-C, Lp(a), and triglycerides.
Single-dose, long-acting lipid-lowering therapy. Its lead product, STX-1150, is a liver-targeted PCSK9 epigenetic silencing therapy (which does not permanently alter DNA) that has entered Phase 1 trials in Australia and New Zealand, with preliminary data from the single-dose arm expected in the first half of 2027.
Data from non-human primates are robust (LDL-C reductions of up to 68% with a single dose; reductions of >50% at relevant doses sustained for two years). Subsequent candidates STX-1200 (Lp(a)) and STX-1400 (APOC3) have received approximately $25.7 million in non-dilutive funding from CIRM and are advancing toward clinical trials.
The company raised approximately $155.5 million through an IPO and a private placement with Sanofi, providing cash reserves through the first half of 2029.
Short-term (until the data window): Target price range of $18–24; if Phase 1 shows positive safety and lipid-lowering signals, there is significant upside potential in the medium term. Risks include clinical translation, competition, and execution.
#QQQ #STOCK #SCTX
Several stocks on the market have already been volatile since the early trading session today.
Stock Code: S***
Like and comment or send me a private message, and I’ll send you the full report directly.
Add my WhatsApp number (listed on my profile) to get the full information in advance.
Several stocks on the market have already been volatile since the early trading session today.
Stock Code: S***
Like and comment or send me a private message, and I’ll send you the full report directly.
Add my WhatsApp number (listed on my profile) to get the full information in advance.
$CRUS
Cirrus Logic is an audio and high-performance mixed-signal chip company whose core customers include consumer electronics manufacturers such as Apple.
The company confirmed that it had previously submitted an acquisition proposal to Synaptics (referred to as “Party A” in the SEC filing), but is no longer pursuing the transaction and will not comment further.
Previously, onsemi changed its offer for Synaptics from a stock-for-stock deal to an all-cash offer of $123 per share (approximately $5.7 billion), and after evaluation, the board selected onsemi’s proposal.
For CRUS, withdrawing from the competition eliminates potential risks of significant dilution and integration, allowing the market to refocus on its core business. Recently, Q1 FY27 revenue hit a record high of approximately $460 million (double-digit year-over-year growth), with robust profit margins.
The stock price is near its 52-week low, with a relatively reasonable valuation (approximately 13x P/E), and the median analyst price target is around $165.
In the short term (until the earnings report in early November): Expect the stock to consolidate within the $105–120 range as the market digests the news; if Apple-related orders and the mixed-signal business remain robust, there is room for a recovery in the medium term.
Risks include customer concentration and industry cycles. If you’d like to track earnings reports, customer orders, and capital allocation, please leave a comment or send me a private message.
#CRUS #CirrusLogic #Semiconductors #Synaptics #MAndA #AppleSupplyChain
TSMC is tomorrow. The ADR closed Tuesday near $445, about 9% off its early-October high. Guidance is for gross margin 65–67%. The print is expected to be a sixth straight record.
#TSMC#TSM
$LIFE
Ethos is a digital life insurance technology platform that transforms the traditionally complex and time-consuming underwriting process into a fast, online experience through direct sales and third-party channels.
Key Metrics: Q2 revenue of $189.6M (+113% YoY), with direct sales up 131% and third-party channels up 90%; new policies exceeded 107,000 (+133%), bringing the cumulative total to over 700,000. The quarter delivered GAAP net income of $19.5M, an adjusted EBITDA margin of approximately 19%, and positive operating cash flow.
Full-year guidance was raised to revenue of $727–731 million (approximately +88%) and adjusted EBITDA of $119–123 million, and a share buyback program of up to $100 million was initiated. The platform boasts extremely high gross margins, with growth driven by the scale of policy activations and channel expansion rather than simply pricing.
The next earnings report is scheduled for November 2 (Q3). Analyst consensus is strongly bullish, with target price ranges generally between $32 and $40 (recently raised to $40). In the short term (through the Q3 earnings report): expect a range of $36–41; if policy activations and revenue continue to grow strongly and margins remain stable, the stock could approach $40–42.
High growth and a profit inflection point are the key themes; execution will determine the upside potential.
If you’d like to track policy growth, channel contributions, and the next earnings report, please leave a comment or send me a private message.
#LIFE #Ethos #Insurtech #LifeInsurance
UnitedHealth (UNH) reported its third-quarter 2026 results and raised its full-year 2026 earnings guidance. UnitedHealth reported third-quarter revenue of $112.7 billion and operating income of $6.6 billion; earnings per share (EPS) were $4.56, and adjusted EPS were $4.69. The company raised its full-year 2026 adjusted earnings per share guidance to at least $20.50, up from the previous range of $19.50 to $20.00. Third-quarter operating cash flow totaled $5.1 billion. As of September 30, the company’s debt-to-equity ratio stood at 41.7%.
Group CEO Stephen Hemsley said, “This quarter’s results reflect the team’s discipline and execution across all business lines. We continue to drive the Group’s transformation and are committed to providing a simpler, more comprehensive service experience for patients and the clinicians who care for them.”
Oil eased, but the level is still high. WTI around $91.85 (−2%), Brent around $104.50 (−2%) after Monday’s jump on the Saudi airport strikes. A 2% pullback does not erase the $100-plus Brent.
#Oil#Brent
$KDK
The company reaffirmed its plan to launch commercial long-distance autonomous driving services by the end of the year; its Autonomy Readiness Measure has risen to 96% (up from 93% at the end of August). Routes such as Dallas-Houston and IKEA continue to move forward, and the company is collaborating with partners including AWS.
Analyst targets remain in the higher range, with a short-term rebound expected to $2.0–2.5. The key catalysts are the progress of the driverless launch and the completion of safety cases; meeting these milestones would provide significant upside, while delays would continue to weigh on the stock, leading to high volatility.
If you’d like to see the launch timeline and risk milestones, please leave a comment or send me a private message.
#KDK #QQQ #STOCK
The week has three clocks. Today: thin equity tape, oil headlines, no cash bonds. Tuesday: the first bank prints. Thursday: TSMC. If oil stays over $100 and the banks do not expand margins, December is back on the table.
#QQQ#Stocks
Apple cut a build, not a narrative. The stock fell 1.1% on a report that it asked suppliers to trim component production for the iPhone 18 Pro and Pro Max. The reasons given: memory costs and demand.
#AAPL#Memory
$MU
Three separate points. The price showed almost no clear direction today. Yesterday’s close was 1,035.84. Around 1:00 p.m. Eastern Time, it was trading at approximately 1,027–1,028, down less than 1%, with volume already nearing 10 million shares. The closing price hasn’t been released yet.
The 1,020–1,080 trading range remains intact. It didn’t reach 1,090, and 1,120 is out of the question. It hasn’t returned to 1,000. Shares not yet purchased and production lines not yet halted were not priced separately today. The aggregate target is approximately 1,463. Market capitalization is approximately 1.16 trillion.
Timing is the first consideration. The CHIPS Act was signed in December 2024 and remains in effect until December 9. CFO Mark Murphy stated on September 30 that the company would increase returns to shareholders starting that day, with excess cash primarily allocated to share buybacks going forward. Approximately 22 billion remains under the current authorization.
Net cash at the end of the fiscal year is approximately 683 billion. This is according to the company’s own figures. The model is the second factor. UBS’s Arcuri assumes cumulative free cash flow of approximately 400 billion by 2028, with buybacks exceeding 30% of outstanding shares.
Cantor’s Muse projects free cash flow for the next eight quarters to exceed 333 billion. Assuming a 30% share cancellation with profits remaining unchanged, the stock price would rise by approximately 43% per share. This is an analyst’s calculation, not an officially announced figure. If market capitalization remains constant and half the shares are canceled, the price would reach over 2,100—provided that memory-related profits do not decline and the price-to-earnings ratio is not compressed.
The market capitalization has quadrupled in just over a year. Factories are the third issue. The Taoyuan union, with 2,258 members, authorized a strike with 88.3% support; however, no work stoppage has been called yet, as they are awaiting a response from the board. The Taichung union, with approximately 10,000 members, will hold further talks on October 22 and has not ruled out another vote. The union states that Taoyuan and Taichung combined account for more than 60% of global production.
A Reuters report in September noted that since no strike had been called, production remained unaffected. The workers’ demand is for bonuses equal to 15% of operating profit. The authorization for a share buyback remains in place, as does the authorization for a strike. As of October 28, neither side had fulfilled their commitments.
This is not investment advice.
#QQQ #STOCK #MU
$MU closed at 1,035.84 yesterday.
This is a three-part statement; please do not combine them into a single sentence.
The first part is the date. The CHIPS Act agreement was signed in December 2024 and is valid through December 9. CFO Mark Murphy stated on September 30 that the company would increase capital returns starting that day, and that excess cash would primarily be used for share buybacks going forward.
Approximately 22 billion remains under the current authorization. Net cash at the end of the fiscal year was approximately 683 billion. This is according to the company.
The second part is the model. UBS’s Arcuri assumes cumulative free cash flow of approximately 400 billion by 2028, with share buybacks exceeding 30% of outstanding shares. Cantor’s Muse projects free cash flow for the next eight quarters to exceed 333 billion.
With 30% of shares retired and profits remaining unchanged, earnings per share would rise by approximately 43%. This is based on analysts’ calculations, not announced figures. Assuming the market capitalization remains constant and half the shares are retired, the price would rise to over 2,100—which implies that memory profits will not decline and the P/E multiple will not be compressed. The current market capitalization is approximately 1.2 trillion, having more than quadrupled in one year. The aggregated target is approximately 1,463.
The third segment concerns the factories. The Taoyuan union, with 2,258 members, has authorized a strike with 88.3% support; however, they have not yet called for a work stoppage and are awaiting a response from the board of directors. The Taichung union, with approximately 10,000 members, will hold further talks on October 22 and has not ruled out another vote. The unions state that Taoyuan and Taichung together account for more than 60% of global production.
Reuters reported in September: Since no strike has been called, production has not been affected. The demand is for a bonus equal to 15% of operating profit. Today’s range is 1,020–1,080. Negotiations on 1,120 will only begin once the price breaks above 1,090; if it drops back to 1,000, the first to be priced out will be the shares not yet purchased and the production lines that haven’t yet halted.
#QQQ #STOCK #MU
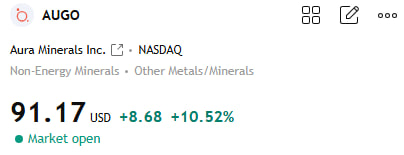
$AUGO closed at 82.49 yesterday. +11% (I wasn’t betting on 96, just 91—and as it turns out, it’s already there)
Aura’s six mines reported preliminary production of 95,557 gold-equivalent ounces, up 27% month-over-month and 29% year-over-year. On a constant-price basis, the increases were 26% and 25%. Sales totaled 93,742 ounces.
Production for the first nine months totaled 253,131 ounces. MSG saw an 85% increase month-over-month, Borborema a 60% increase, and Aranzazu a 39% increase. Minosa and Almas saw month-over-month declines. The company stated that production will continue to increase in the fourth quarter, and full-year guidance remains on track. These are preliminary production figures; the financial report is expected around November 5. The figures are reflected in the first half of the year.
Revenue was 718.6 million, up 104% year-over-year. Adjusted EBITDA was 440.5 million, up 135% year-over-year. Rolling revenue is approximately 1.3 billion, with net income of approximately 299 million and earnings per share of $3.57. P/E ratio is approximately 23x, with a forward P/E of about 11x. Market capitalization is approximately 7.5 billion.
Dividend is approximately $1.87. 52-week high is 110.32. Consensus target is approximately 102.
Today’s range: 84–91. A break above 92 is required before 96 can be considered;
Several stocks on the market have already been volatile since the early trading session today.
Stock Code: ****
Like and comment or send me a private message, and I’ll send you the full report directly.
Add my WhatsApp number (listed on my profile) to get the full information in advance.
Several stocks on the market have already been volatile since the early trading session today.
Stock Code: ****
Like and comment or send me a private message, and I’ll send you the full report directly.
Add my WhatsApp number (listed on my profile) to get the full information in advance.
$MU closed at 1,035.84 yesterday.
This is a three-part statement; please do not combine them into a single sentence.
The first part is the date. The CHIPS Act agreement was signed in December 2024 and is valid through December 9. CFO Mark Murphy stated on September 30 that the company would increase capital returns starting that day, and that excess cash would primarily be used for share buybacks going forward.
Approximately 22 billion remains under the current authorization. Net cash at the end of the fiscal year was approximately 683 billion. This is according to the company.
The second part is the model. UBS’s Arcuri assumes cumulative free cash flow of approximately 400 billion by 2028, with share buybacks exceeding 30% of outstanding shares. Cantor’s Muse projects free cash flow for the next eight quarters to exceed 333 billion.
With 30% of shares retired and profits remaining unchanged, earnings per share would rise by approximately 43%. This is based on analysts’ calculations, not announced figures. Assuming the market capitalization remains constant and half the shares are retired, the price would rise to over 2,100—which implies that memory profits will not decline and the P/E multiple will not be compressed. The current market capitalization is approximately 1.2 trillion, having more than quadrupled in one year. The aggregated target is approximately 1,463.
The third segment concerns the factories. The Taoyuan union, with 2,258 members, has authorized a strike with 88.3% support; however, they have not yet called for a work stoppage and are awaiting a response from the board of directors. The Taichung union, with approximately 10,000 members, will hold further talks on October 22 and has not ruled out another vote. The unions state that Taoyuan and Taichung together account for more than 60% of global production.
Reuters reported in September: Since no strike has been called, production has not been affected. The demand is for a bonus equal to 15% of operating profit. Today’s range is 1,020–1,080. Negotiations on 1,120 will only begin once the price breaks above 1,090; if it drops back to 1,000, the first to be priced out will be the shares not yet purchased and the production lines that haven’t yet halted.
#QQQ #STOCK #MU