Looking for value, focused on O&G, Mining and Shipping.
It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so
One thing that line leaves out: hedges. 8 MMbbl of 2027 oil is capped at a ~$84 average, and 2 MMbbl of collars top out at $85 exactly when 1H prices near $100. Above $85 you keep ~55c of each dollar.
I’ve seen some pretty bad takes on $KOS. Weak earnings were mainly cargo timing — being underlifted is actually a positive here since those barrels get sold into much higher Q4 prices. Loss is mark-to-market, cash flow is positive and the barrels haven't gone anywhere. If you don’t understand basics like barrels sold vs prod in an E&P, you probably shouldn’t own it 🙂
FCFE, i.e. after interest and the $110m of 2027 principal: ~$360m at the strip, 24% of the market cap, ~$0.61/share. Caveat: none of it is distributable — it all goes to debt — so don't count the yield and the deleveraging as two different returns.
My numbers, not guidance: Q4 at $110 Dated, 13 MMbbl of Ghana oil incl. 1 MMbbl of underlift catch-up, $400m capex, gas at $6.70/mcf. Capex is the soft one — no 2027 guidance yet
Ngl, I expected some feedback, for or against the thesis. That was the main reason I published it. Kinda get what @respeculator meant about wanting a sounding board and not getting the dialogue.
Been quiet here for a while. Back with a long one on Panoro $PEN.OL #PEN, which I bought after the Block G deal. H2-loaded liftings, Q4 cargoes into a physical market well above the screen, and a bond that decides the dividend.
@Ren558668020931 I bought in February before high oil prices because I already thought SP should be way higher. I think a fair price is above 35NOK as my article explains
Been quiet here for a while. Back with a long one on Panoro $PEN.OL #PEN, which I bought after the Block G deal. H2-loaded liftings, Q4 cargoes into a physical market well above the screen, and a bond that decides the dividend.
Been quiet here for a while. Back with a long one on Panoro $PEN.OL #PEN, which I bought after the Block G deal. H2-loaded liftings, Q4 cargoes into a physical market well above the screen, and a bond that decides the dividend.
The catches: the bond caps payouts near a 5% yield until 2028, Block G came with a big abandonment bill, and a run-off of today's 2P alone is worth a bit less than the share price. So the price pays almost nothing for Block G after 2040, the 2C or EG-23.
Equinor acquires 17.4% interest in PEL 90 (Namibia) from operator Chevron. QatarEnergy also 27% in PEL 90
Chevron's Kapana-1 well came in non-commercial in Jan '25 but the company confirmed Monday it will spud its 2nd PEL 90 well, Nabba-1X, before year-end
H/T @AndersSjastad
Deepwater E&P is a specialty of Equinor's and is worth the risk given the upside potential in my opinion $EQNR
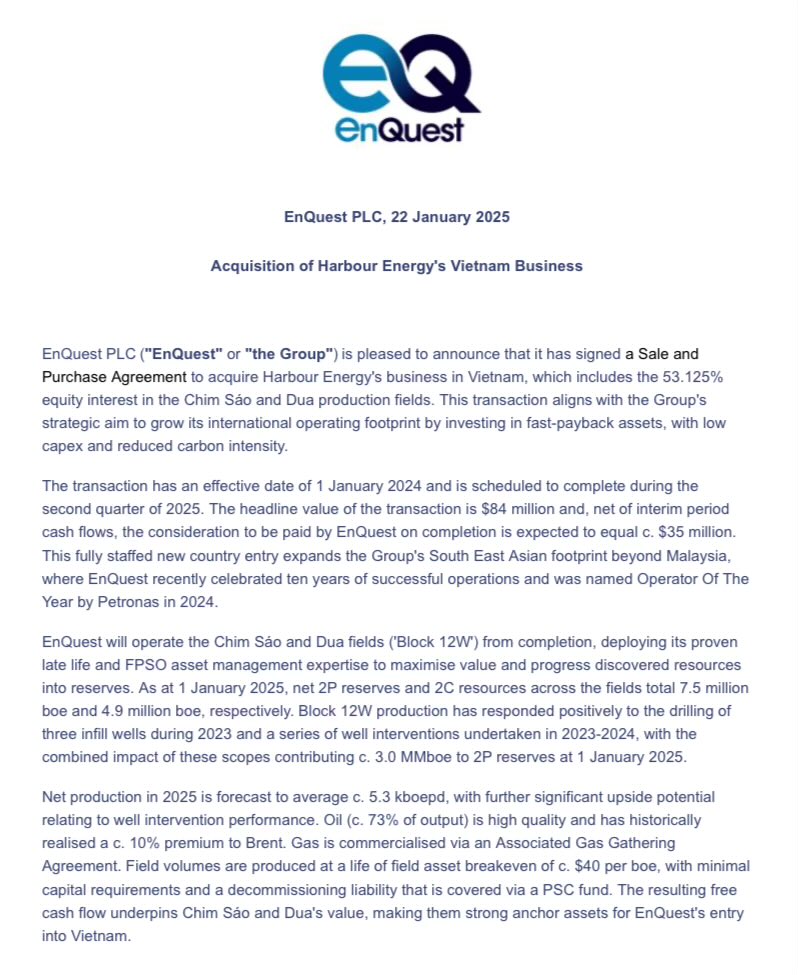
Nice move by EnQuest (never thought I would say that). Fair deal in APAC, that's where they should focus their business. Also positive for $HBR.L that they’re able to sell this in the end. #ENQ $ENQ.L