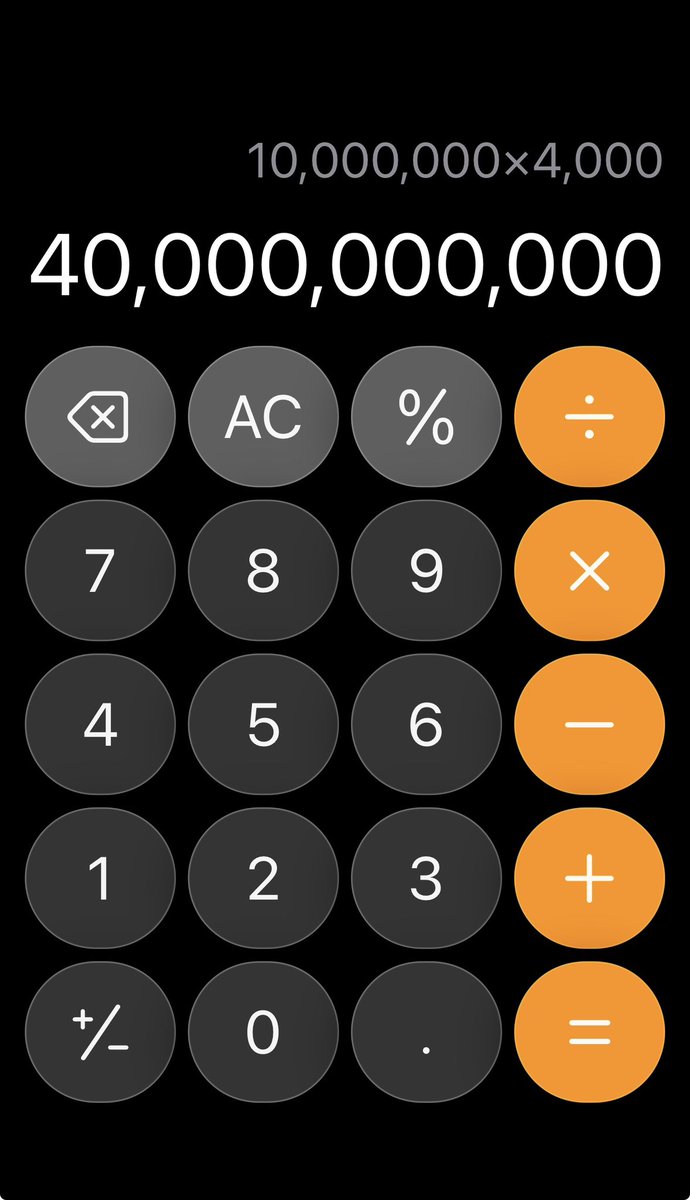$MMTLP Embarrassing. Won't go to a federal court but shoots off a useless PR to the White House.
Next Bridge wasn't negatively affected by the halt on the A series, they reported a clean exchange of shares below the issued count and never intends to trade. McCabe probably doesn't even know that the majority of the 2.6M shares rolled into his stack were likely settled for cash or like securities a long time ago.
He wants to sell those shorts shares directly. Hes already papered shareholders out of the money. Why they aren't lined up at the Nevada Secretary of State office is unbelievable. An organized group of shareholders holds the cards to end this and don't even know it.
.
The TRCH merger with MMAT RTO merger did not change the stock structure of TRCH. The ticker symbol changed. Brda and Atlas squeezed most out in the pump days before the merger.
Any residual shorts at the close in TRCH became short MMAT, not $MMTLP. Those shorts owed thd dividend and the VPA the first week looks like many squeezed out.
Once again, when a short is sold it can hurt price with volume. That pain stopped at the merger. They only effect of shorts on $MMTLP was 100% upside, every short and options contract had to buy to close.
@_TraderZero_ The answer is easy. You keep on conveniently overlooking it on purpose. Most of those shorts were carried through the merger from TRCH. Why do you even bother at this point? We know who you are. It just looks desperate. You need some more pocketchange, bum?
The market mechanics are real, they are autommated, and they will stop a naked short seller who has no intention of delievering shares T+1. This is exactly how a trade flows.
All trades flow through fiber on dedicated mainframe servers. The order is routed through a monitored prime broker short locate server. If shares are available the order is certifed by the bank then goes to the exchange. No locate, order is rejected at both the broker and exchange level. The order cannot make it to clearing without a borrow.
Every trade is cloned and sent through FINRA's SONAR system and analyzed. Any trade that looks slightly out of line is flagged. At clearing the NSCC becomes counter-party to the trade and the deliver obligation to the buyer is guaranteed, the selling broker now owes those shares to the NSCC. CNS clearing balances nightly. Imbalances are automatically traced and the selling brokers id is flagged.
The Market Makers and your Issuer are partners. The issuer pays the MM a fee to provide liiquidity in their stock. The "maker/taker" relationship is contractual, teh MM charges a fee and the issuer gets a rebate based on mutually agreed upon metrics. There is no incentive for a market maker to drive share price down, you don't shit where you eat.
QTC and Dark Pool trades have a mandatory automated 10 second cap on reporting to the lit tape. The trades are routeed through FINRA's TRF/ORF servers to flag suspect trades, and all dark pool trades are live monitored to the nanosecond in the CAT pipe.
The system didn't fuck you, you were preyed upon by scammers who take advantage of retail greed and inexperience to bring volume to a ticker they already own, then sell into you while telling you to buy and hold.
The SEC needs to clamp down on social media pumpers and restrict trading on penny stocks for people with less than one year of experience.
✌️TZ
$MMTLP
1, Do gobal crime syndicates exist? Of course they do.
2. Does a global crime syndicate zero in on an unsolicited OTC ticker that's a preferred share dividend with a bagged retail overhang equal to 100% of the float and traded with a 52 week average share price at $1.47? They would be the dumbest criminal cabal in history. Here's why:
THe question becomes - Why would a sophisticated internationnal short seller choose an unusually capital-intensive sub-$5 OTC illegal naked short when substantially more capital-efficient legal bearish exposure is available on a national exchange?
To make it apples-to-apples, let's say both tickers was to lose 66% (1.47 -->.50 and $30 to $10) and we give each short the same $1.47B initial notional exposure and the same 66% decline over six months.
Both are sold naked (which could never happen) except $MMTLP trades at $1.47 and the Nasdaq ticker trades at $30. The syndicate has the same amount of cash to trade with, so all in $1.47 billion dollars at stake.
Both positions sell $1.47 billion worth of stock short:
$1.47 stock: 1 billion shares × $1.47 = $1.47B
$30 stock: 49 million shares × $30 = $1.47B
Now both fall 66%:
$1.47 → about $0.50
$30 → $10.20
Then:
OTC: $1.47B sold − ~$500M to close = ~$970M profit
$30 stock: $1.47B sold − ~$500M to close = ~$970M profit
The simple point
The billion-share count is irrelevant to the economic return.
A 66% price decline on a $1.47 billion short position produces approximately $970 million of gross profit, whether that position consists of:
1 billion shares at $1.47 or 49 million shares at $30.
Say the get completely wrecked. Keeping the same $1.47B short notional for both and assuming each stock rises 700%:
$1.47 → $11.76
$30 → $240
Price after +700%
MMTLP $11.76
NYSE$240
Cost to buy back = Same cost$11.76B
Original proceeds = Same amount $1.47B
Loss= Same amount $10.29B
Bottom line -->> Each loses $10.29 BILLION.
McCabe and Company are too stupid to understand that while a billion shares sounds enormous because the stock price is tiny, the relevant number is the dollar value of the short position, not the share count.
The starting share price and share count make zero difference when the initial dollar exposure and percentage price move are identical.
Now the why they wouldn't do it part: The naked short seller is already in a max enforcement risk situation simply due to size exposure, a $1.47 billion/1 billlion share short in a single OTC ticker with 165M shares isn't a just a risky trade, it would be the largest short OI in recorded history. For comparison:
Current historical database leader: ~329 million shares short in $PLUG Power
$ONDS as on 10/15/26 reached 254 million shares short
$GME 2020–21 extreme was only about 69–71 million shares short, with SI at 140% of its public float.
That would put $MMTLP at 1.4x all three of those combined and 3x bigger than the highest SI ever. Every regulator on earth would want to know who entered that position. This is why a sophisticated broker playing this game is going to find a highly liquid listed name at a high share price, at $30, 49M shares can hide in a high float high liquidity ticker. Much less risk for the same profit and upside loss. You would be caught the day the orders hit the tape. (They also wouldn't be dumb enough to close all in on the last day of trading for fucks sake)
Even granting the extreme premise that a broker-dealer could sell 1 billion nonexistent shares at $1.47, avoid a prime broker borrow expense, prevent the position from producing a persistent FTD under CNS clearing, and later acquire the shares for $0.50 in a stock with an ATH volume under 14 milllion shares, the maximum headline spread is about $970 million. The relevant question is what capital, clearing exposure, financing, regulatory exposure, and balance-sheet capacity had to be committed to earn that $970 million, when you could legally short a $30 stock with nearly no regulatory scrutiny and make the same if not more profit?
They naked shorted a billion shares! sounds dramatic, but when you look at it from a non-biased purely financial perspective it sounds pretty "fucking retarded" doesn't it?
✌️TZ
Forget all of that bias. Answer this question: What was your personal reason for buying the stock? What was the date you bought the stock and at what price? Lastly, what was your unrealized loss when the stock stopped trading?
Making a bad trade based on information you read on social media and your decision to hold the stock despite the price trend and date the dividend would lose its underlying value is your problem. The SEC has no obligation to resolve that problem. Your choice to make a financial decision based on social media posts was irresponsible. You fucked up.
Yesterday in $MMTLP news -
Greg McCabe told @cvpayne that an international German cabal, in coordination with a criminal American broker network, tied up billions of dollars in cash margin deposits to sell one billion shares short with no borrow, through a US prime broker, quoted by an OTC broker, with no liquidity to support the offer. Gregh says that this was not done on a large cap exchange listed ticker with supporting volume, but the crime syndicate chose the most visible ticker possible; an unsolicited penny ticker that was cleared CNS and only traded 265 million shares in total at an average share price of $2.25/share.
Greg also says that:
- FINRA, SEC, DTCC, NSCC, IRS, TREASURY, FEDERAL RESERVE, OTC MARKETS, all in on it.
- The U3 Halt stopped those German criminals from closing positions on 12/9, when they would have already gained the NBH shares and lost the clearing window.
- @palikaras can prove this
-Equiniti issued 165M NBH shares on 12/15 and had to return 52,000 shares because the DTC net holding was short the float not over the float and all street name holding was accounted for.
-There was no settlement of the naked short sales, therefore, no cash or securities changed hands, the criminals never received a single penny from this crime.
-There was no catastrophic margin call at any bank
- The DTC margin pool was not depleted and the NSCC as contra-party said nothing about the CNS daily imbalance that would have caused. https://t.co/D0PGRrEz4E
Which one of those things was responsible for the dry hole that just slapped another $10 million liability on the books, McCabe? Which one of those put $173M accumulated deficit on the books McCabe?
Your stock wasn't shorted, the dividend that was exchanged for your stock was shorted then cancelled and your stock has never traded. You have diluted share holders with 100 million shares. Explain how any shorting was negative for you. You can't. Because it is positive for you.
When are you going to tell your shareholders that you aren't chasing a billion naked shorts? When will they find out that you are trying to find a way to access the 2.6 million real shorts trapped with the longs without live trading?
Why are you doing that?
1. Because the shorts in your stack are not a liability, the $MMTLP Army Longs are the liability. The short sale hit MMTLP tape a long time ago, it did not affect your company at all.
2. On 12/8 the U3 HALT trapped 100% buyers holding short and today they are a guaranteed direct to NBH buyer if you can find a way to make them close.
3. YES - The $MMTLP shareholders ARE the liability. They are loud, cost money to maintain, expose McCabe to all kinds of problems, and if the stock started trading, they would sell hard into those shorts you desperately want to sell shares directly to.
4. Pretending that you are on their side keeps them from running to Nevada and removing you as Chairman.
This can't last forever Gregory. Keep it up though, this German cabal theory was hilarious.
@cvpayne is an embarrassment to financial journalism.
To be or not to be in ChatGPT "Your own voice":
Do I keep going, or do I end it?
That’s the question. Is it better to take everything life throws at you and keep your mouth shut, or finally stand up to it and risk what comes next?
Death sounds simple enough. You sleep. The pain stops. Every hit you took, every betrayal, every damn thing you carried—gone.
But here’s the problem: we don’t know what comes after.
If death is a sleep, what do we dream? That’s the part nobody can answer, and it’s enough to make you stop and think.
Because honestly, who would put up with all of this if there were an easy way out? The abuse, the arrogance, the people who get ahead by stepping on everyone else, the love that goes nowhere, the delays, the disrespect, and the endless parade of people in power who haven’t earned it?
We put up with it because the alternative is unknown. Nobody comes back with a report.
So we think. And then we think some more. We run through every possible outcome until the decision we were ready to make starts looking a lot less certain.
And that’s how the thinking itself can stop us from doing anything at all.
The stock traded 28 million shares from $9 to $2.9 on the last week. Exit liquidity was high, idiots were FOMO buying shares on a half cent spread. OTC is a broker quote based market. Brokers buy your shares then sell them to another broker and scrape the profit. A broker wouldn't touch $4000 quote on top of a liquid, declining $9 to $3 book. The markets don't work like that. Use common sense. Plenty of shares to buy at $7 but fuck that, im gonna buy this guy's shares for 4 grand a pop?
On an exchange? The bid is NBBO, every order fills on that tape. A $4,000 ask never hits the tape.
NSCC / CNS cleared $MMTLP trades. Can't naked short size. That's why every broker ever busted for a naked scheme over the last 40 years tried to locate before settlement so they wouldn't get caught.
Market mechanics matter. You cant pretend they don't exist so your fantasy works.
If Anson Funds had to cover their naked short position of 10M shares of #MMTLP at a quoted share price of $4000/share as some shares reportedly were sold right up till the U3 Halt, they would have had netted a LOSS of $40B.
That would have bankrupted them completely.
They couldn’t have that.
They need to keep their coffers full of money to pay off their industry friends in the SEC and FINRA to look the other way. 🤬
$DRIO has a developing 1–3 day long bounce setup, but I wouldn’t chase Friday’s close.
The buying response is encouraging; volume and liquidity still need to prove the trade.
Status: DEVELOPING / CONDITIONAL. Structure: oversold bounce.
Friday, October 23: closed $3.77, +10.56%, versus $3.41 previously. Regular-session range was $3.27–$3.77, with 85,438 shares traded; the reported after-hours print was $3.71. These figures agree between Stock Analysis and WSJ; another quote feed differed on the intraday extremes, so I’m using the corroborated daily bars.
What the VPA says
Session
Low
Close
Volume
My interpretation
Oct. 20
$3.85
$4.08
132,562
Selling accelerates
Oct. 21
$3.13
$3.68
265,793
Heavy selling, substantial recovery off the low
Oct. 22
$3.01
$3.41
198,124
New low, another rejection of lower prices
Oct. 23
$3.27
$3.77
85,438
Higher low; closes at the high
Daily-bar source.
My read: possible stopping action, followed by an initial demand response.
Wednesday and Thursday’s lower wicks suggest buyers met the selling. Friday then advanced on 57% less volume than Thursday—consistent with reduced selling pressure, but insufficient to establish accumulation.
Friday’s volume was 1.23× the preceding 10-session average of 69,420, below the 1.5× confirmation threshold. The order-flow proxy suggests possible absorption/exhaustion, not confirmed aggressive accumulation. Daily bars cannot identify who bought.
The conditional trade I’d consider
The important hurdle is $3.85, Tuesday’s broken low. Clearing Friday’s high alone leaves that resistance immediately overhead.
Item
Proposed rule
Trigger
A 15-minute close above $3.85, then a retest holding that level
Entry
$3.86, only after the hold and volume confirmation
Stop
$3.64
First resistance / trim
$4.08 — 1.0R
Second target
$4.20 — 1.55R
Stretch target
$4.49 — 2.86R
Invalidation
Failed reclaim followed by loss of $3.67; exit by the planned stop
Time stop
Reassess if there is no continuation within two sessions
These are proposed execution rules, not an active signal. Require expanding breakout volume and at least 1.5× normal same-time volume on your platform. A completed session above roughly 104,000 shares would exceed 1.5× the retrieved prior-10-day average; that full-day figure is not an intraday pace measure.
The first two targets offer modest reward relative to risk. The trade needs room toward $4.49 to become attractive. If it gaps substantially above the entry, recalculate rather than chase.
Context that affects conviction
Relative strength: Friday outperformed SPY and healthcare, but DRIO still lost 21.8% for the week, versus approximately −0.4% for SPY and +1.5% for XLV. SPY’s recent daily structure is weakening. This remains a countertrend bounce.
Catalyst: I found the October 6 Aon-analysis announcement, but no verified fresh announcement explaining Friday’s rebound.
6ix
Supply risk: July’s SEC prospectus disclosed common shares, immediately exercisable pre-funded warrants, and a $20 million ATM facility. That establishes dilution capacity—not proof of selling during this decline.
$DRIO Prospectus Summary
Liquidity: Only about $322,000 of turnover using close × volume Friday. Small limit orders matter here; a stop price does not guarantee the fill.
Current score: 54/100, C — volume 16/25, structure 16/25, trigger 10/20, catalyst 4/15, liquidity 8/15.
Confidence: 0.78 in the setup assessment, not a win probability. Intraday confirmation and executable spreads remain unverified.
Not trading advice 😉
Do the Due
✌️TZ
$MMTLP Since this is a common misunderstanding and the community thinks this was a bad thing for years, I am posting the answer broadly.
The TRCH shares 2:1 reverse split before the ticker symbol was changed. TRCH shares on loan (15,309,824) were converted to a MMAT shares on loan (7,654,912).
The 2;1 ratio in round numbers is 100 TRCH became 50 MMAT. The A series dividend was 1:1 with the legacy TRCH shares and was a separate obligation - so they had to Deliver 2 preferred-share dividends to the lender when you return 1 MMAT share to cover.
Here is the part the morons can't figure out: TRCH shares were sold short into TRCH volume pre-merger. Any price degradation caused by those shares being sold short into the market already happened pre-merger. The carried over obligations as $MMAT shares and the tacked-on A series dividend shares, later $MMTLP shares, became guaranteed buy side commitments when they were closed, commons and options. The only influence on price for both securities was upside buy pressure.
The chart shows the first trading day opened at .10 cents and the day 2 peak was $3.20 on 11.2 million shares traded, the second highest volume day behind the 12/8 final day it traded. That's a 3100% two-day gain.
A squeeze without the lemon is what I call it when I am pretending to be some kind of analyst, and a fucking loser tells me to look at the whole picture.
You should stop listening to the people who got bagged on a textbook slow burn short squeeze trade.
@_TraderZero_ How about before MMTLP started trading? How many shorts carried over? If you're gonna pretend to be some type of analyst, then look at the whole picture. Considering TRCH traded for 7 and a half years before merging with MMAT, it would seem that time period might be worth a 👀🖕
It amazes me how this topic hasn't died yet. The available borrow figure is a live inventory number driven by both demand (borrowing) and independent supply decisions by lenders. It is not a closed, fixed pool. How difficult is this to understand:
Shares available to borrow comes from inventory supplied by lenders (mainly institutions such as mutual funds, ETFs, pension funds, and some retail accounts that opt into fully-paid lending programs). Brokers and data providers (Interactive Brokers, Ortex, etc.) report a snapshot of currently unborrowed shares from the lenders they have access to.
Lenders can add or remove shares from the lendable pool at any time, based on their own policies, inventory, fee thresholds, or portfolio decisions. This is independent of lit-market trading volume. When someone borrows shares (primarily for short selling, but also for market-making, settlement, hedging, or other uses), those shares leave the available pool until returned. When a short covers, the shares return to the pool and become available again. Once shorted shares are sold, the new buyer can potentially lend them again (this is part of why short interest can exceed the float).
"The truth the community doesn’t want to admit actually can be calculated by an Actuarist. If a billion shares were sold naked into that reported tape, that would be 3.97 times every share printed in the company’s cited period. Even if you hand Greg McCabe every trade in that dataset as a naked short sale, he is still 748,023,204 shares short of his number. A naked short sale needs a fully clothed buyer, Gregory. A billion shares sold short cannot fit inside 251,976,796 reported shares traded." - TZ $MMTLP
"A clearing failure is a specific obligation between identifiable parties. NSCC’s Continuous Net Settlement system nets participating clearing members’ obligations by security, marks positions to market, and carries unresolved net positions into the next processing cycle. So if you are going to stand behind a billion naked short allegation you must reconcile the systemic clearing failure that didn't happen. @laralogan asked the wrong question. She should have asked Which clearing member could not deliver?, "What did the buyer’s broker receive?", Which loan was missing?, Which accounts failed to reconcile? What remained unsettled, and on what date? Naming Goldman, Schwab or Fidelity is not a substitute for identifying the obligation. A settlement claim or lack thereof needs to be addressed for your naked short theory to be valid." - TZ $MMTLP
"McCabe said the market is about supply and demand, and he’s right. There is nowhere near a billion shares of reported buying in the dataset his own company cited. McCabe can see this chart. Pushing a billion naked as the CEO of a company with thousands of wrecked shareholders who believe it is possible is irresponsible without producing the work. People who are ruined financially got to hear a multimillionaire repeat a billion-share naked-short scheme. Logan didn’t press him for the reconciliation. She was more interested in how much pain and suffering he personally had endured." - TZ $MMTLP