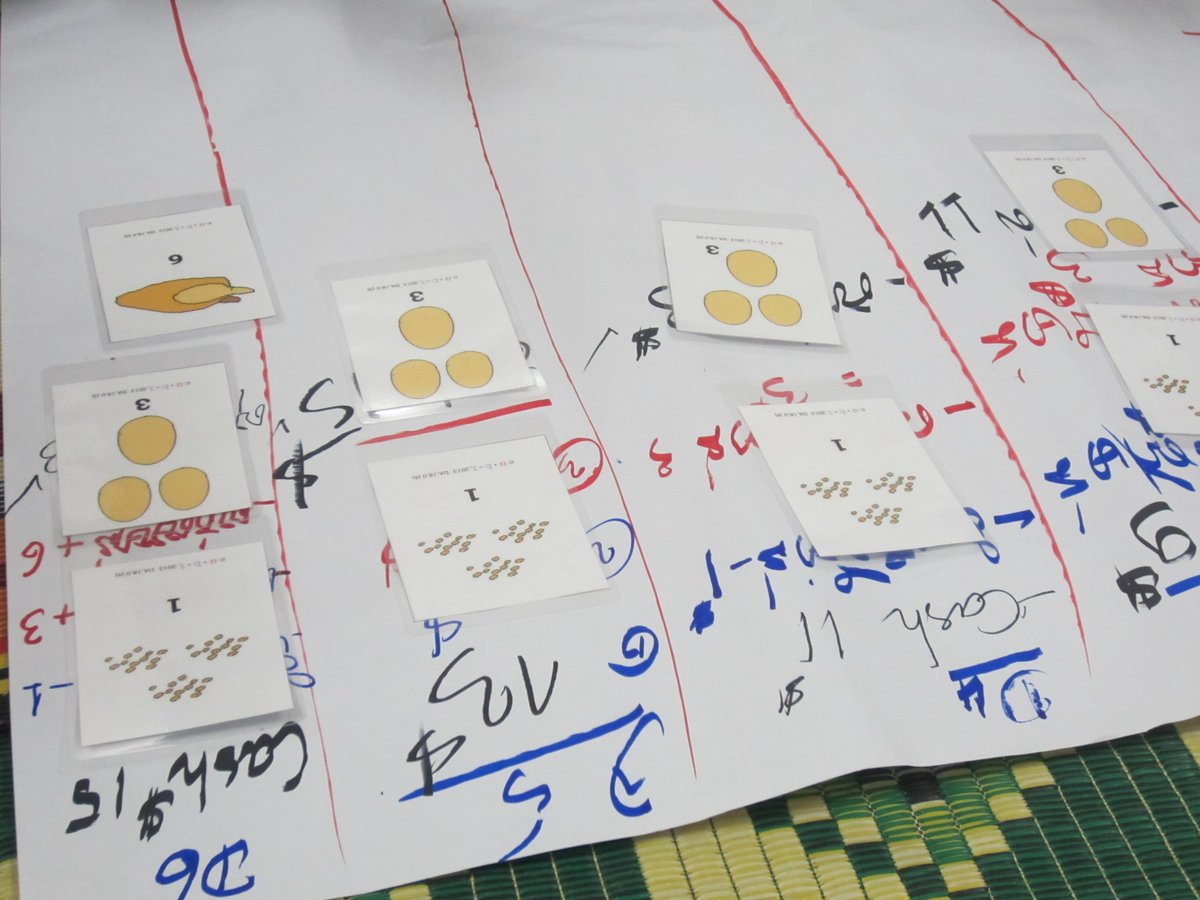
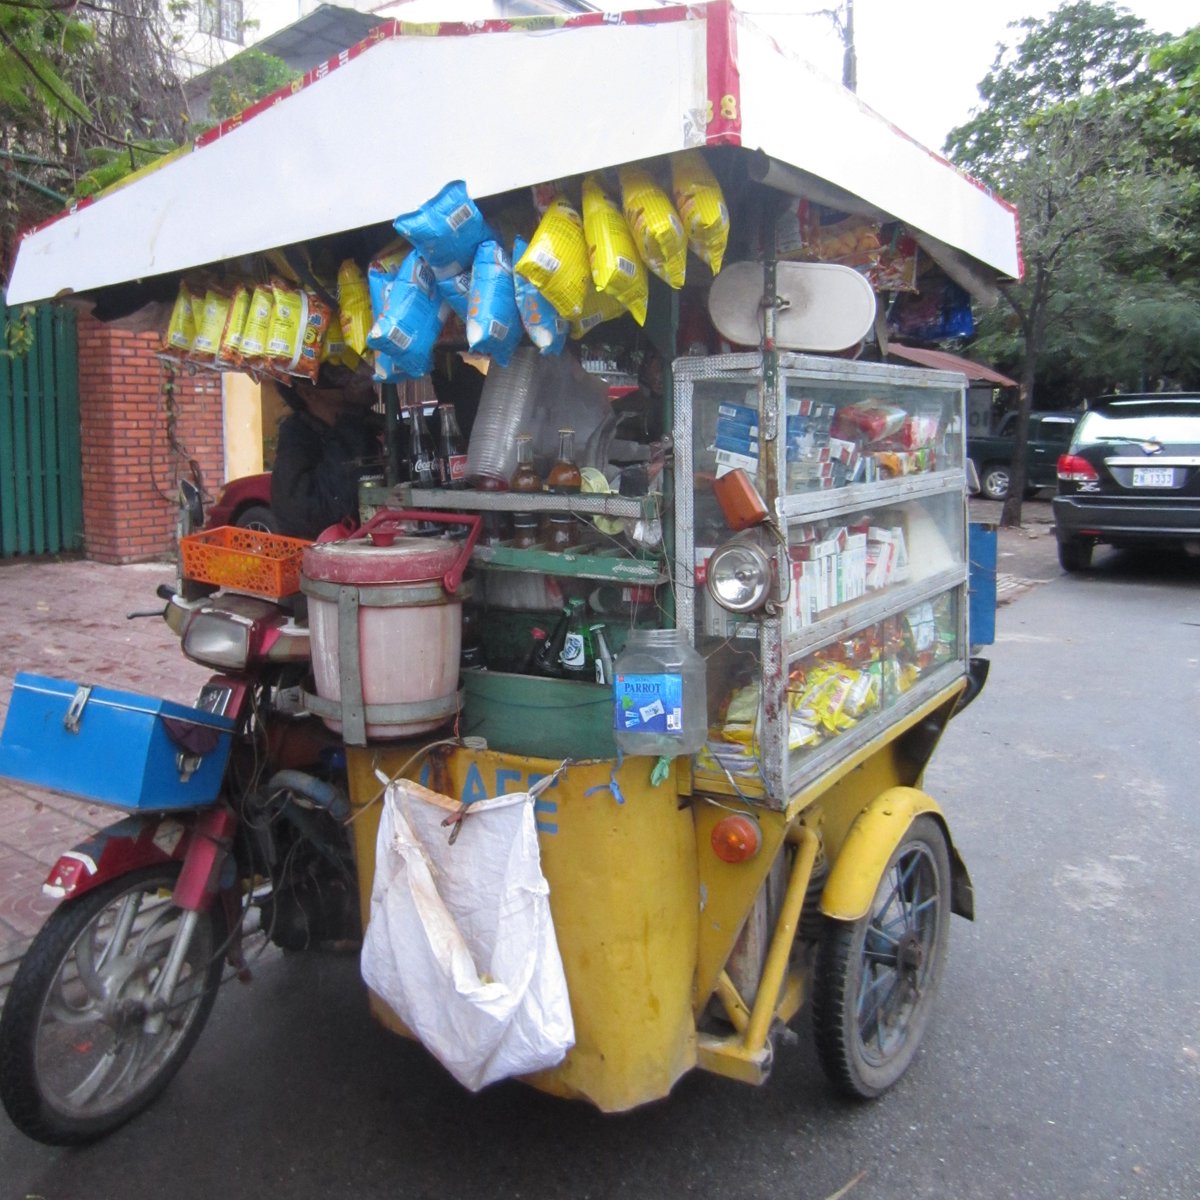
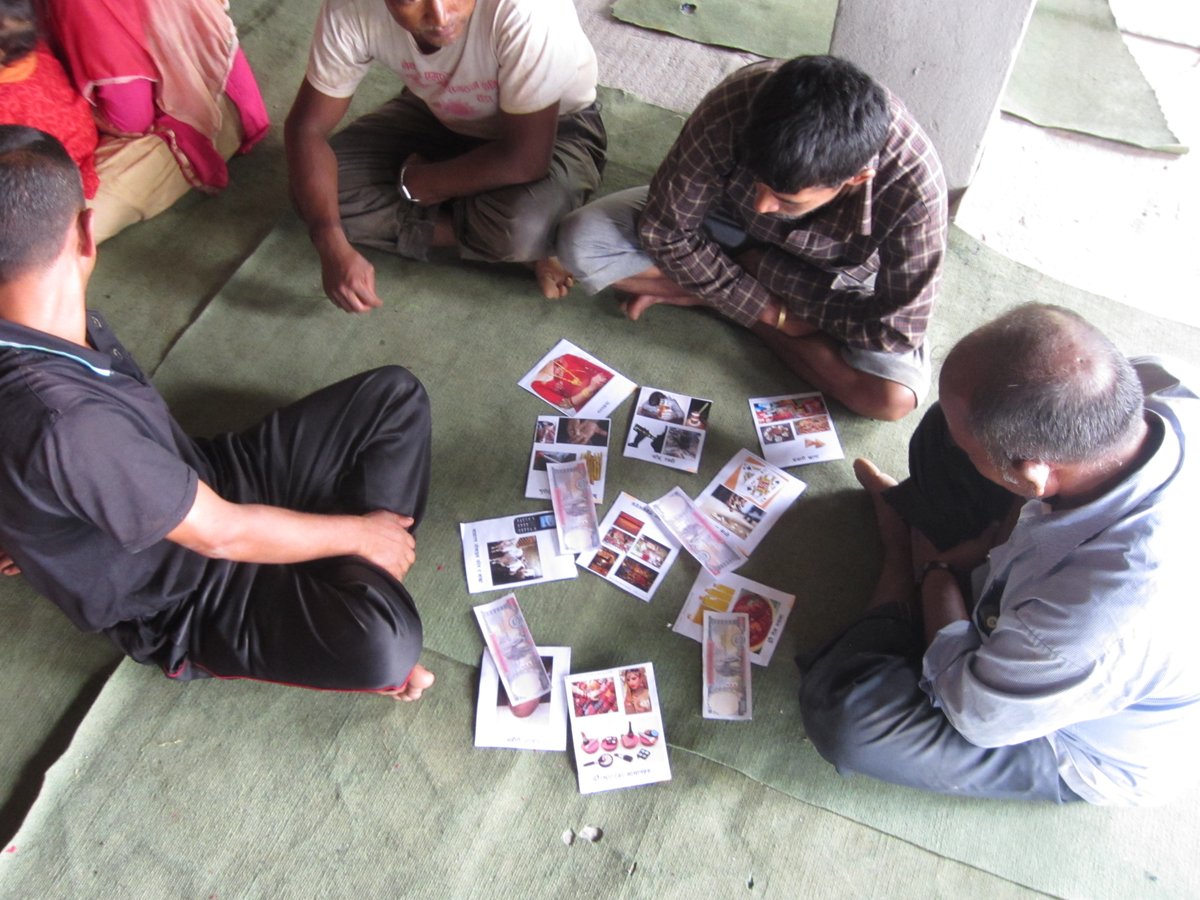
In 20 years, the world has changed: informal shops in Laos now accept QR code payments, all tuk-tuk drivers have smartphones, and domestic workers in Hong Kong are interested in investing in cryptocurrencies... Yet one thing hasn't changed: household debt. #FinancialEducation
#financialeducation programmes, which frame money management as an individual responsibility, are unable to provide adequate solutions to societal expenses like wedding, funerals... despite their significant impact on family finances. Let alone... expenses linked to corruption.
I was once contacted by a volunteer about to leave for Indonesia to lead an entrepreneurship training programme. What if the organisation create market opportunities for this community, or gave the amount (plane ticket, hotel.) to these women + let them decide what to do with it?
Generating income always involves generating expenses. We train a community to spend less + save, and another programme encourages the same community to create a business, i.e. to spend. Finance is not a science, but a network of transactions. #FinancialEducation must be social.
It is the trainers' ability to adapt #financialeducation to the specific problems of their participants and their empathy that sets trainers apart. There is no one-size-fits-all and universal approach to financial education.
Funders often ask us to develop financial education programmes for women only although interviews indicate women lack decision-making power. It isn't a problem of knowledge, but of power dynamics. Why not offer training for men, and then for couples? #FinancialEducation
'Dissaving' (using one's savings) is never included in #FinancialEducation. Simulations show constantly growing nest egg. The underlying message: anyone who can't grow their savings isn't managing their money well. Does financial education contribute to financial exclusion?
A young woman wasn't convinced by my budgeting advice. She started listing her expenses down to the number of bars of soap. Of course, she managed her expenses. #Financialeducation never replaces a living income. Those struggling have more to teach us about money.
On Int'l Women's Day 2008, Lehman Brothers HK invited me to give a speech on financial literacy. At the end, some executives confided in me about their stress related to their debt. #FinancialEducation is funded by the financial sector and target low-income people. Is that logic?
At the end of a TOT workshop, a participant stood up and said: Thank you for teaching me to be stingy. I’ll stop going out with my friends and I’ll save. What if all ‘financially educated’ people did the same? What impact would it have? What is the goal of #financialeducation
Once, in Cambodia, one participant to our training took our lessons so much to heart that she saved money and was lending those savings to her neighbours and friends with high interest. Can we become financial literate only at the expense of the others’ financial illiteracy?
20 years! In November 2005, I founded a+b=3 in Hong Kong. Our training programmes have directly impacted 6,000 people and around 80,000 through the trainers we've trained to deliver our workshops. These 20 years have deeply challenged my knowledge and assumptions about finance.
📣Big news! Positive Money has a fresh new look and a brand new website!
We’ve grown and evolved since our start in 2010 - with offices now in the EU, UK, and US, we’ve decided to refresh our international brand.
Formation avec des partenaires (bénéficiaires) de SAHI (ATIA) sur comment épargner pour des dépenses annuelles avec un revenu journalier : https://t.co/Dgro95VPnO
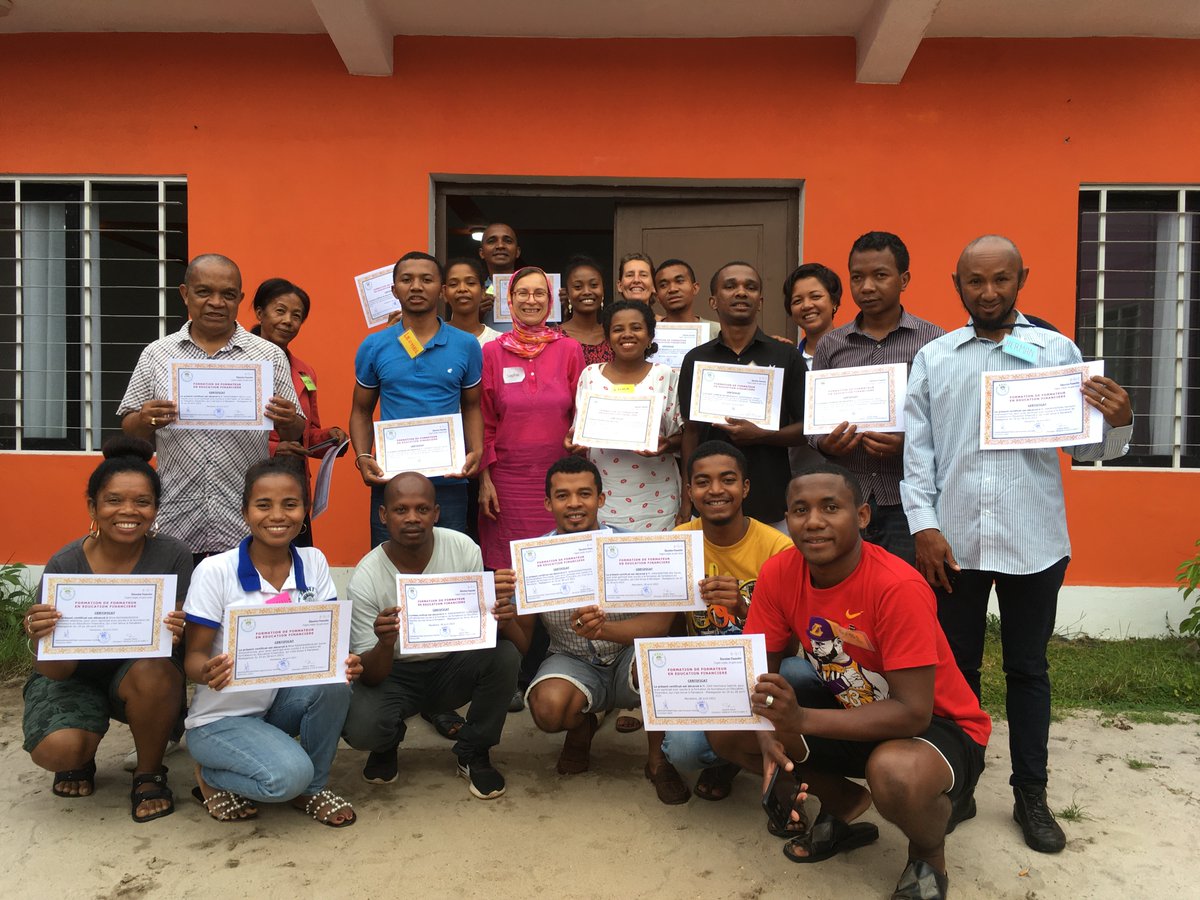
Dernier jour de l'atelier de formation de formateurs de SAHI (ATIA Groupe Inter Aide). Les participants ont pu animer des exemples de formation avec de vrais bénéficiaires.
https://t.co/dLwUvwqqii
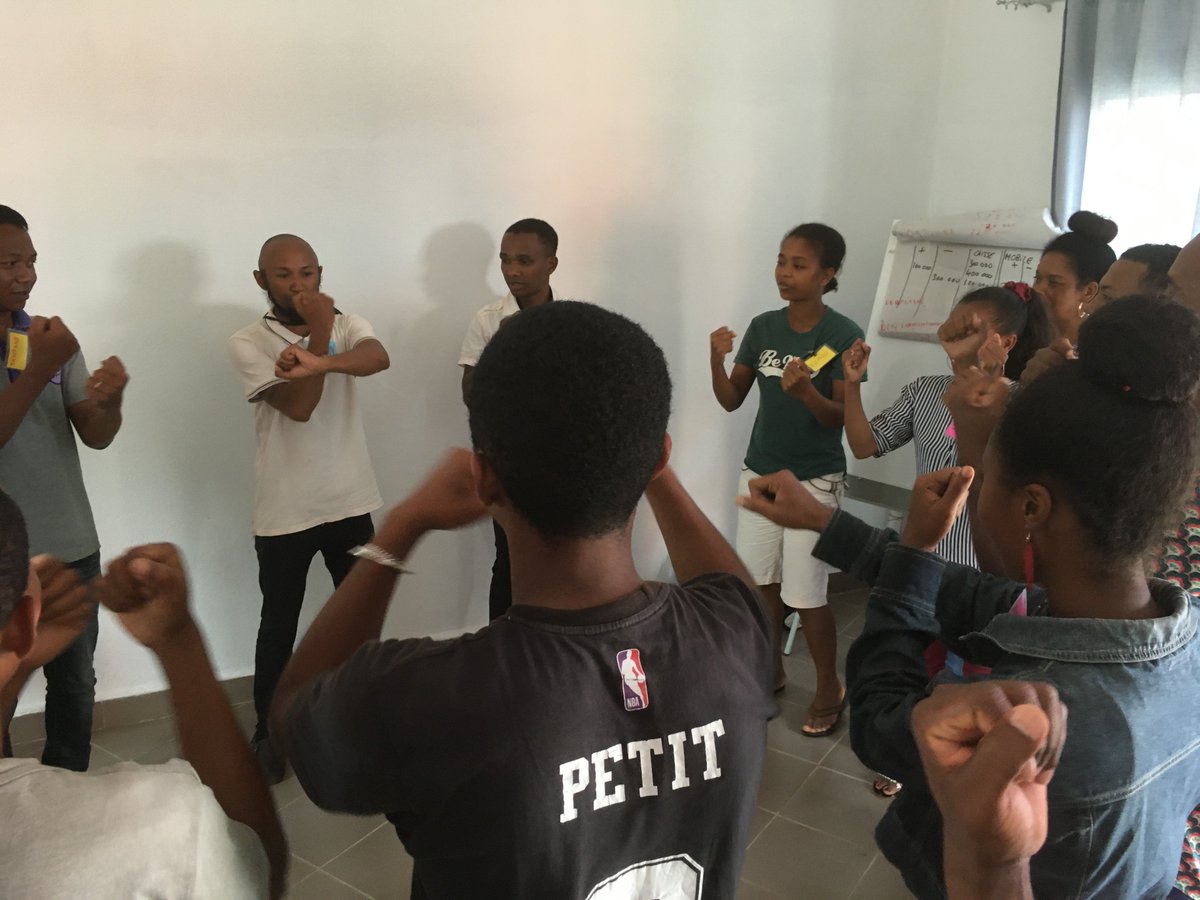
On passe aux choses sérieuses ! Les participants ont commencé à créer des exemples de formation et les animer. Suite demain pour les 19 participants de la formation organisée par SAHI, partenaire à Manakara (Madagascar) d'ATIA Groupe Inter Aide https://t.co/IR9J1fmm4J