If you’re an investor, looking for strategies that give good returns
Its for you.
STOP SEARCHING ✋️
Don't bet on strategy or backtest or even live data.
Bet on the person running the same thing from past 2years generating good risk adjusted returns. 💯
#StockMarketTips
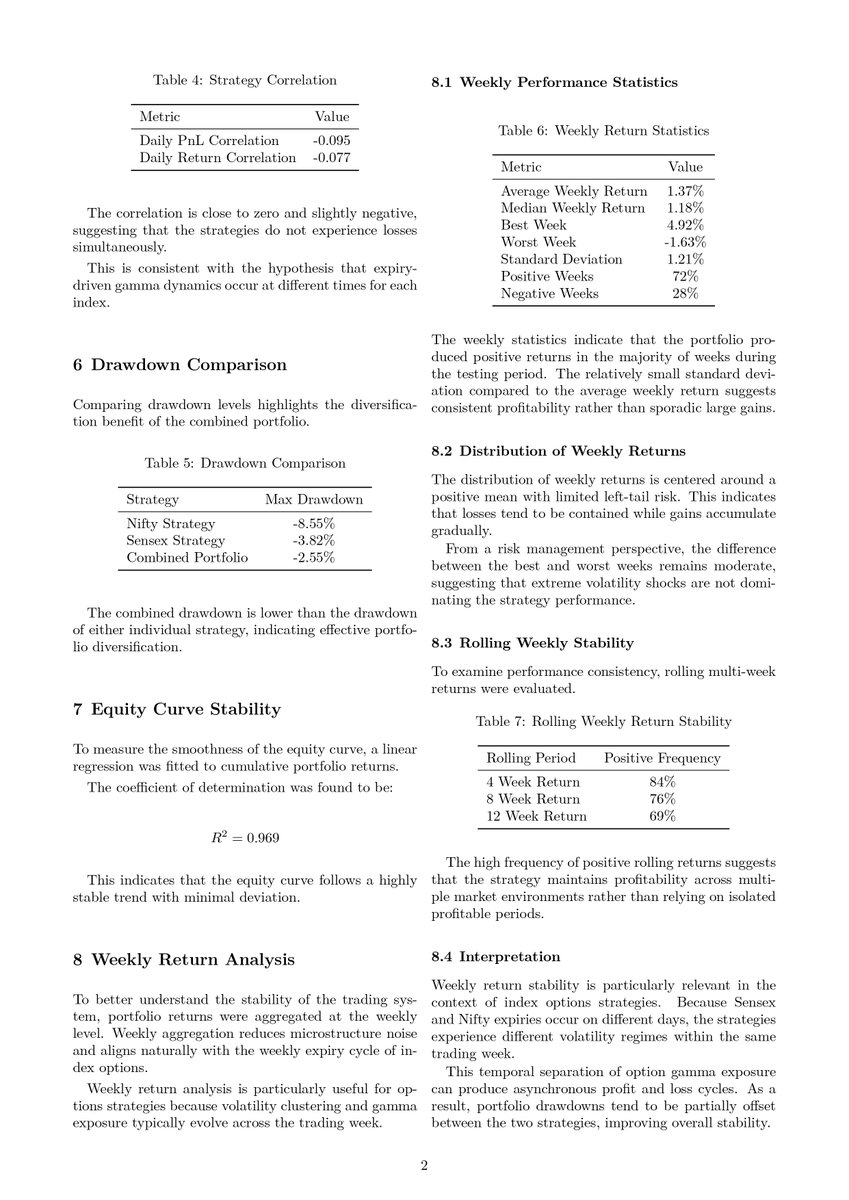
A latest (06 OCT 25 to 12 MAR 26) portfolio backtest combining #Nifty50 and #Sensex weekly expiry options strategies produced the following performance profile:
Capital Allocation
Total Capital: ₹1 Crore
Nifty Strategy: ₹50 lakh
Sensex Strategy: ₹50 lakh
Performance
Total Return: 35.81%
Net Profit: ₹35,81,068
Risk Metrics
Maximum Drawdown: -2.55%
Annualized Volatility: 10.53%
Sharpe Ratio: 4.64
Sortino Ratio: 8.96
Calmar Ratio: 40.72
For Business deals feel free to Contact [email protected] or dm on LinkedIn itself.
#AlgoTrading #OptionsTrading #QuantitativeTrading
Okay. I mostly work at a low level. If I can say, these would be
1. Concept of Abstraction
2. Memory safety
3. Manual Memory Management and why it even helps
4. Why it is called Portal assembly
5. Struct of Array vs Arrays of Struct
7. Direct system call
8. Bitwise operations
Lastly you can cover c vs rust