Merci à Fabien Labrousse et à VidéoBourse pour cet échange et pour le travail réalisé sur la vidéo.
J’ai eu plaisir à y présenter The Atomic Investor, mon parcours sur les marchés de l’énergie et la manière dont j’analyse l’uranium et les métaux critiques.
🍿 L'entretien complet (1h09) avec @adri_relli est à retrouver sur VideoBourse : https://t.co/DKkFqZUk3D
📌Au programme :
• La grille A.T.O.M.I.C. appliquée à l'énergie
• Cas pratiques : $UEC et Energy Fuels
• Sizing, timing & gestion du risque
• Marché de l'uranium : spot vs long terme
Breakdown of the large categories:
1. Mortgage Debt: +$77 billion to $12.52 trillion
2. Auto Loans: +$10 billion to $1.63 trillion
3. Student Loans: -$10 billion to $1.59 trillion
4. Credit Card Debt: +$27 billion to $1.14 trillion
This comes after US households have depleted over $2.3 TRILLION of excess savings since 2021.
At the same time, the credit card debt reached $1.06 trillion in July, just $3 billion below the all-time record.
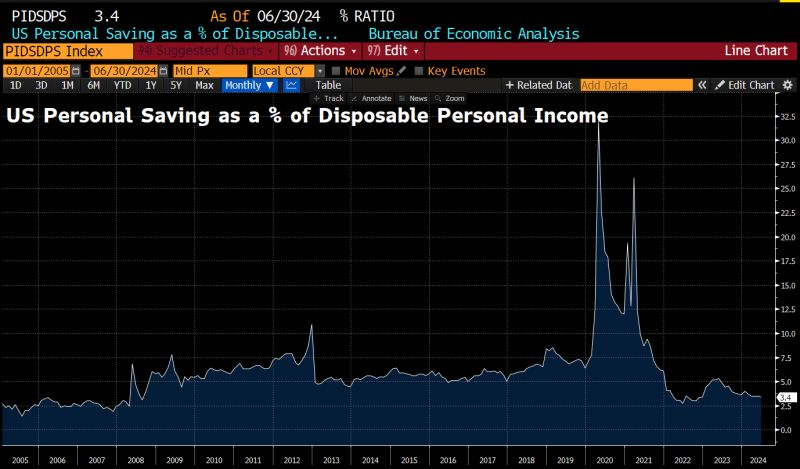
The US personal saving rate declined from 3.5% in May to 3.4% in June, the lowest since December 2022. By comparison, in May 2023, the saving rate was 5.3%.
Excluding 2022, the savings rate sits at its lowest level since the 2008 Financial Crisis.
S&P 500 futures are now trading at new lows, down 3.5% on the day and NASDAQ 100 Futures are also down more -5%, set for the biggest opening drop in more than four years.
The US 2y -10y yield curve that has been inverted for two years is close to flipping. 2y yields (-16bps) are a whisker away from falling below those on 10y for the first time since July 2022.
Bond markets are now pricing-in a 60% chance of an EMERGENCY INTEREST RATE CUT within 1 week. This would mark the first emergency interest rate cut since March 2020 during the pandemic.
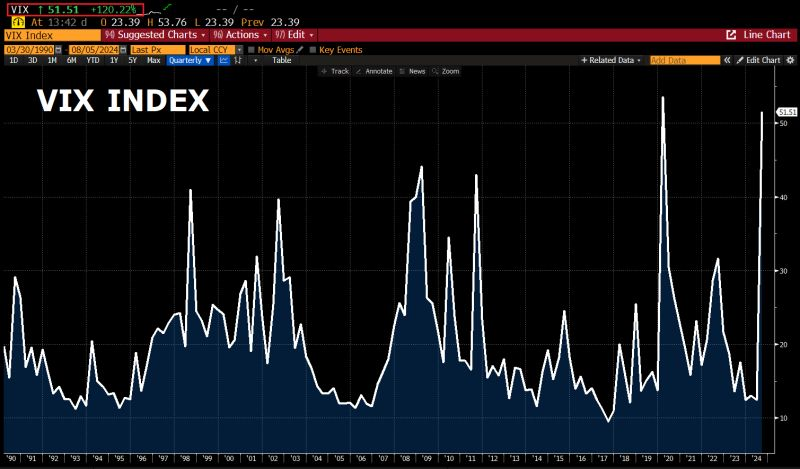
Since July 1st, the VIX is now UP over 330% and trading at March 2020 levels. The last time volatility was this high, the global economy was heading to a complete shutdown.
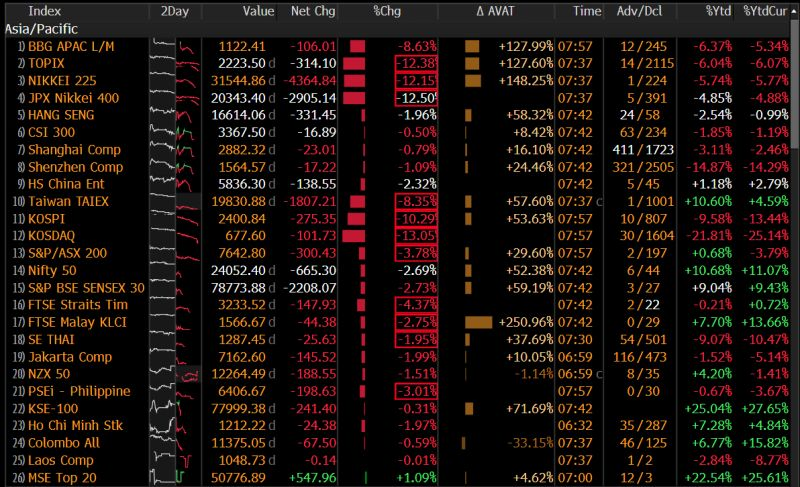
🇰🇷South Korean shares fell for a second straight session on Monday, with trading curbs activated for the first time in four years, as risk appetite dampened across global financial markets on U.S. recession fears.
Now its rapidly unraveling as TOPIX heads for its worst selloff since October 1987, while the banks sub index is on the way to its most dismal day on record. The TOPIX has gone from a peak gain for this year of just under 25% touched on July 11 to being about 6% down for 2024.
🇯🇵Japanese stocks fell sharply again, driven down by disappointing U.S. jobs data and a further rise in the yen. The TOPIX (-13%) and NIKKEI (-12%) indexes were on the verge of a bear market.
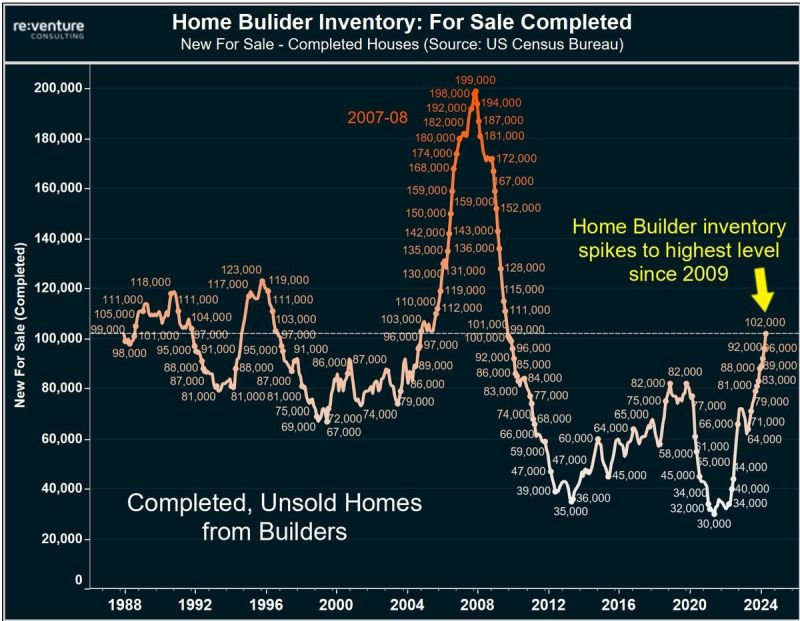
New home supply is skyrocketing in a market where mortgage demand is plummeting.
A record 1 out of 3 homes for sale right now is new construction.
Price cuts are coming soon.
🚨🇺🇸 BREAKING: Home builders now have 102,000 completed and unsold homes for sale on the market, the highest since 2009, according to Reventure.
This comes at a time when mortgage demand is at its lowest level in nearly 30 YEARS!
Meanwhile, there are a whopping 274,000 new homes under construction.
This is just ~62,000 less homes under construction than the PEAK before the 2008 Financial Crisis.