@DeepValueBagger Obviously the sector is likely to be a huge tailwind in the years to come, but curious what you think RKLB’s real competitive advantage is? It’s a company in going to start deep diving soon.
@QualCompounders Fair point. Though it remains to be seen whether Adobe can convert freemium users into paying subscribers. ADBE is a really interesting company to watch.
@DudeWhoInvests Are you adding to your Netflix position? It seems super undervalued now. My plan is to keep adding to it each month whilst it stays at this price.
Sometimes investing can become highly over-complicated. The investments that have served me best over the years, have been the ones which I could explain to a 6-year-old in two minutes. Eisman’s short position on FICO is a great example of this.
@DeepValueBagger I would wager half of the people pumping $FICO wouldn’t have been able to explain the business model to a 10-year-old. It has been a good lesson for people that 1) you must know what you own, and 2) you should be very exacting with whose opinions you listen to.
I think $ADBE is grossly undervalued relative to its current fundamentals. However, I only invest in companies that I’m happy to own for at least 10 years. Adobe could be a huge company in that time. Or it could be obsolete.
For me, Adobe is one of the most interesting setups in the market. Good luck to all owners.
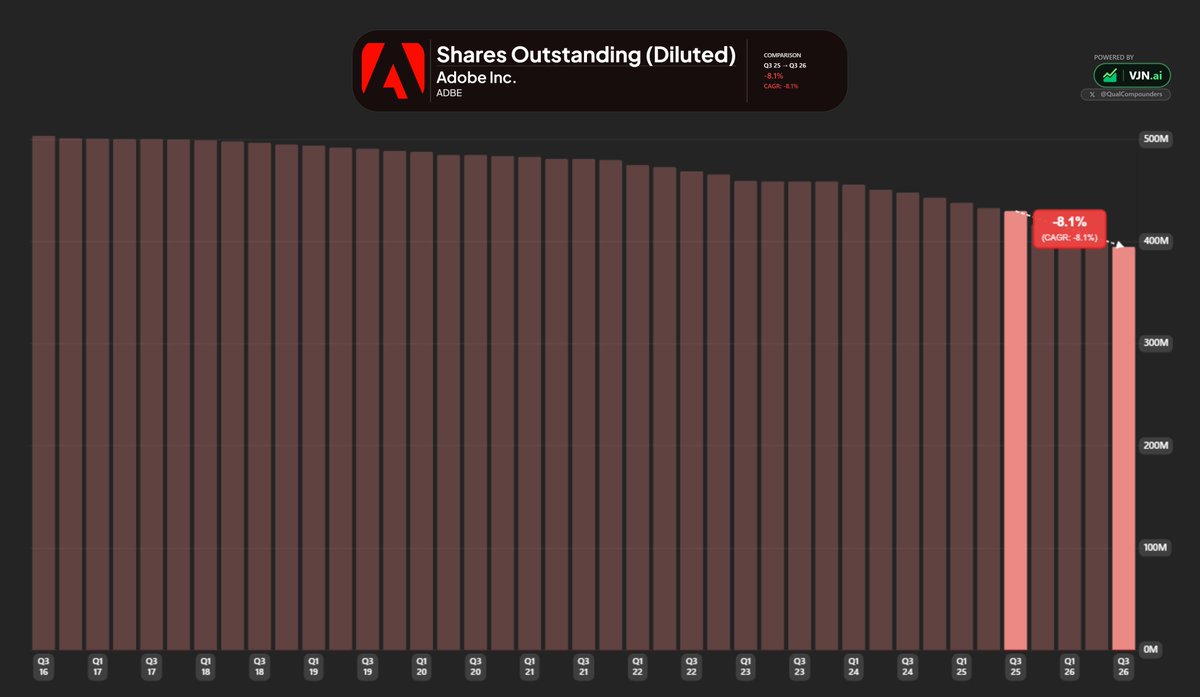
$ADBE is using its depressed share price to buy back 8.1% of the float this year.
If the AI disruption narrative fades, these buybacks will be extremely accretive as they will boost EPS.
@babyfolio@michaelcassau This is a significant point. Here in the UK, most people I know haven’t even heard of Muse. Meta has a first-mover advantage in the US, for sure, but elsewhere there is still a gap to be filled.
I think even if Uber took a lower percentage of the ride (say, 80% to the AV operator), the cost of travel is likely to decrease over time. The lower the cost, the greater the number of rides, which would benefit Uber even with lower take-rates.
You make a very fair point, though.
The market is bearish on $UBER due to concerns about autonomous vehicles. The current market price reflects this. What if the market is wrong?
In their Q2 results, Uber says: "We’re investing from a position of strength, as we accelerate our cross-platform strategy at a global scale and build the world’s largest platform for autonomous vehicles.”
But the real story is the potential for growth. Currently, AV rides (which will be significantly higher margin over time) currently accounts for less than 0.5% of the overall trips.
Uber only operates autonomous vehicle rides in 7 cities globally. They are on track to double this by the end of the year.
The expansion is coming. The AV market will be fragmented, and Uber is best place to benefit from it.
The potential growth opportunity for Uber and AVs seems immense. It is so early.
Hard to see how $AMZN isn’t a long-term winner from here.
It has an unmatched scale and infrastructure moat.
The forthcoming era of robotics and automation is an incalculably significant tailwind.
AWS growing at a tremendous rate.
And you get all of that for a reasonable price.
It’s true in Burry’s 2008 context. Each year his thesis didn’t materialise, he had to pay huge premiums on his credit default swaps. He would have depleted his fund if the thesis didn’t play out in a limited period of time. Not to mention his investors were threatening to pull their capital out of his fund. So, being too early and being wrong were effectively the same thing in his context - though of course his thesis ended up playing out in time.
Of course, for the long investor, the above wouldn’t apply as the market will catch up to fundamentals eventually, and you’re not working against the clock.
@2CommaInvestor Absolutely. Buffett wrote in one of his annual letters, “If you aren’t willing to hold the stock for ten years, don’t even think about buying it for ten minutes.” It’s a good rule to stick to.
@burak_finance The dilution is painful in the short term, but the $ONDS bull would say they are scaling their business through acquisitions, and thereby positioning themselves to be a serious player in (what will undoubtedly be) a hugely profitable sector. Really interesting company, imo.
@StockMarketNerd Completely agree with this. Meta can entice people into Muse for free, and make it a sticky product by having people spend time setting up their accounts/passwords/related apps.
1. The fact that OpenAI didn’t simply pre-record this demo is astonishing.
2. I think $META has a real first-mover advantage. People are already embedding themselves into Muse: passwords, apps, profiles, and so on.