Tokenized assets earned 45% of Raydium's Q3 swap revenue, up from 19.5% in Q2.
Stock pairs held about a fifth of volume.
Raydium's cut of their fees rose to 6.67 bps per dollar traded in Q3, from 1.74.
Tokenization really does open the flood gates for asset issuers to distribute their products globally, but also for the individual investor to access products you would never have been able to invest in 5 years ago. @_yakovsky and I discussed this during our recent Proof of Vision interview.
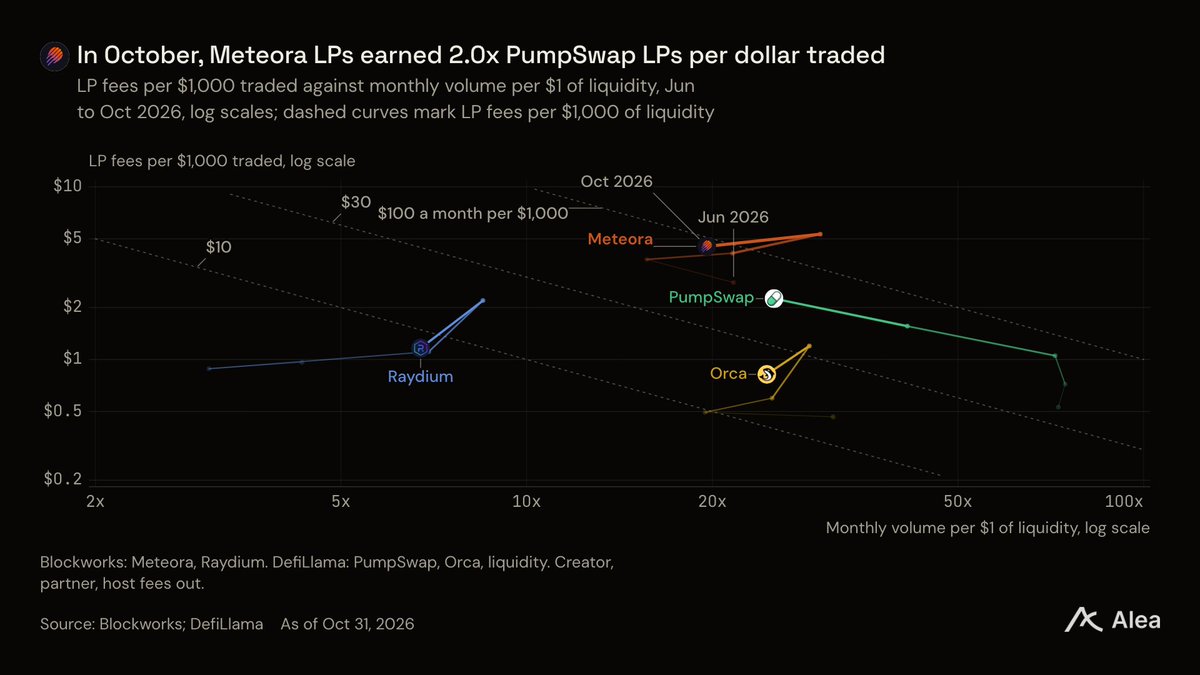
In October, @MeteoraAG's LPs took $4.51 of every $1,000 traded, twice PumpSwap's take.
Each $1,000 of Meteora liquidity earned its LPs $88 in gross fees. On PumpSwap, it earned $57.
Rewards per dollar of USDe supply ran at 3.7% to 4.9% a year in every month from January to September.
The range held even in April, when perp funding averaged minus 1.2%.
Lending to trading firms grew too.
FalconX opened a $1B facility with Ethena on Aug 19 and had drawn $237M of it by the end of September, secured by $394M of collateral.
Securitize registered its transfer agent on Jul 31, 2019, bought Pacific Stock Transfer in February 2022, and tokenized a KKR feeder fund on Sep 13, 2022.
BlackRock's BUIDL arrived on Mar 20, 2024.
The licenses came first. The scale followed.
Aave, Morpho, Spark, Kamino, Compound, Fluid and Euler compete for the same crypto collateral and stablecoin borrowers.
At Sep 30, Aave held 50.6% of their deposits, 54.0% of their loans and 49.2% of their Q3 fees. Morpho rose from 23.7% to 25.5% of deposits in Q3.
Of new borrowers from May to July, Aave Core's came back more often than Spark's on Ethereum.
32% of Aave Core's borrowed again the next month and 25% three months on. At Spark the figures were 28% and 19%.
Maple's Q3 revenue after depositor rewards rose 37% from a year earlier, from $3.15M to about $4.31M.
Drips paid about $1.05M of SYRUP in Q3 2025 and had ended by Q2 2026.