What are we working on at the moment?
In June we published a detailed analysis of Qantas's A321XLR entry into service. Now it's time to have a look at the A220. With more data at our disposal, we're taking a look at reliability & network strategy!
https://t.co/S3yXUXolNE
🚨NEW: Where next for Qantas after Cape Town?
Everyone knows we hate route speculation but when we do we bring the receipts!
Could Qantas add another European destination? Yes, but which? It's probably not Frankfurt!
https://t.co/x1sXwNJfWM
Given some of the commentary on Qantas this week it's probably a good time to reshare this article from last year👇
It highlights why running a capital intensive business like an airline is difficult & making a reasonable profit isn't sufficient!
https://t.co/8GcCHZb3St
Plenty, but probably too late now. Their A330neos start arriving soon, sooner than any leased ones would arrive. They've probably timed firming up these purchase rights perfectly given their plan.
The time to bring in some short term leased replacements would've been a few years ago, although there wasn't much available then.
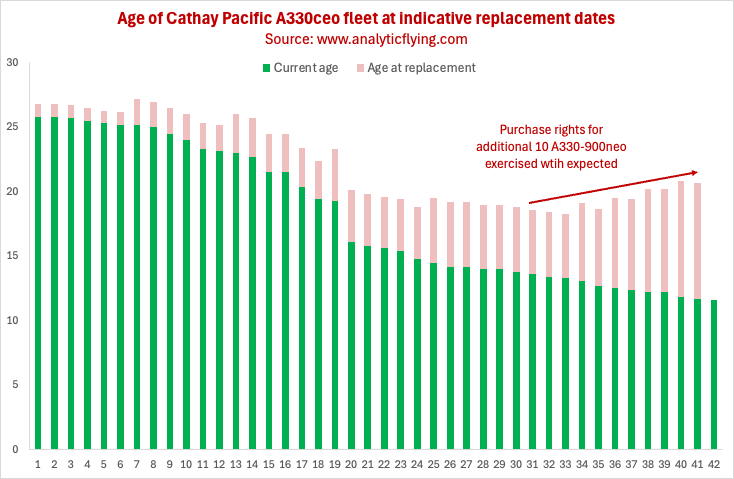
✈️🇭🇰Cathay Pacific just exercised 10 A330neo purchase rights taking their order to 40 to replace their 41 A330ceo
Purchase rights don't guarantee delivery slots so firming them up is required to assign a delivery slot. But why now? 👇
🔴CX's A330ceo fleet is pretty old → presently 12 to 26y, with 17/41 aircraft already >20y
🔴1st tranche of A330neo (30) due 2027-31 → 19 A330ceo will be 23-27y at replacement, but next 11 will be 19-20y
🔴2nd tranche (10) due 2031-35 → replacing 10 A330ceo that will be 19-21y at the time
🔴But that age curve of the final 10 A330ceo is creeping up; exercising purchase rights now ensures replacements arrive before 24y heavy check while also maintaining some flexibility
Sounds like you just made those numbers up 🤣
Qantas bonuses don't use EBITDA (they use PBT), but either way only short term bonuses use it. This will have 0 effect on FY27. In fact, redundancy costs will affect FY27 and thus make it more difficult to hit FY27 PBT target. And for future years they'll already be included in the baseline.
@CashdoesntLIE@farrm51 And a particularly capital intensive one. With annual capex of $3-4 billion, net profit of a little more than $1 billion doesn't generate a sufficient return on capital to pay for that capex.
@sittingwanderer Definitely not. Dates in these applications can be overly ambitious. Often trying to signal ability to do it so as to make their application more compelling.
🇦🇺🇮🇩Subtle change in Australia-Indonesia bilateral that nobody picked-up, but the sharp minds at Virgin have pointed it out to the IASC:
Avalon removed from the cap meaning it now has unlimited capacity!
Don't think it changes the argument but gives JQ a little extra scope!
🚨Virgin's application for expanded Aus-Indo capacity is in!
🔴Incremental MEL, PER & SYD to DPS increases proposed
🔴Big move on PER-DPS where VA don't have any presence
🔴Since applications exceed available capacity, QF/JQ & VA will have to motivate their proposals & IASC will run a competitive process!
@sittingwanderer It's now a competitive process and IASC unlikely to decide before then. It's still open for comments until 20 November and may take several more weeks to decide.
@_marty_k Correct. They had to reduce MEL-DPS to enable AVV-DPS; they can now use them wherever they want!
VA are arguing they should get more since updated ASA frees these up for QF/JQ to use. No doubt QF/JQ will argue that they took a risk starting AVV-DPS & shouldn't be penalised now.