The global economy doesn’t run on equity valuations, it runs on middle distillates, maritime choke points, and physical supply chains.
When you strip away the daily media noise, three critical realities are currently driving global market risk:
1. The Energy Squeeze Beyond Crude:
While retail traders focus on Brent crude headlines, the real structural damage is happening in middle distillates (diesel & jet fuel). Simultaneous export disruptions across major refining hubs hit long-haul freight, aviation, and agriculture directly. Downstream inflation always follows crack spreads.
2. Choke Point Vulnerability:
Geopolitical friction around maritime bottlenecks, from the Strait of Hormuz to Bab el-Mandeb, isn't just a defense headline; it's an immediate tax on global trade. When routing risk rises, insurance premiums surge, shipping lines detour, and supply chain friction compounds.
3. Signal vs. Rhetoric:
Press releases and political statements promise "imminent resolution," but military logistics, region-wide travel alerts, and emergency schedule clearings show the operational reality. Always trade the physical posture, not the media narrative.
With a background in journalism and a deep focus on global macro and energy market volatility, my objective is simple: cut through narrative spin to deliver clear, data-driven analysis on supply chain logistics and geopolitical risk.
If you’re trading energy futures, monitoring supply chains, or tracking global macro trends:
👇 Bookmark this post, follow for real-time analysis, and turn on notifications.
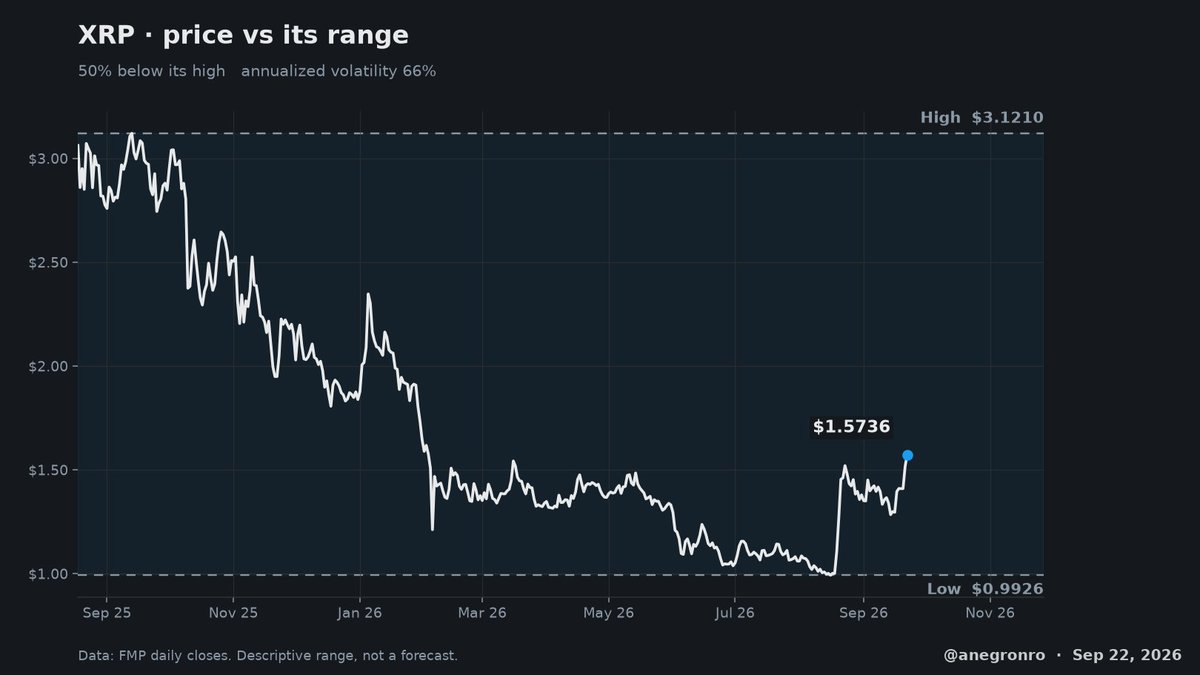
That isn't corridor demand. FMP has XRP at $1.57. A year ago it was $2.85. Same rails don't shed that much flow. I still read $XRP as a legal residual.
This month's jump tagged the high of the 10-year Treasury yield. Per FRED data that is 5.01%, from 4.65% a month ago. Equity multiples have not followed.
@WatcherGuru I don't see Moscow perps making Bitcoin's price the right one. $BTC is at $86,602, still 31% off the high per FMP. BTC just got more leverage.
I don't read this as permission. @SECGov said in a Federal Register notice it granted temporary conditional relief from the exchange definition for tokenized NMS stocks. That is a Section 36 waiver. If the conditions drop, those venues are exchanges again.
@zerohedge Weaponizing the Strait of Hormuz via a 20% detention levy is an immediate tax on global energy transport. Expect maritime insurance rates to spike and energy risk premiums to price in prolonged supply disruptions.
Adding perp futures across BTC, ETH, SOL, XRP, and TRX on MOEX creates a onshore, regulated proxy market insulated from Western exchange freezing orders. Watch for pricing spreads and funding rate discrepancies between MOEX crypto derivatives and offshore venues (Binance, Bybit) as local institutional demand tests ruble liquidity. Derivatives infrastructure as a geopolitical buffer.
The index is not the cycle. Per FRED data the 10y-2y Treasury spread is +20 bps, the low of the history I have. That flatten is a risk appetite cut stocks have not printed.
The distinction matters for capital allocation. Pumping from $85k to $115k under the ATH is local range expansion, where you're trading into heavy overhead distribution and trapped leverage. A true structural breakout occurs above major resistance ($126k ATH) where price enters price discovery and triggers systematic buy-stops. Vocabulary dictates risk parameters.
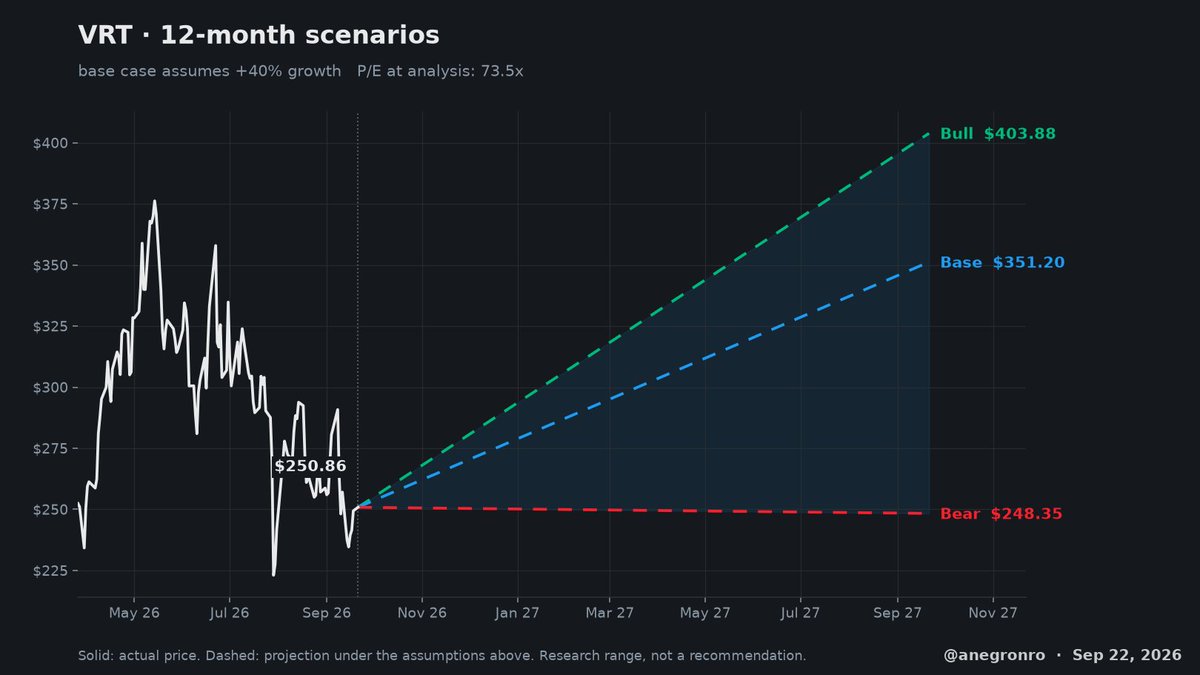
Sideways does not kill the VRT call for me. I'd mark a miss on a break of $248, not on silence. $VRT is still inside the range, and the base still assumes +40% growth.