October's AI selloff had a pattern: the further a stock fell, the harder it bounced.
Peak → low, then low → Oct 28 close:
1. $AAOI −48% → +22%
2. $LITE −34% → +21%
3. $VRT −23% → +25%
4. $NVDA −12% → +2%
Optics fell roughly 3–4x as hard as Nvidia, and is rebounding about 10x as fast.
Most of this was positioning, not fundamentals. Nothing in last week's earnings broke the AI demand story; crowded high-beta trades unwound. I'd want the rebound to hold through next week's optics earnings before calling it a bottom.
Bottom in AI infrastructure, or a dead-cat bounce in high beta?
Not financial advice.
The most-traded AI chip stock yesterday wasn’t $NVDA.
$MU: $29.9B traded, +5.86%
$NVDA: $20.1B traded, −1.17%
$AMD: $10.8B, +3.24%
SK Hynix’s record quarter turned memory into the crowded trade.
My take: Memory used to be the cyclical afterthought of AI. When it out-trades NVDA by ~$10B in a day, the market is saying the bottleneck has moved to memory. But crowded cuts both ways: MU gave back ~2.5% after hours. I’m watching whether it holds the gap today.
Not financial advice.
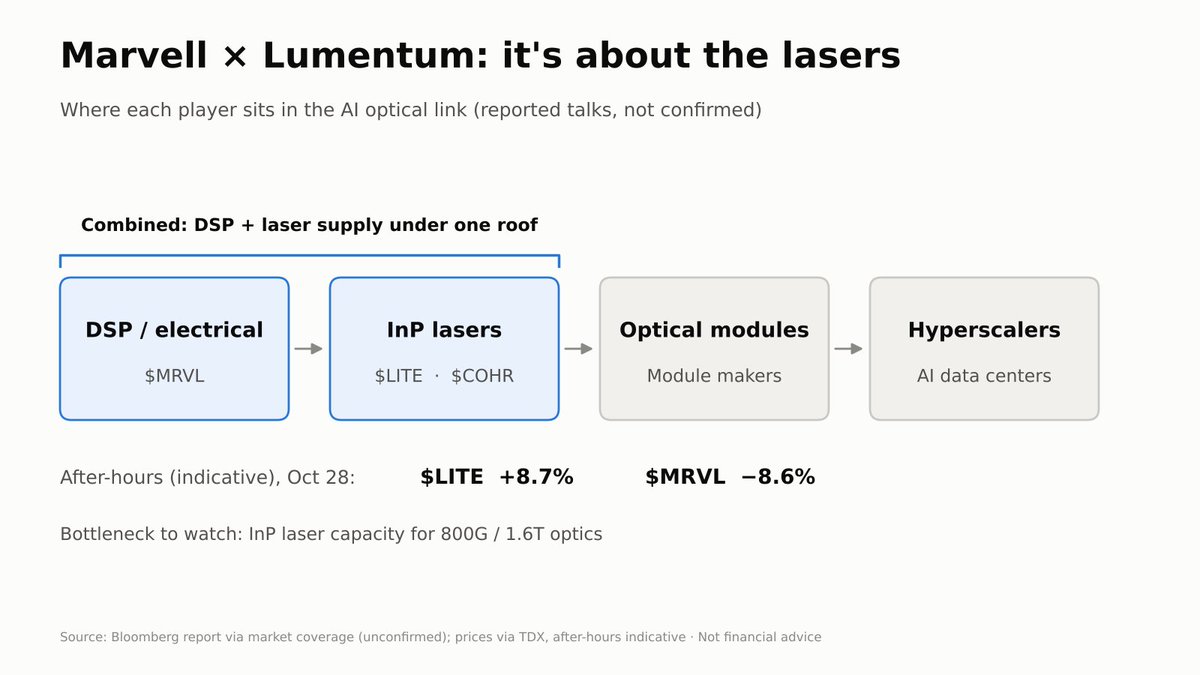
Everyone’s reading $MRVL × $LITE as an optics-module deal. I think it’s a laser supply deal.
The bottleneck in 1.6T optics isn’t DSPs, it’s InP lasers. Lumentum is one of the few at scale.
Own the laser fab, and $MRVL controls supply its competitors depend on.
Market’s first vote (after hours): $LITE ~+8.7%, $MRVL ~−8.6%. Investors are pricing the cost, not the moat yet.
Watch $COHR: a vertically integrated Marvell is a bigger rival overnight.
My take: In a supply-constrained market, owning the scarce input beats owning the biggest share. If this closes, pricing power in the optical link moves upstream. Module makers get squeezed between one integrated supplier and the hyperscalers. MRVL’s −8.6% is the market’s first draft. The real test is the price and whether it’s paid in stock.
Reported talks only, nothing confirmed. Not financial advice.