After over two months of fighting, my original account (@MarketMatrixs) with 25,000 of you was permanently locked down due to an automated false-positive flag for "inauthentic behavior."
Anyone who knows me knows how much time, late nights, and genuine passion I poured into that page line by line. Losing years of work and a community of 25k to an algorithm, with zero human review, has been devastating.
I’m done waiting on automated system loops. Today, I’m building from scratch.
I’ve started a brand-new official page under this handle.
If you enjoyed the work, insights, and conversations we built together on the old page, I would deeply appreciate your support right now. A follow, a repost, or just tagging someone who used to follow the old account goes a massive way in helping me rebuild what was lost.
We built 25k once, and with your support, we’ll build it back even stronger.
New handle: @armaanzinvest
Thank you to everyone who has reached out and had my back through this. Let's get to work.
Especially my $ASTS crew 🫡
🚨 REMINDER:
The Canadian 🇨🇦 stock market will be CLOSED tomorrow for Thanksgiving and will reopen Tuesday.
U.S markets are business as usual for Columbus Day - (Bond market is closed)
Happy Thanksgiving Canadian friends.
Enjoy!
“We are not building the operating platform for the Ondas of today, but for the significantly larger company we expect Ondas to become.”
- Eric Brock, CEO of $ONDS
When the market looks at $ONDS it sees a pile of acquisitions being built off of shareholder dilution. I see a defense company being assembled in real time without tapping the debt market.
Ondas has a $757 million pro forma backlog with a revenue target of $525 to $550 million for the 2026 fiscal year. I started a position at the end of last week and finished writing a bullish deep dive which will be out tomorrow.
I believe that the acquisitions, customer relationships and $PLTR partnership are beginning to fit together. This combination could become dramatically more valuable over the next five years. Here is the underlying business Ondas is building at a time when autonomous warfare is still in it’s infancy:
· Sentrycs provides cyber-based counter-drone capabilities
· Iron Drone adds physical interception
· DZYNE brings Dronebuster, the ULTRA reconnaissance aircraft and IonStrike.
· World View adds persistent sensing from the stratosphere
· Roboteam adds ground robotics
I see a company positioning itself to detect threats, collect intelligence and deliver responses across multiple domains. Integrating those capabilities could make Ondas more valuable to a customer than any individual product.
Then there is Mistral which was a brilliant acquisition. That acquisition gives Ondas direct prime contractor access to U.S. Army and Special Operations contract vehicles, alongside domestic manufacturing and integration capabilities. Owning that customer relationship matters when you are trying to turn a growing technology portfolio into larger defense programs.
The financial progress is getting harder to ignore:
• Q2 revenue: $83.8 million, up 67% sequentially
• Pro forma organic revenue growth: 85% year over year
• Reported June backlog: $613 million
• Pro forma backlog including DZYNE and Cyberhawk: $757 million
• Full-year 2026 revenue target: $525–$550 million
I will be focusing on the organic growth Ondas can produce because acquisitions alone cannot carry this thesis indefinitely. I want to see the underlying businesses growing while orders convert into deliveries with more cash hitting the cash flow statement.
Palantir is where the longer-term opportunity gets especially interesting. The $PLTR partnership covers manufacturing, mission planning and intelligence processing aboard autonomous platforms. SkyWeaver is being developed to process information closer to the mission and support operations when connectivity is degraded.
My view is that coordinating drones, sensors and ground systems could become one of the most valuable parts of this market. Ondas has an opportunity to participate in that software layer alongside its hardware. A recurring software business would strengthen the economics considerably.
The balance sheet also matters as Ondas ended June with approximately $1.38 billion in cash, cash equivalents and short-term investments, against roughly $6.4 million of debt. Subsequent acquisitions have consumed substantial cash but that starting position gives management room to build.
Equity financing has a real cost as every new share reduces my ownership unless the value created exceeds dilution. I am judging management on whether this acquisition strategy ultimately produces greater earning power per share. You will need to read my article which is forthcoming to see my bull case and price targets.
I will be watching organic growth, backlog conversion, cash consumption and the share count together. My bet is that Ondas can turn this collection of capabilities into a profitable defense platform whose earning power grows faster than its share count.
My question for the Ondas community is which development do you think would provide the strongest evidence that this strategy is working?
🚨 $IREN x Anthropic Leak
The Information, one of the best-sourced outlets covering the AI industry, just reported that Anthropic recently signed a cloud deal with $IREN.
For anybody who has followed management’s commentary closely over the past few weeks, this doesn’t come as much of a surprise.
First, $IREN announced a new contract with an unnamed “leading frontier AI lab” during its recent earnings call, followed by CCO Kent Draper revealing that the company in question was “1 of 2” possible customers.
While The Information didn’t disclose any specific MW amounts or terms of the deal, I believe it’s very likely that Anthropic secured the 50 MW of air-cooled B300 capacity coming online at $IREN's Childress site THIS year.
As for the economics behind the deal and where this relationship could go from here, we recently published an in-depth report for both our X and Substack subscribers covering exactly that.
I’ll link it below in the comments for anybody interested.
Wishing everybody a great rest of Sunday and a great start to the new week. Cheers!
Futures are open as the stock market opens tomorrow!
Decently green to start!
Happy Thanksgiving to all my Canadian fellows! Enjoy the day off tomorrow.
$OSCR profitability just had an insane inflection point.
Q1 2026: $1.4B —> Q2 2026: $4.9B
That’s a ~250% increase in just ONE quarter.
+$3.5B in a matter of 3 months.
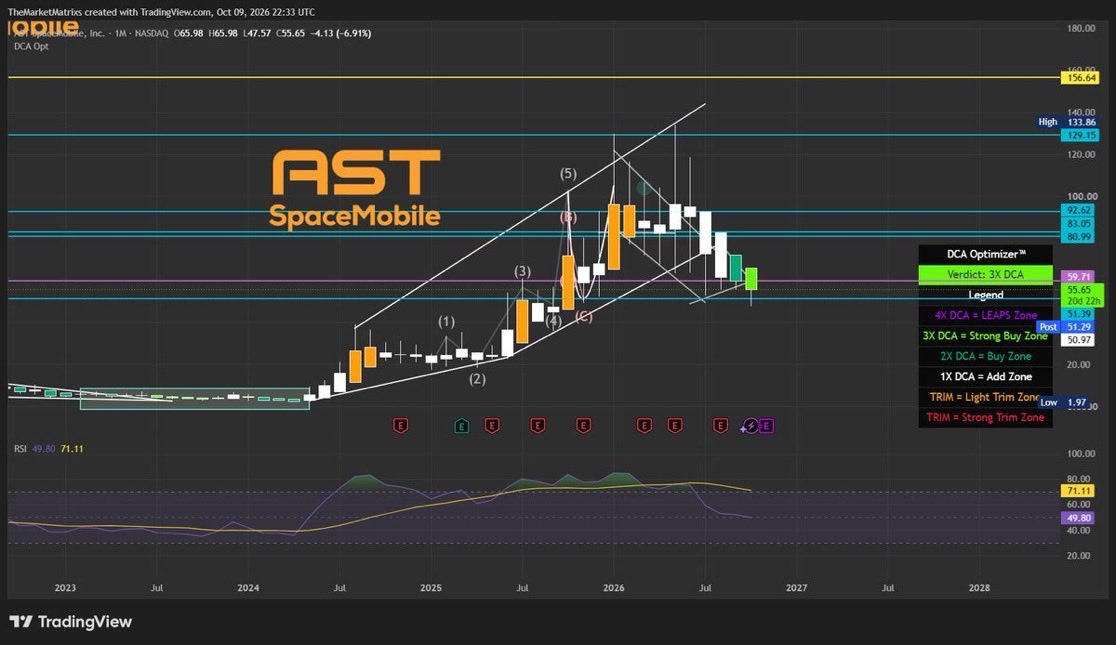
$ASTS
- Nearing oversold territory
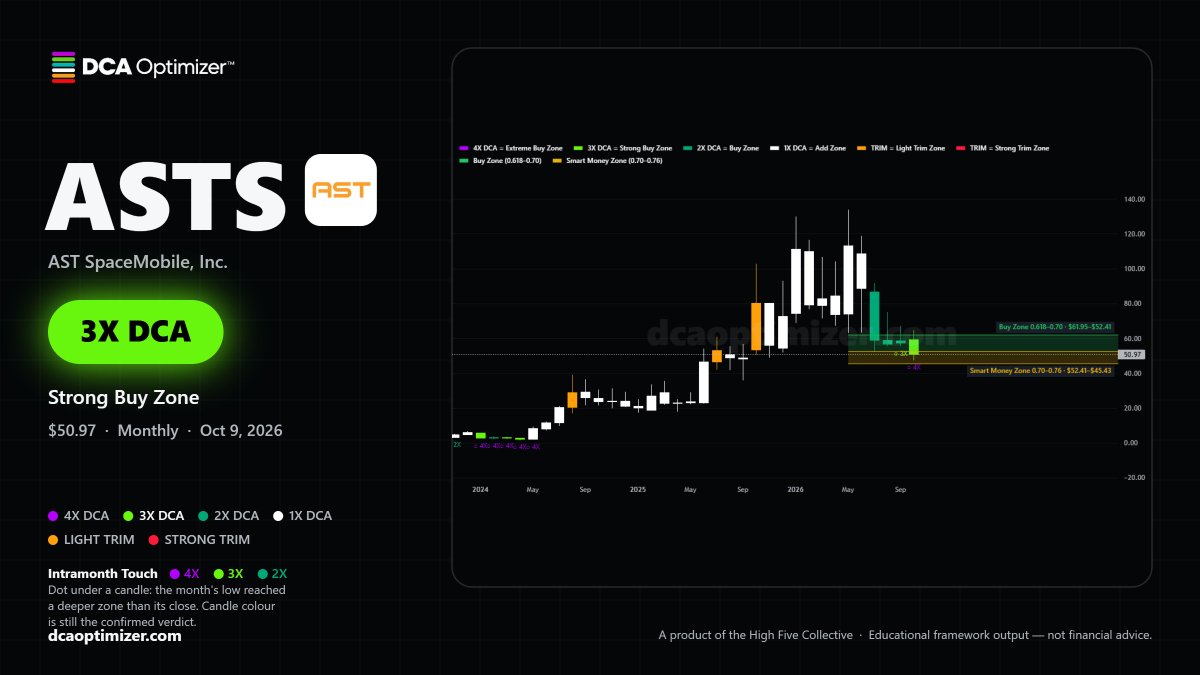
- in the 3x DCA zone
- Radar testing coming
- BB 14, 15, 16 launch soon
- $SPCX only validating the market
This is a massive opportunity.
I'm no $ASTS bull or investor but am I common sensing this correctly...?
$SPCX is becoming a massive competitor to the communication companies like Verizon, AT&T, and T-Mobile.
Meanwhile AST SpaceMobile is the one selling the picks and shovels to them so they can compete and not fade into existence. Thus, ASTS is $NVDA in this situation, no?
So more competition equals more desperation which equals more CAPEX into ASTS. Meaning more revenue and the business model isn't dying, it's accelerating.
If I'm common-sensing this wrong please let me know in the comments below.
This all while ASTS is in the Strong Buy Zone (3X DCA) for the first time in 3 years.
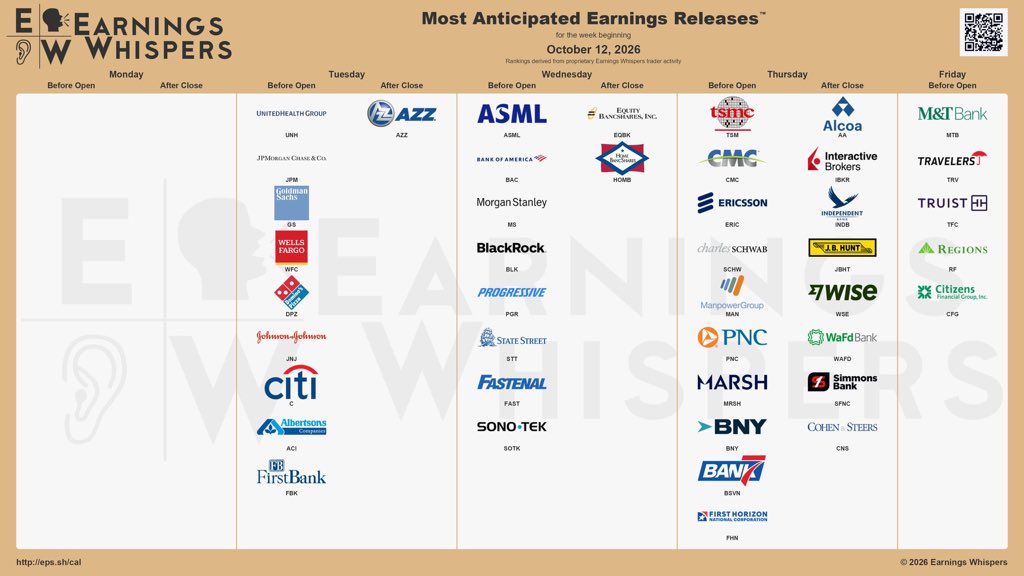
EARNINGS SEASON IS BACK!
+ CPI/PPI data..
Monday: $UNH, $JPM, $GS $WFC, $JNJ, $C
Wednesday: $ASML, $BLK, $MS
Thursday: $TSM
And then CPI data on Wednesday and PPI Thursday.
Buckle up!
Surprises me how people are buying $SPY and $QQQ at all-time highs while:
$ASTS is down -61% from ATH’s
$SOFI is down -50% from ATH’s
$AAOI is down -50% from ATH’s
$VRT is down -36% from ATH’s
$CRDO is down -30% from ATH’s
And remember..
$AAOI is down -51% from all-time highs
$COHR is down-27% from all-time highs
$LITE is the only photonics name to hit all-time highs after June.
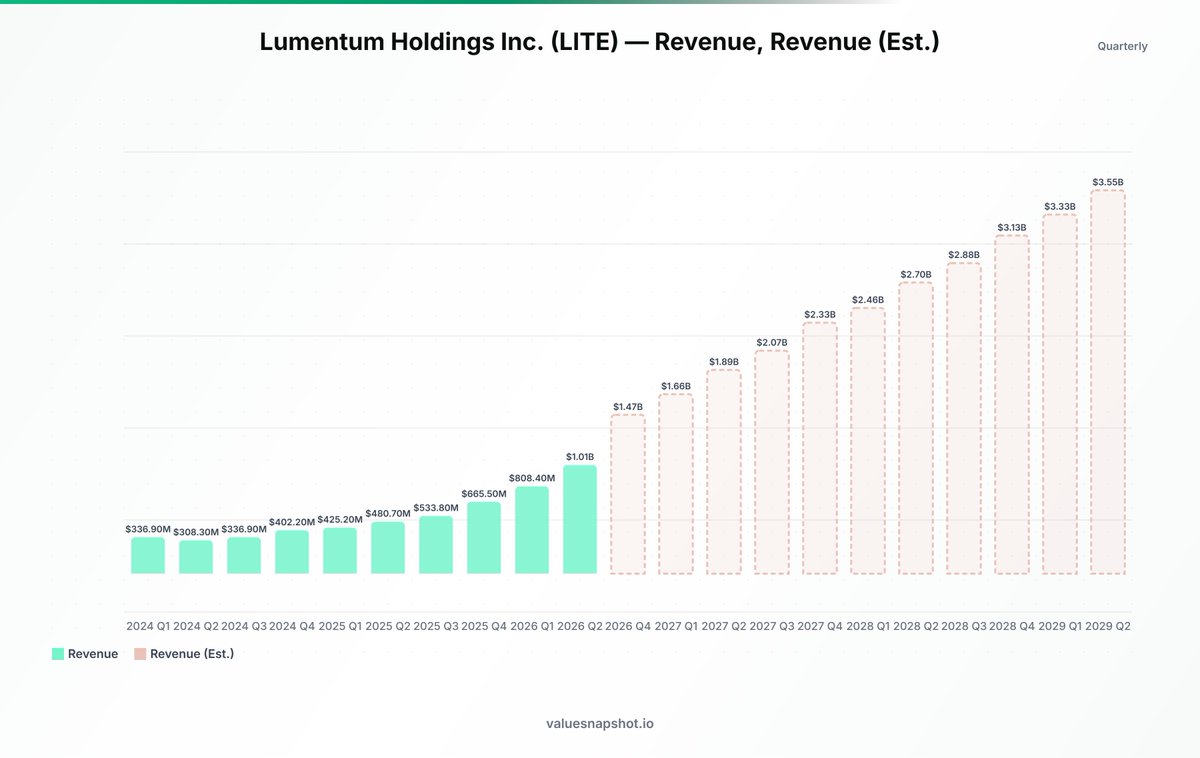
$LITE AI demand is getting ridiculous.
CEO Michael Hurlston says Lumentum can only supply 30% of demand for certain products.
That means demand is roughly 3.3x available supply.
Revenue grew 83% in FY2026 to $3.01B, and Q1 FY2027 guidance implies a ~$5B ARR at midpoint
🚨 COMING SOON...
I've been working on something BIG behind the scenes, friends.
The DCA Optimizer is becoming its own standalone website, giving investors and traders the ability to identify when to BUY MORE, when to WAIT, and when to TRIM.
Monthly DCA signals, charts, screeners, historical backtests, market-wide opportunities, and so much more.
The same tool that helped me optimize my $PLTR $ZETA $VST cost basis is getting an upgrade.
My goal is simple. Help everyday investors optimize their cost basis and make smarter long term investing decisions.
Here's your first look.
$ASTS could go from $71M in revenue in 2025 to nearly $1.8 BILLION in 2028.
That’s a 25x increase in just 3 years, with EPS projected to turn positive by 2028.
And now, $SPCX is making an $8B play to become a mobile carrier.
Validates just how valuable that market could be..