@MylesMcNulty@Cumulus51896691 I think #AVCT’s mega competitive/FIC drug development speed is often overlooked
- Conveyor belt of assets = more opportunities
- Speed to IND = Maximising the patent window
- Trial efficiency = rapidly to market
A facet almost unique to the platform + widening preCISION’s moat
“Idea to drug in mere months”
Hugely significant.
I’ll reiterate: the drug assets matter but pre|CISION - the platform that enables it all - is everything
Compressing product dev timelines is high focus for pharma + another massive string to #AVCT’s bow
https://t.co/pgZSnWhCvS
@tom_the_bomb__@JStonker AVA6000 Ph1 complete… has been a long time coming.
AVA6103 indicated as ~50% through Ph1.
Appreciate it’s a crude graphic but comparison of trial efficiency between the two is night and day.
Excellent news on both counts.
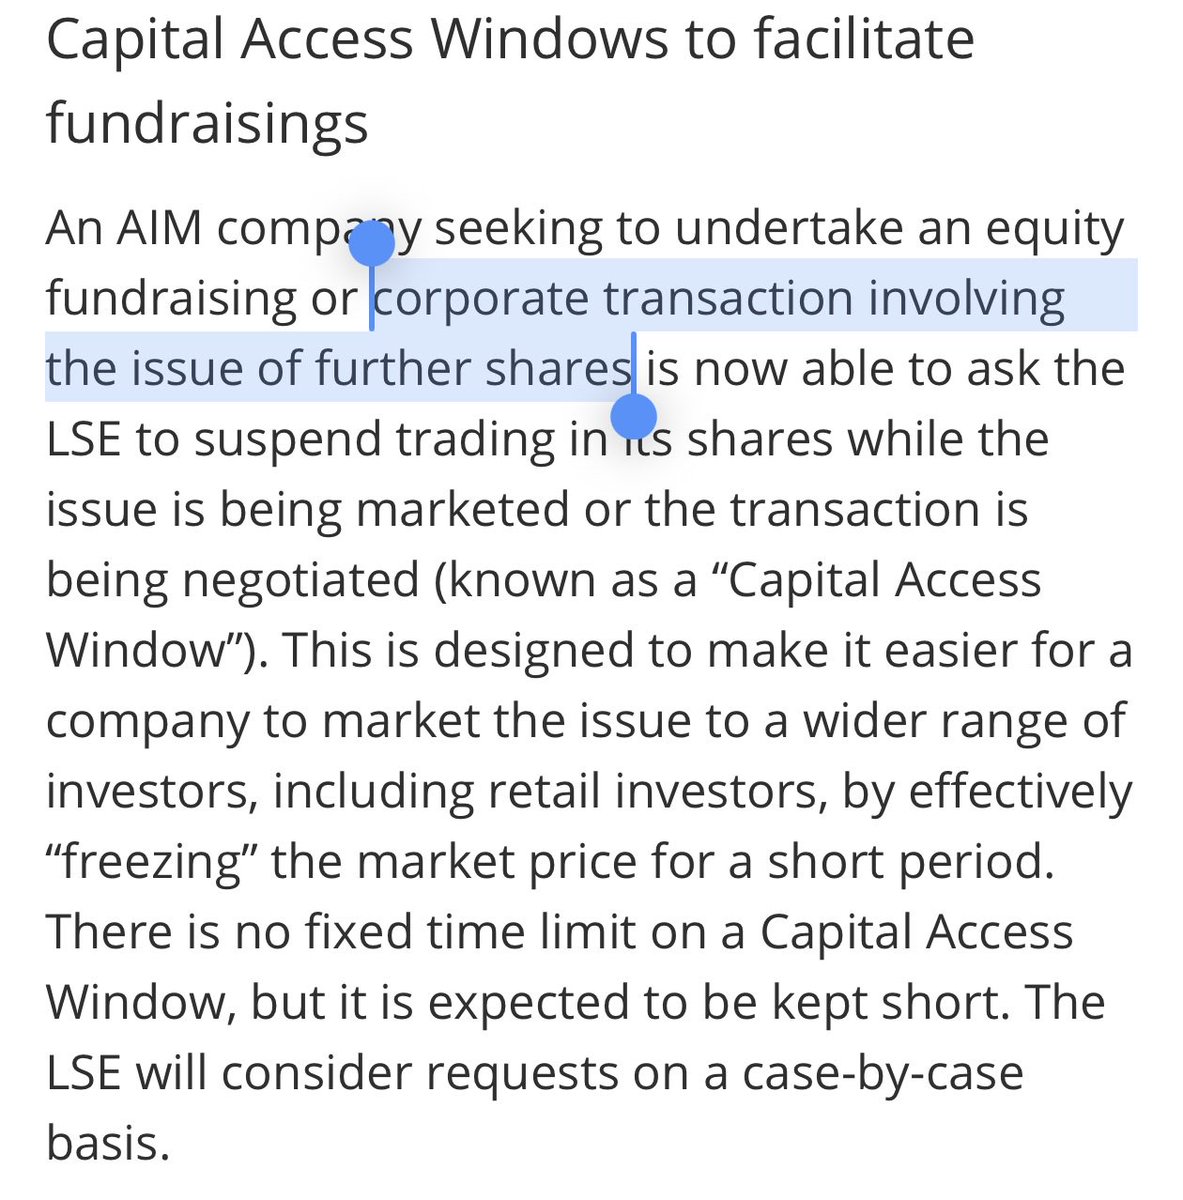
@tom_the_bomb__ Did a little looking into Capital Access Window yesterday, which has me leaning in a similar direction.
If a generic placing, it simply wouldn’t take 3 days execute. Something more complex in play IMO
@JStonker It’s a good observation.
Worth thinking broader than generic placing and consider other fundraising mechanisms which might include an equity component.
Commercial deal with equity component and cash? For “Faridoxorubicin, pending partnering” per the interims. 1/2
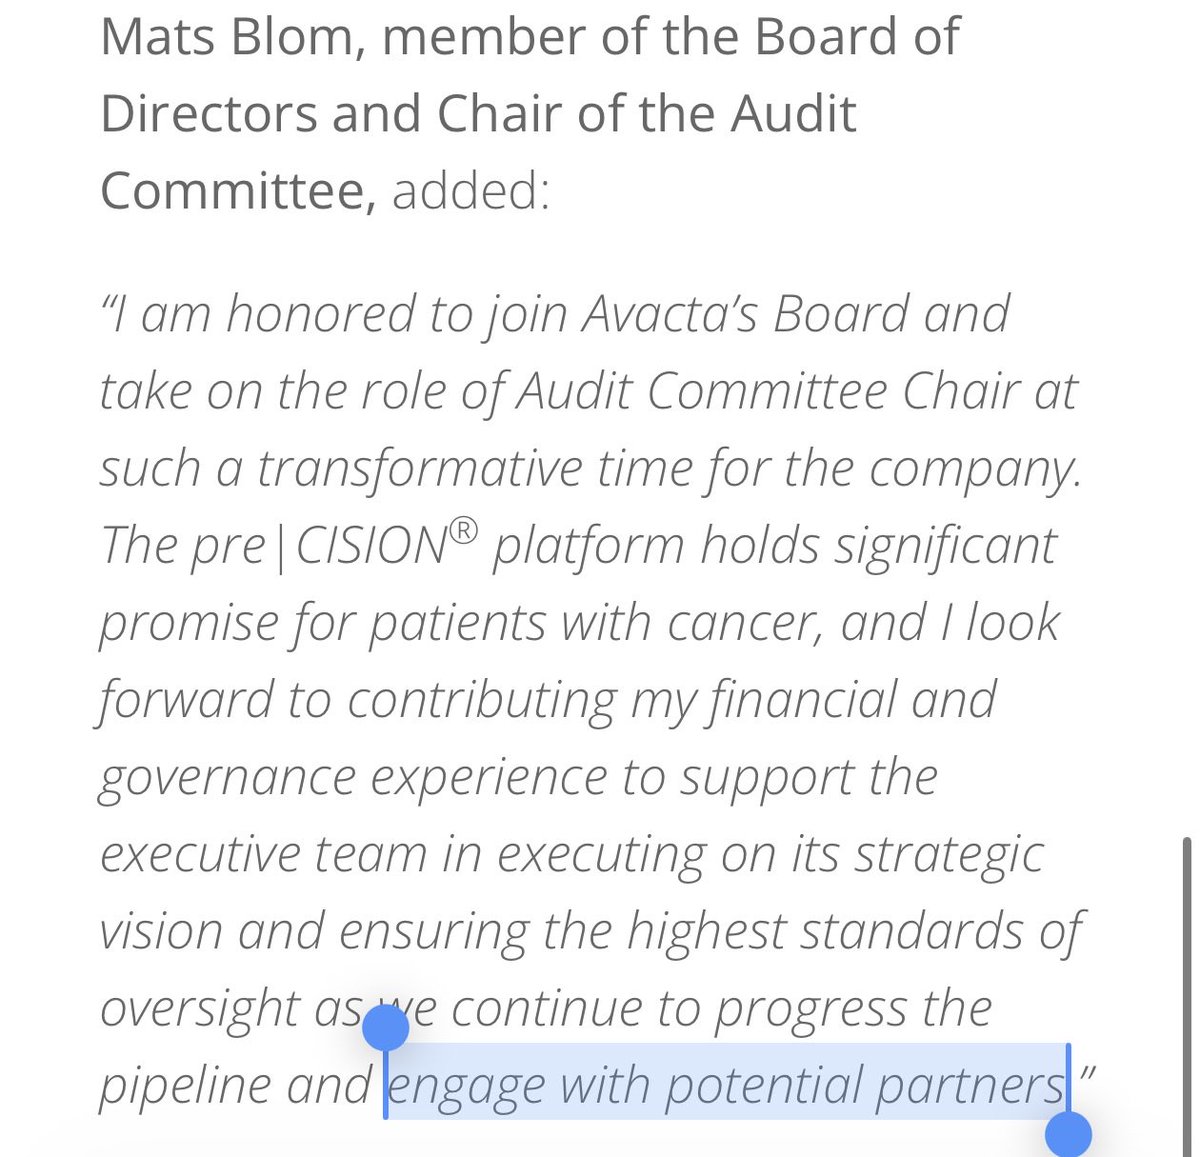
@tom_the_bomb__ Dep Chair + new AuditCo chair appointed, both biotech veterans. Latter officially stepping up on 30th September - the day the Capital Access Window opened
Not unreasonable to assume a partner would want #AVCT to beef up governance if handing over cash + taking an equity position
@JStonker “a raise is less likely than a partnering transaction, given FOCUS-01 + Phase 1b progress underpinning current partnering discussions'' - Zeus
Partnering + a non-standard raise could come together as an equity stake + u/f payment
Certainly a “broader range of investors”! 2/2
@JStonker It’s a good observation.
Worth thinking broader than generic placing and consider other fundraising mechanisms which might include an equity component.
Commercial deal with equity component and cash? For “Faridoxorubicin, pending partnering” per the interims. 1/2
In other #AVCT news ⬇️
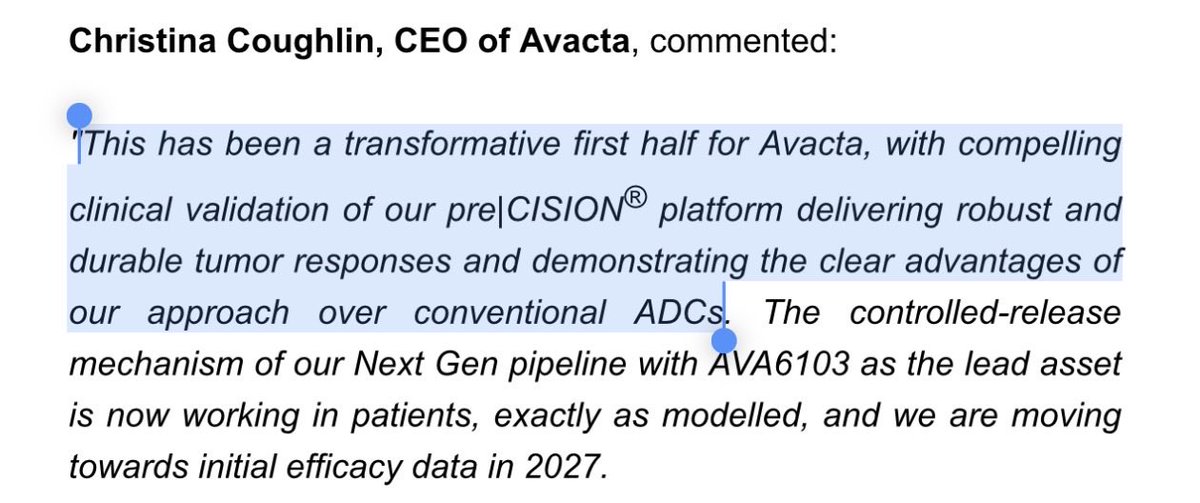
Surely nodding at more than a hint of efficacy in AVA6103? The key clinical activity and, therefore, validation in H1 being the FOCUS trial.
Doesn’t make sense for this comment to relate to A6K, IMO. Many have assumed AVA6103 efficacy, now confirmed? 2/2
Have to admit to be being disappointed about the prospect of another placing.
Remains my view the IP is mature enough to monetise but, admittedly, I don’t know what is playing out behind closed doors.
Expect this is a brief trading pause + there is plenty of demand.1/2 #AVCT
@PJ_Crabb@Ian07594592@RoryStuart15@hughesy0707 Agreed
Been of the view for a while now that we’ve passed the point where the business needs to be equity funded, as there is sufficient progress and scope across the IP (and resulting products) to now monetise the technology
Which is, in my view, more shareholder friendly
@BigBiteNow She didn’t manage coherent goodbyes to my wife or kids as we didn’t understand how little time we had with her
A drug offering more time would have meant a great deal
Some dont appreciate that + I truly hope they dont endure something that removes the veil on that ignorance.2/2
@BigBiteNow Same applies to PFS
My MiL passed away in ‘21 from uveal melanoma - a rare cancer, with very few treatment options
She endured chemo + trial drugs but to no avail
Her deterioration was rapid (days), with her cognitive decline being devastatingly fast + unexpected 1/2
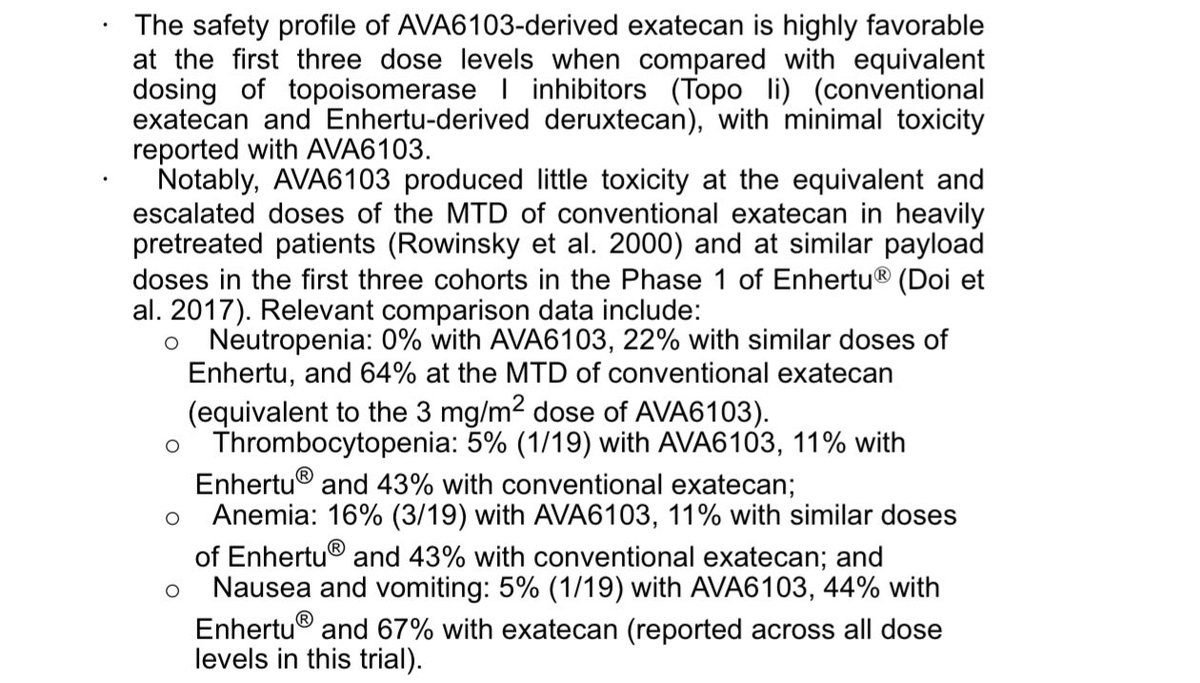
Back to 6103, the fact the below statement precedes the pre-clinical efficacy comparison with Enhertu, says it all really:
preclinical PK = modelled deep and prolonged partial responses ➡️ observed patient PK = patient anti tumour activity
Read between the lines 2/2 #AVCT
Astonishing safety comparisons with Enhertu, which did $1.4bn revenue in Q1 26.
The usual mention partnering, inflection points etc. We are talking serious, scaled deals given what is in the data. “Pipeline expansion”… left field… watch this space IMO 1/2 #AVCT
@111BEN_111@RAH00084 So CCs package being addressed now is likely well timed + will be diluted less than examples you’ve shared. She is also paid at lower end of scale relative to peers + gets no bonus. For a cash strapped co, solving this with stock is prudent IMO
Appreciate the discourse tho.4/4
@111BEN_111@RAH00084 I think the rapid delivery timeframes for new drugs that the co is demonstrating sees the above monetisation look after itself; coupled with platform tech and a growing body of clinical data. Therefore, I believe that slog + river of dilution js largely behind us. 3/4
@111BEN_111@RAH00084 At this time theres no better CEO for #AVCT, given the knowledge + leadership in FAP, team she’s built + critical period we face
It’s a lot of shares, yes. But you would need to give that sort of package to any incoming US CEO. Reward + retain is the right move here
All IMO.2/2
@111BEN_111@RAH00084 McKenna joined Prometheus in 2019, IPO happened in 21 + then further c50% dilution in 22. At one point he had >6% of the co having got 2.4m options, which was then diluted down/sold. He also had a bigger salary than CC 5 years ago + 55% bonus. So more nuanced than final value.1/2
@tom_the_bomb__ IMO low hurdles are to quickly correct this
It may be the last opp for such an issuance. Do it once + do it right
Keep high value ppl locked in during this crucial period. To hire a new CEO, you lose org knowledge, culture, momentum + give away more than we did yesterday.3/3
@tom_the_bomb__ Also creates a ceiling for US CFO + CMO, w US biotech expectations. So CC needed a material bump to make headroom for them. Use of Aon points for US benchmarking IMO
50k shares + 3.6m options prior to this, CC had no real skin in the game. This doesn’t reflect well on anyone.2/3