@Sharad9Dubey Simplex Castings Limited- Makes Cast and Fab. Bogies which are used in both Electric and Diesel Locomotives. Have visited their facility recently to check the same.
What separates a promoter who creates wealth from one who destroys it?
While putting together our latest study, “Promoter Edge,” we came across some fascinating patterns in Indian wealth creation.
Promoter-led companies have historically compounded better—but skin in the game alone is not enough.
A few observations stood out:
• Many exceptional wealth creators emerged when promoters were in the 40–55 age bracket — experience behind them, ambition ahead.
• A powerful model has been Owner Mindset + Professional Execution.
• And perhaps most importantly: what does a promoter do with every ₹100 the business earns? The “retained rupee” and how it is allocated can determine decades of compounding.
But ownership can cut both ways. Poor governance and capital allocation have also destroyed enormous shareholder wealth.
Which brings us to the central thought behind our latest IKIGAI study:
Promoter-led is not an investment thesis.
Promoter quality is.
We don’t invest in promoters.
We invest alongside the right promoters.
Ownership is visible. Stewardship is the edge.
Sharing our latest presentation — “Promoter Edge: Backing the Right Promoters is an Art for Wealth Creation.”
Would love to hear your views: What is the single most important quality you look for in a promoter?
Link for presentation:
https://t.co/LJjx4cJfLZ
#Investing #WealthCreation #CapitalAllocation #CorporateGovernance #LongTermInvesting #IKIGAI
Sat Kartar Life has signed an LOI to establish a new 20-bed Hospital-cum-Therapy Centre at Dehradun. The proposed 7,000 sq. ft. facility entails an investment of ₹70 lakh, funded through IPO proceeds, and is expected to become operational by 15th December 2026.
After crude shock in H1CY26…if the food inflation shock hits more….that too…ahead of festive season-this may become a double whammy…consumption is looking dicey….and only select plays would make sense…difficult times…but trading opportunities come up..especially with the industries having better pricing power…after sugar..others..sectors..may start moving..,
Soft commodities price rise..is more sticky in nature and can last 2-4 quarters..while action in hard commodities etc…maybe more volatile and less sticky…we may be entering 2022 cycle…good to see…what history is showing…only 1.5 to 2 months of erratic monsoon is left.,,
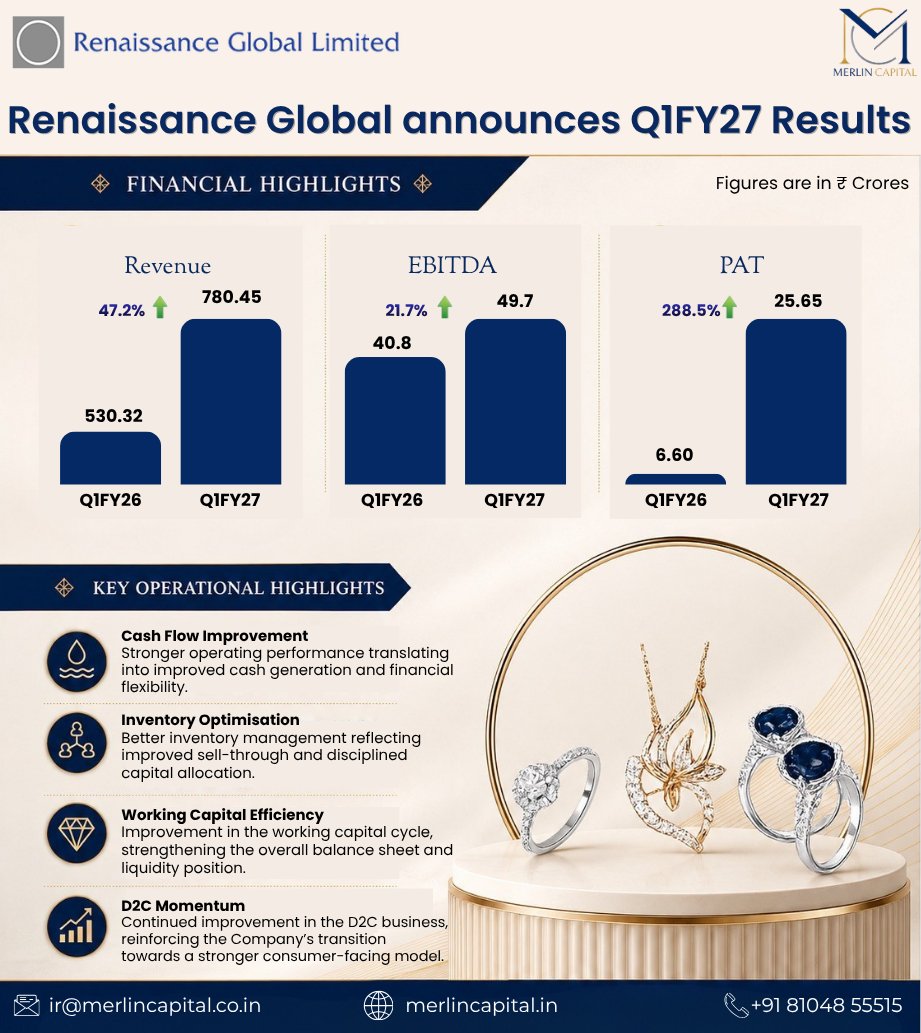
Renaissance Global Limited has reported a strong start to FY27, delivering healthy growth!
Q1 FY27 Financial Highlights:
• Revenue: ₹780.45 Cr, up 47.2% YoY from ₹530.32 Cr
• EBITDA: ₹49.7 Cr, up 21.7% YoY from ₹40.8 Cr
• PAT: ₹25.65 Cr, up 288.5% YoY from ₹6.60 Cr
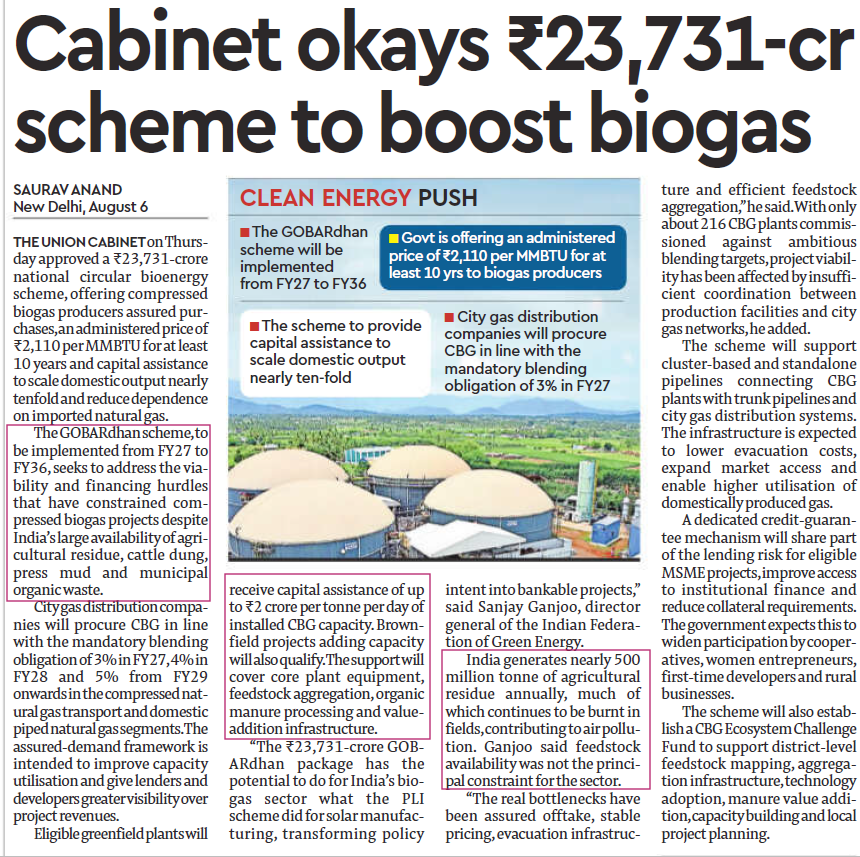
India’s clean energy transition receives a significant push with the Union Cabinet approving a ₹23,731 crore scheme to accelerate the country’s biogas ecosystem.
Capri Global Ventures Private Limited has acquired 5,00,000 equity shares of Simplex Castings Limited through a bulk deal at a price of ₹97 per share on August 6, 2026 (today).
Despite a huge shortage in memory chips, Sony India is eyeing a revenue potential of INR 10k Cr. from its televisions vertical. Spokesperson also mentions that they're seeing premiumization as the key driver here with interest from both rural and urban pockets.
RENAISSANCE GLOBAL: CO. ANNOUNCES OPENING OF THIRD JEAN DOUSSET STORE IN SAN FRANCISCO, STRENGTHENING ITS BRAND FOOTPRINT
RENAISSANCE GLOBAL: CO'S CEO SAYS WE INTEND TO ESTABLISH JEAN DOUSSET IN ANOTHER 4 LOCATION, TAKING OUR NETWORK TO SEVEN STORES BY THE END OF FY27
A unique approach seen by Renaissance Global to INCREASE their number of stores in FY27, which was originally planned to be 3 more stories- and is now 5. Have done a good DD in USA over the months to know that the demand for this brand is EXCELLENT!!
Renaissance Global Limited has opened its third Jean Dousset retail store in San Francisco, marking the beginning of a significantly larger physical retail rollout for its ultra-premium luxury jewellery brand in the United States.
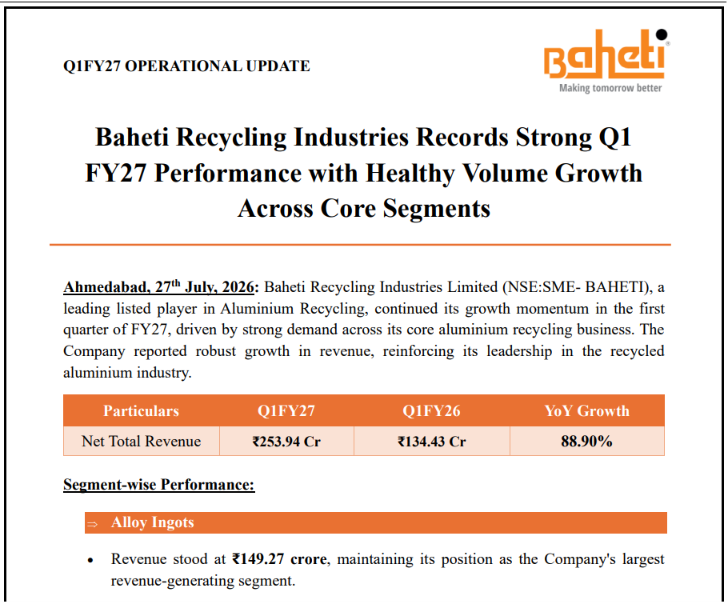
Baheti Recycling Industries Limited (SME) Q1FY27 Business Update
➤ Net Total Revenue ₹253.94 Cr (+88.90% YoY)
➤ Alloy Ingots remained the largest revenue contributor, generating ₹149.27 Cr
➤ De-Ox segment reported revenue of ₹63.87 Cr, supported by healthy industrial demand
➤ Copper Alloy Ingots contributed ₹4.72 Cr, marking the commencement of sales in this new value-added product category
➤ Strong revenue growth was driven by sustained demand across the company's aluminium recycling business, improved product mix, and efficient execution
➤ Entry into the Copper Alloy Ingots segment represents a key milestone in expanding the company's value-added product portfolio
➤ Management remains focused on strengthening manufacturing capabilities, deepening customer relationships, and capitalizing on the growing preference for sustainable recycled metals
➤ Management highlighted a strong start to FY27 with robust growth across core business segments
➤ Company expects continued momentum, supported by rising demand for recycled aluminium products and its expanding portfolio of value-added offerings
Have grown up studying on an IFPD in my school, it’s a big game-changer compared to traditional teaching and learning methods!
Closely tracking this theme.
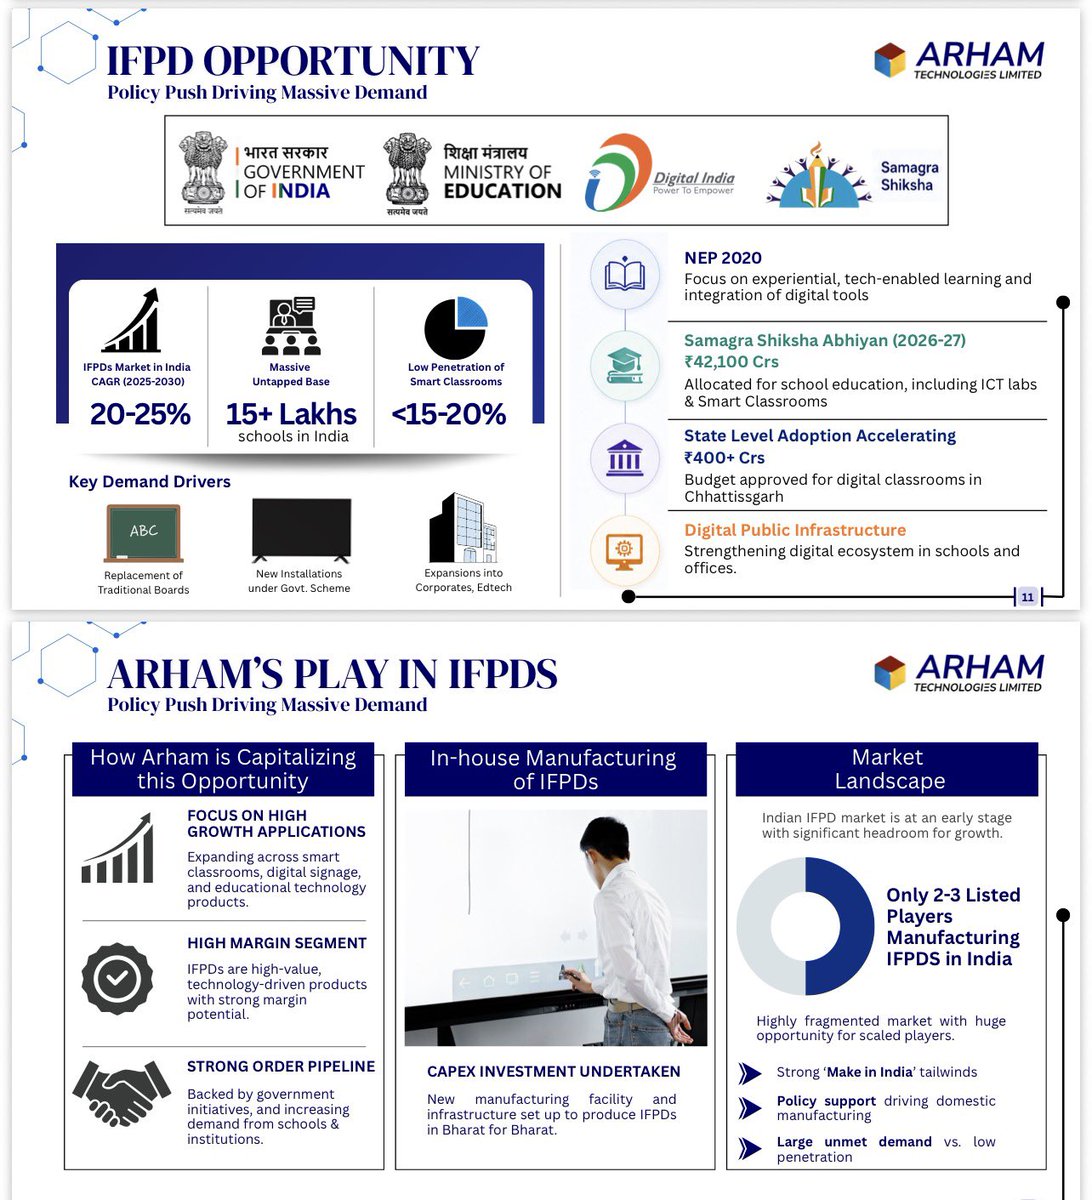
SME company called Arham Tech..manufactures IFPD (Interactive Flat Panel Display)-Smart Boards
With NEP Push and Urgent Need For Smart Classes..Becomes Important.
Large Tenders Announced By PSUs..will be interesting track this theme.
Concall Summary of Q1FY27 of Gandhar Oil Refinery (India) Ltd
BUSINESS OVERVIEW
* Q1FY27 was the strongest quarter in the company's history, with record profits driven by healthy volume growth, better realizations and a sharp improvement in gross margins.
* Despite geopolitical disruptions, revenue growth remained strong, supported by agile sourcing, disciplined execution and a diversified product portfolio.
* The company continues to focus on expanding its high-margin Personal Healthcare & Performance Oils (PHPO) portfolio while maintaining procurement discipline.
OPERATING ENVIRONMENT
* The quarter was marked by supply chain disruptions due to Middle East tensions, concerns around the Strait of Hormuz and crude oil volatility.
* Delays in supplies from Saudi Arabia prompted the company to diversify sourcing towards South Korea and domestic suppliers.
* Management believes its sourcing flexibility continues to be a key competitive advantage.
SEGMENTAL PERFORMANCE
* PHPO remained the biggest growth driver, backed by healthy demand from the personal care, pharma and healthcare sectors.
* Process & Insulating Oil (PIO) posted strong growth on the back of robust transformer oil demand from the power sector.
* Lubricants delivered steady performance and continued to provide a stable revenue base.
* Management expects PHPO and PIO to remain the key growth drivers going forward.
EXPORTS
* Exports grew 54% YoY and contributed 51% of consolidated revenue, up from 37% a year ago.
* The company now exports to over 100 countries and continues to deepen relationships with global customers.
* Export contribution is expected to remain around current levels, with export realizations continuing to be 5-6% higher than domestic markets.
MARGINS
* Gross margin per KL expanded sharply to ₹28,145, driven by better realizations, a richer product mix, efficient inventory management and agile sourcing.
* Management clarified that inventory gains were minimal, as inventory is maintained for only 30-40 days.
* Margin expansion was primarily due to selling prices rising faster than raw material costs.
* While Q1 benefited from favourable market conditions, management expects margins to remain healthy through most of FY27.
VOLUME GROWTH & GUIDANCE
* Management reiterated its FY27 volume growth guidance of 8-10%.
* Revenue growth is expected to outpace volume growth, supported by stronger realizations.
* Export momentum and continued expansion in PHPO are expected to drive growth through the year.
CAPACITY & CAPEX
* Manufacturing facilities are operating at around 97% utilization.
* Plants currently run on two shifts, with the flexibility to add a third shift as demand increases.
* Capacity remains fungible across product categories, allowing production to be shifted based on demand.
* The company is evaluating fresh capacity expansion plans, with an announcement likely over the next quarter.
BALANCE SHEET & CAPITAL ALLOCATION
* Company remains virtually debt free on a standalone basis.
* Consolidated debt is largely attributable to working capital funding for its UAE subsidiary, Texol.
* Strong cash generation is expected to fund upcoming capex, while maintaining the flexibility to raise debt if required.
GEOGRAPHIC EXPANSION
* The company continues to expand its international footprint through new entities, including South Africa.
* Management said the South Africa strategy is still evolving, with more details expected in the coming quarters.
* Customer additions and qualification pipelines remain healthy across both domestic and export markets.
INDUSTRY OUTLOOK
* Management expects the global specialty oils industry to grow at 5-7% CAGR and believes the company can continue delivering 8-10% volume growth.
* Growth will be supported by its diversified sourcing network, strong supplier relationships, global customer base and focus on value-added products.
* Demand for transformer oils is expected to remain strong, driven by continued investments in power infrastructure globally.
Note :- The summary can have a change from the actual figures given as official transcript hasn't come on the exchange.
No FOMO, but those who missed the March and June dips waiting for clarity on markets will not wait for the third (upcoming) dip. They will be fully loaded up this time. FIIs may or may not come. But choice is clear for other set of investors with 3-yr time frame.
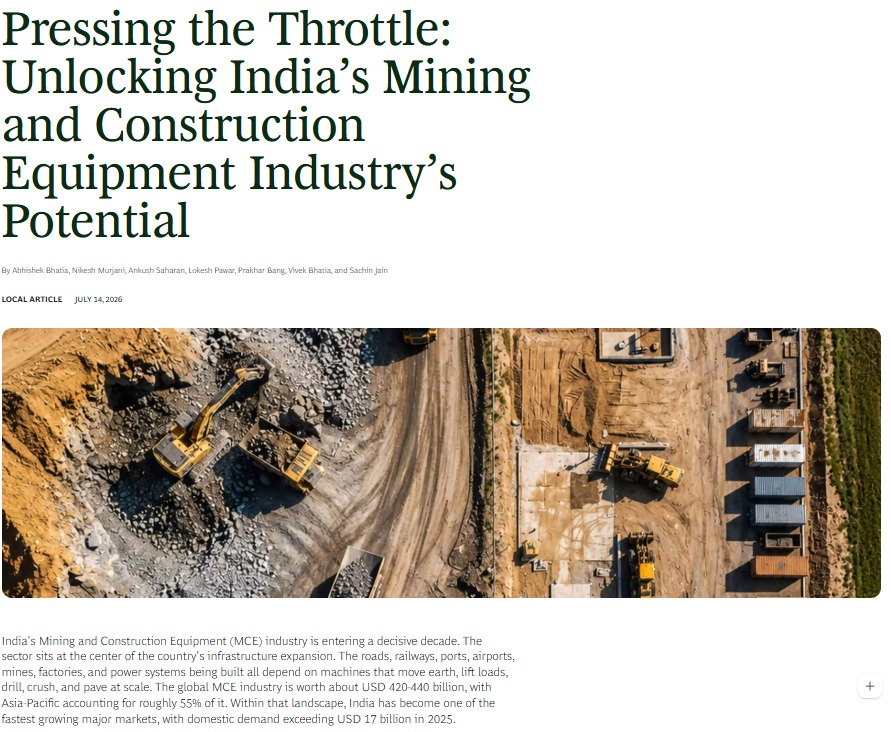
Very positive report on the Mining Construction Industry by BCG. Helps to understand the opportunity size of companies like TAURIAN MPS Limited and Tega Industries