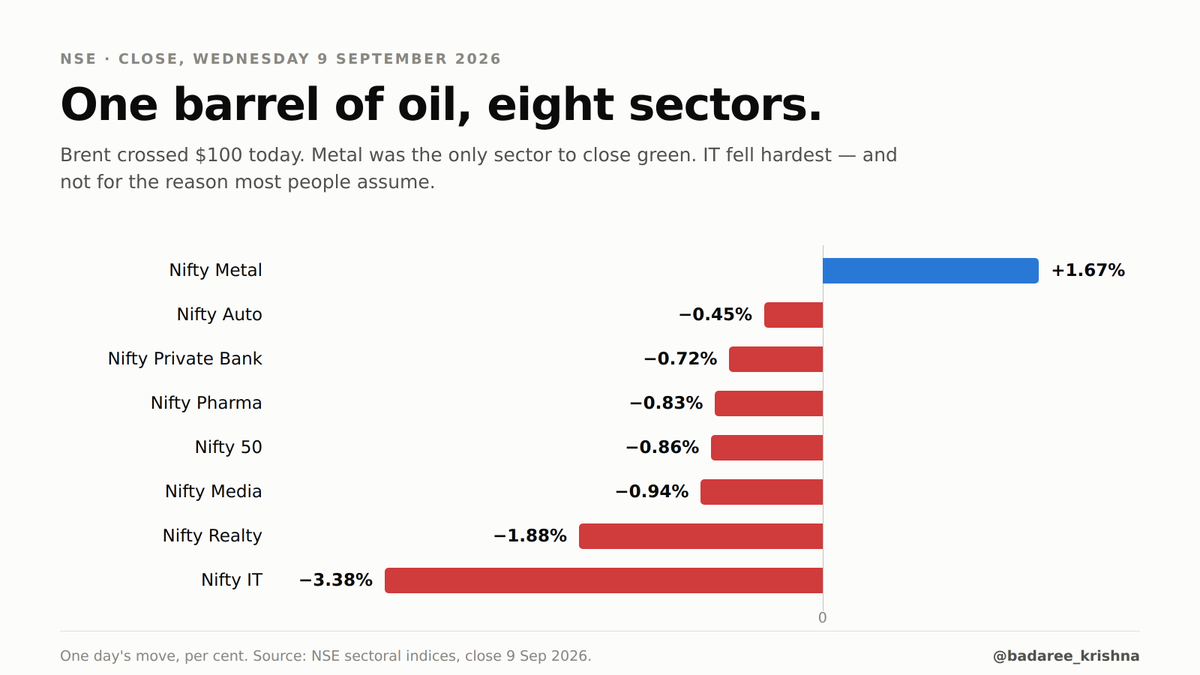
Brent crossed $100. Nifty IT fell 3.38% — the worst sector on the board.
IT doesn't burn oil. It bills in dollars, and a weak rupee usually helps it.
Oil at $100 means US inflation, rates staying higher, client budgets cut.
IT isn't an oil trade. It's a US demand trade.
Why pharma led:
US sanctions on Iran landed softer than expected.
Crude eased. Bond yields eased.
Money rotated out of metals and private banks into defensives.
Most days, the driver isn't domestic.
Nifty closed Tuesday up 115 points at 24,335.
Nifty Smallcap 100 closed red.
If the index was green and your portfolio wasn't, that gap is the story: money rotated into pharma, healthcare and PSU banks, and out of private banks and metals.
Index level ≠ market breadth.
RBI held the repo rate at 5.25% and raised its GDP forecast to 6.7%.
For fixed income, a stable rate environment shifts the driver back to carry rather than capital gains.
The case for locking in today's yields over a 3–5 year horizon deserves more attention.
A correction is a time to check allocation, not conviction.
Equity — seven down days, one up. Noise until it isn't.
Debt — repo steady at 5.25%. Accrual works quietly.
Real estate — illiquid by design. A feature, not a flaw.
Diversification hedges being wrong, not losing.
Nifty snapped a seven-session losing streak today, reclaiming 24,200.
Through that entire drawdown, July SIP inflows hit a four-month high of ₹31,961 crore.
The market flinched. The retail investor did not.
That divergence is the real story.