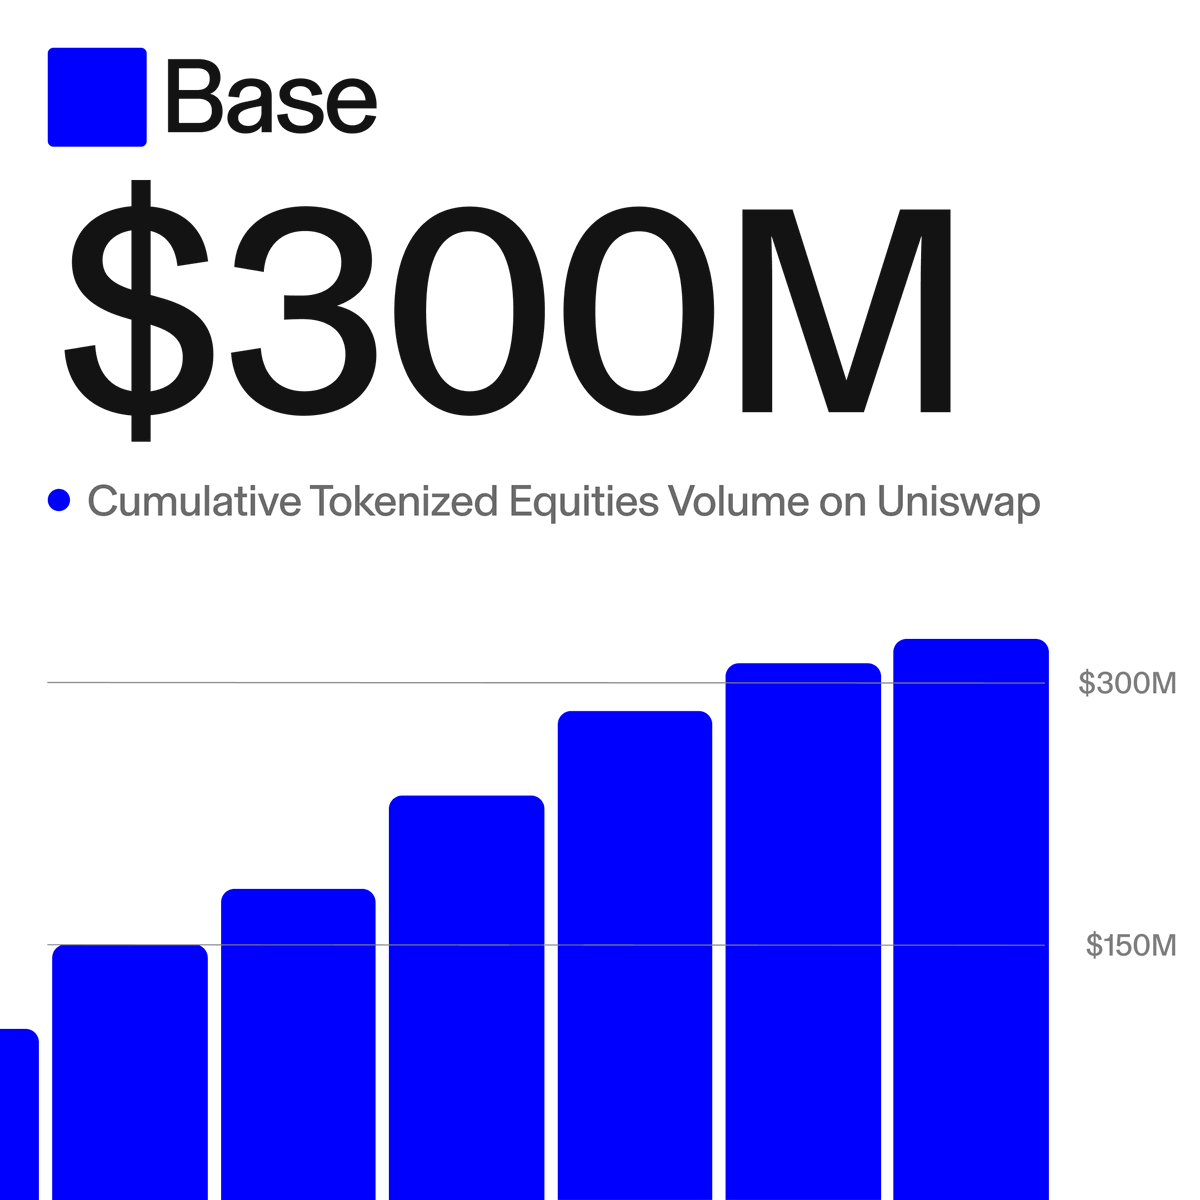
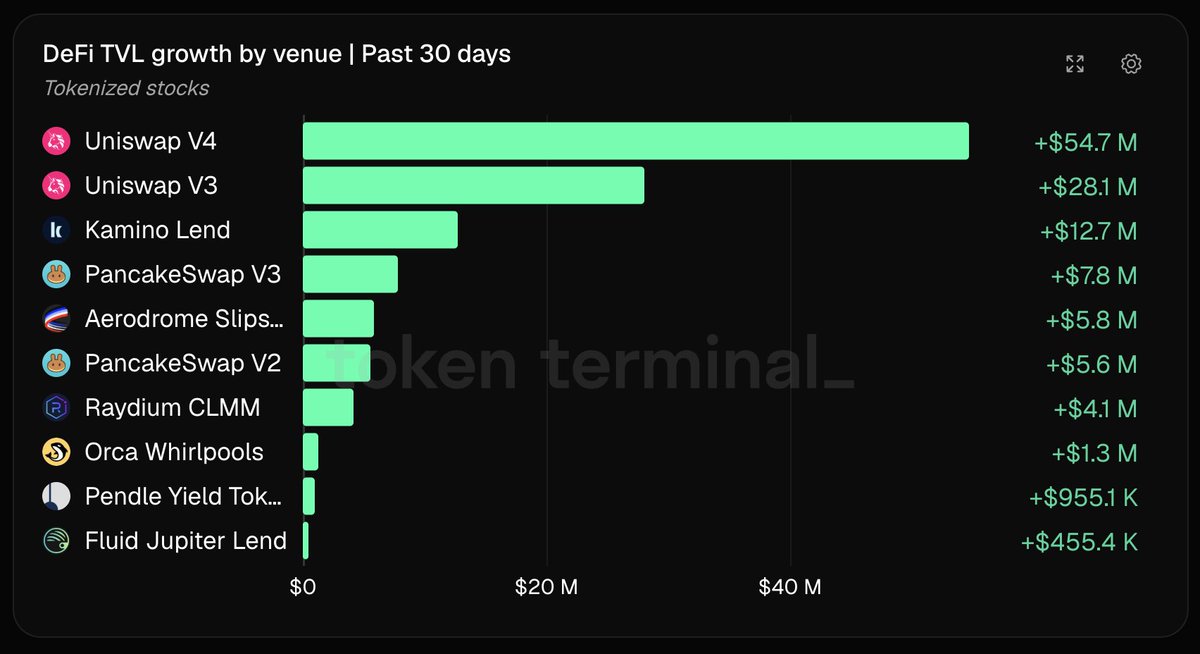
Uniswap led tokenized stock DeFi TVL growth over the past 30d
Value deposited into V4 increased by $54.7M and V3 by $28.1M, for $82.8M combined
Tokenized stocks are expanding beyond issuance into active use across DeFi
Great research piece put out by Geoff and Standard Chartered on the revenue story and growth mechanisms in place for @arbitrum and ethereum:0xb50721bcf8d664c30412cfbc6cf7a15145234ad1.
One part I wanted to double-click on and offer my personal perspective is with respect to buyback mechanisms or other "direct" value accrual to the token.
From my perspective, Arbitrum has the potential to tackle an unbelievably massive opportunity: be the execution environment for all financial services and the backbone of the programmable economy. This vision requires a lot of investment in technology and growth. A lot. If the entirety of the Arbitrum treasury was denominated in ethereum:0xb50721bcf8d664c30412cfbc6cf7a15145234ad1 or relied on the price of ethereum:0xb50721bcf8d664c30412cfbc6cf7a15145234ad1 to go up in order to accomplish that goal, Arbitrum would be introducing an immense amount of risk into its vision and plan.
Arbitrum has been amassing a very meaningful treasury of assets derived from its various revenue sources and totals approximately $125m today (outside approximately $400m worth of ethereum:0xb50721bcf8d664c30412cfbc6cf7a15145234ad1 in the DAO treasury). Multiple years of runway irrespective of token price.
These assets are all controlled by token holder via governance and can only be deployed or moved in accordance with tokenholder wishes.
Personally, I believe the Arbitrum treasury balance needs to grow a bit larger to ensure that the vision can be accomplished. Our partnership with Robinhood has proven the economics and the revenues can meaningfully scale. We need to be able to meet the moment.
That does NOT mean that Arbitrum should hold off on buybacks or other direct value accretive approaches to the token in perpetuity. It means that we just aren't there yet today.
The journey is just beginning.
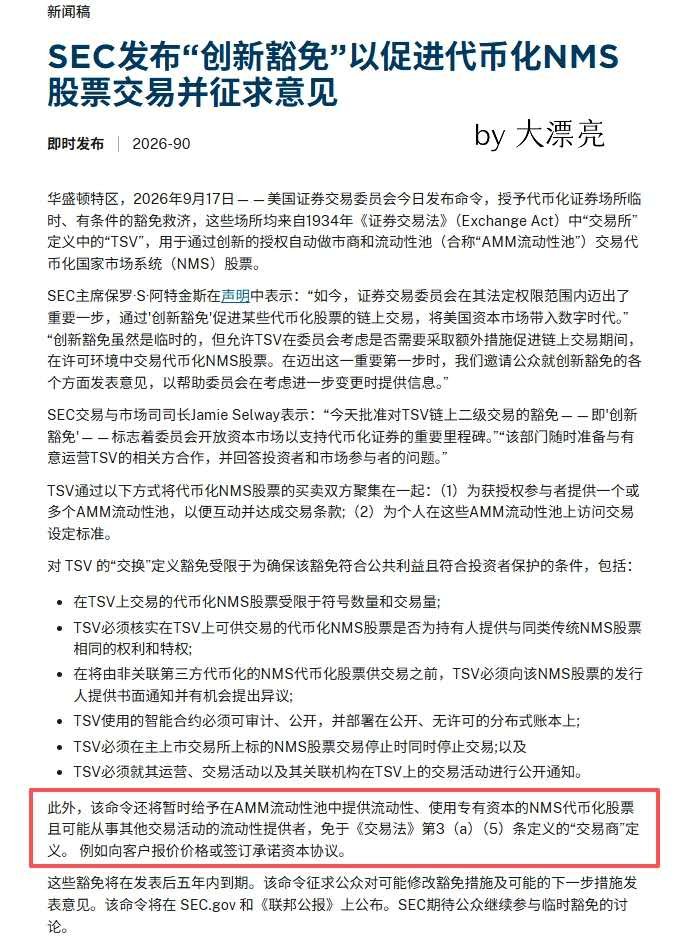
PREDICTION: The SEC just validated the AMM model for regulated securities. $UNI
That could eventually become a major catalyst for $UNI, but there’s a catch.
Permissioned stock pools could use Uniswap-style infrastructure to trade equities 24/7 with programmable liquidity.
But protocol adoption does not automatically create value for the $UNI token.
The signal to watch:
A regulated U.S. venue launches a tokenized-stock pool using Uniswap infrastructure, and directs fees or economic value back to the protocol.
If that happens, @Uniswap could evolve from a crypto exchange protocol into part of America’s capital-market infrastructure.
.@Uniswap v4 already flipped v3 in 30d volume and somehow the conversation is still mostly about hooks.
The bigger story imo is what happens when v4 becomes the liquidity backend and UniswapX becomes the router sitting above everything.
What I find more interesting is the capital efficiency.
– v4 did ~$39B volume over the last 30d against $1.05B TVL = ~37.1x monthly turnover.
– v3 did ~$33.8B over the same 30d against $1.5B TVL = ~22.5x.
– v4 takes ~54% of Uniswap volume on Ethereum.
→ v4 is moving ~1.65x the volume per dollar sitting inside the system.
Which makes more sense when you look at what is actually getting used.
8 of the 10 largest v4 pairs by 30d volume are stable pairs.
Uniswap itself did ~$43.4B stable-to-stable volume in Q2, and now v4 is getting purpose-built infra for exactly this flow.
@sparkfinance already moved $150M of stable liquidity onto v4.
Capital doesn’t necessarily need to sit dead inside an AMM 24/7 anymore just so it can be available when someone wants to trade.
Which also explains why TVL becomes a worse metric for judging v4.
UniswapX is the other tech I’m bullish on. Its fillers can use v4 liquidity, v3 liquidity, other DEXs or their own inventory.
What matters is v4 is making liquidity more programmable and potentially more fragmented. UniswapX is supposed to make that fragmentation invisible.
We can already see how useful that architecture could become on RH.
v2 + v3 + v4 + UniswapX all went live there from day one, and RH is now Uniswap’s largest 30d chain with ~$29B volume.
– v4 is doing ~$15.9B there, or ~42% of all v4 30d volume.
– ETH adds another ~$12.6B, BSC ~$4.4B, Base ~$2.2B.
We also got many projects building on top of v4 hooks, but it’s still early.
90k+ hooks have been initialized, but hooked volume was only around ~1% of v4 volume in most months.
But I really love some of the tech being built:
– @token_works: one of the few teams that actually proved v4 hooks can print, using decaying 95–99% launch taxes + automated fee routing to generate ~$51M cumulative strategy fees.
– @standard_rsv: an onchain central bank where a v4 hook on ETH/$STANDARD runs monetary policy itself, while fees rotate between gold/POL accumulation and $STANDARD buyback + burn.
– $IMD: @surfcoderepeat is building protocol-owned markets on v4 where the hook itself manages liquidity, burns excess inventory and routes value to stakers + future onchain compute.
v4 is winning because the same dollar of liquidity can do more work, while UniswapX can sit on top and hide the mess.
And maybe Uniswap’s moat now is owning the order flow and making every source of liquidity fight for it.
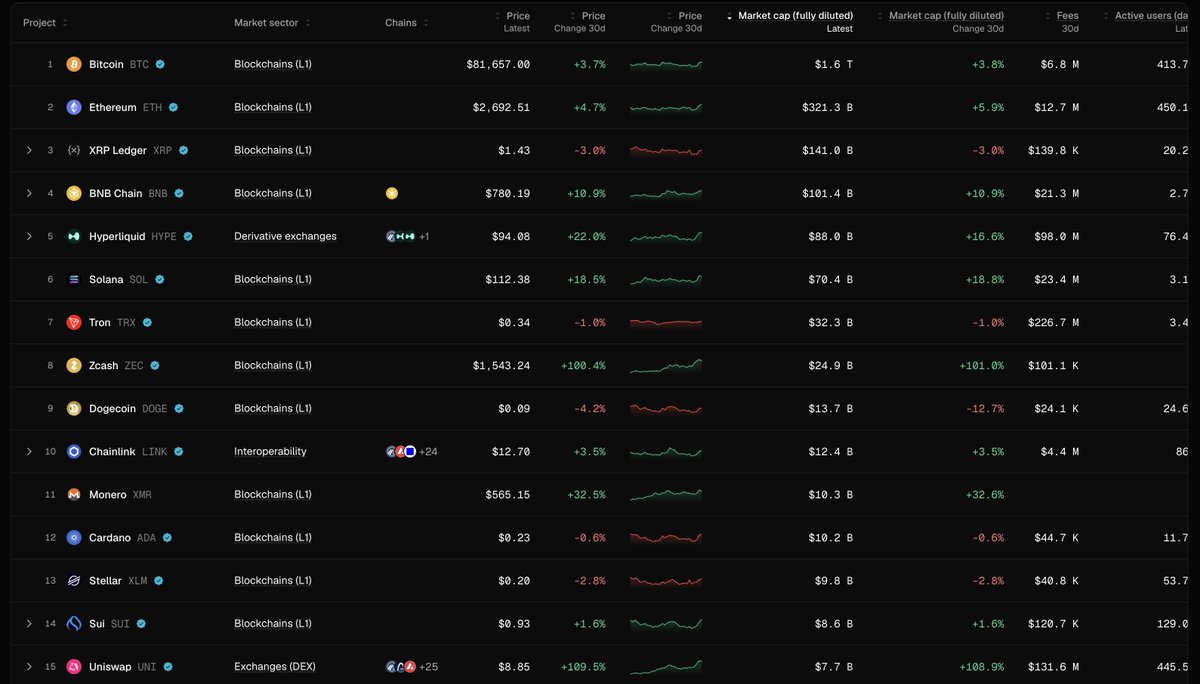
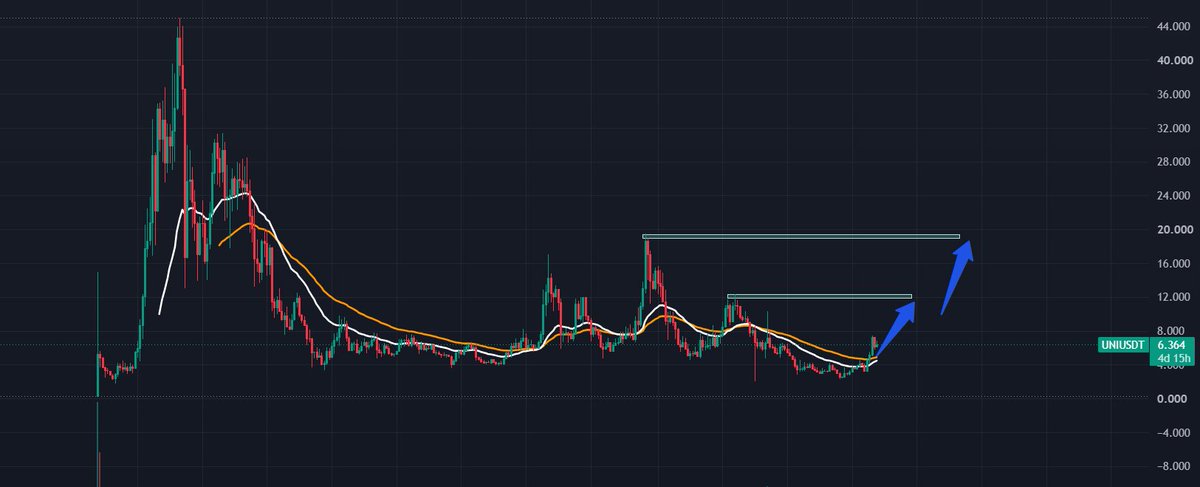
i feel like $UNI is just waiting for the market to stabilize again
Price is pulling back with the broader market, but the structure is still holding up pretty well and buying pressure remains strong, with $UNI even moving against the market’s downtrend at times.
Meanwhile, @Uniswap keeps expanding underneath:
>> $70B+ in protocol volume over the past month.
>> 1,700+ tokenized RWAs are now live on Uniswap.
>> @inkonchain has been integrated into Uniswap Web App, Wallet, and API.
Price looks like it’s taking a breather, but the expansion is not.
for me, this is the kind of setup that looks pretty good for adding more and accumulating while the market is still giving us time.
Once the broader market stabilizes again, i think $UNI will be one of the names that reacts pretty quickly.
how has Uniswap restructured $UNI’s value accrual mechanism?
$UNI didn’t go from governance token to dividend token.
@Uniswap rebuilt the entire value accrual path so protocol usage can remove $UNI from supply without ever paying holders cash.
That distinction matters a lot.
Because for almost 5 years Uniswap was one of the biggest fee machines in crypto while $UNI captured basically none of it.
Now part of the swap fees from v2/v3/selected v4 pools + net Unichain sequencer fees are collected into TokenJar.
TokenJar holds the actual assets collected from trading. ETH, stables, whatever tokens the pools generated.
Anyone can take those assets out, but to do it they need to pay $UNI into Firepit where that UNI is permanently burned.
So Uniswap itself is not market buying $UNI. Instead searchers decide when the assets sitting inside TokenJar are worth more than the $UNI + gas needed to claim them.
Usage creates fee inventory → fee inventory creates an economic reason to acquire/burn UNI → supply disappears.
Tbh the mechanism looked pretty mid during the first half of 2026.
Only ~$28.2M became protocol revenue from $357.6B volume across Jan–Jul 2026. Not exactly Hyperliquid-level token economics.
But the important thing is coverage was still rolling out.
– daily protocol revenue went from $114K pre-v4 flip to $325K after it.
– Robinhood contributed $170K on one post-flip day.
– latest 30d protocol revenue is ~$10.3M, up ~134% over the period.
That’s ~$124M annualized versus the ~$26–35M annualized numbers at the beginning of the year.
What actually printed:
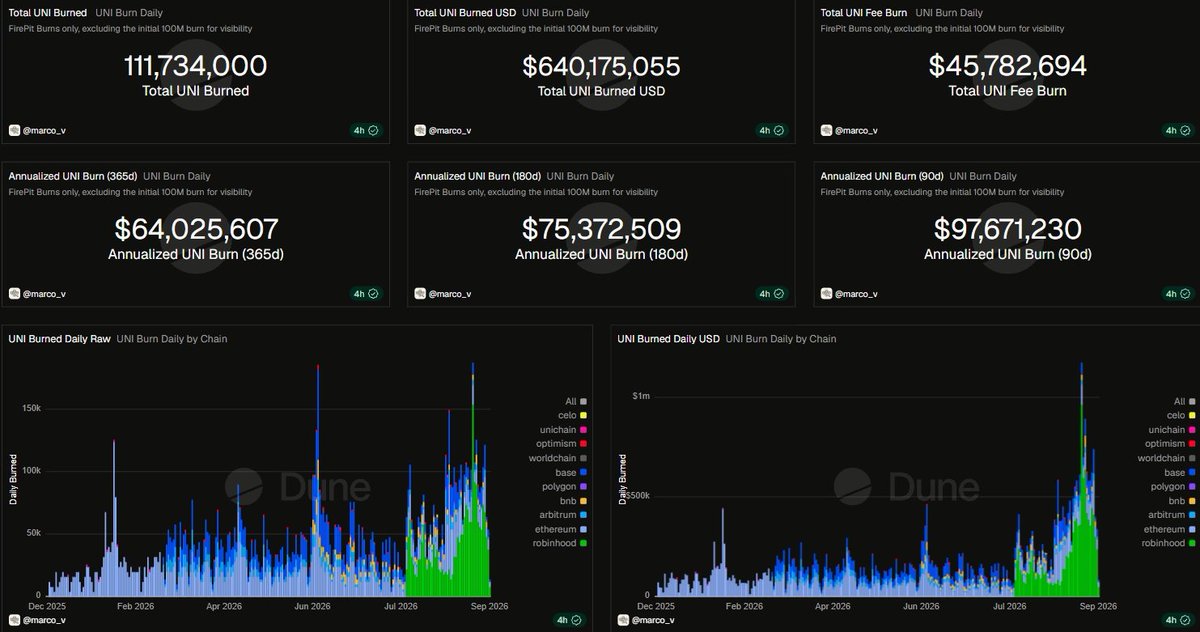
– 111.7M $UNI gone, 888.3M remaining.
– 11.7M of that is actual Firepit, the rest is the 100M gesture.
– L90D / L180D annualized ~$97.6M / $75.3M.
– annualized burn cleared $250M on Sep 8, heavily driven by RH.
Currently the pipe is finally large enough to matter versus a ~$4B mcap, and the Firepit run-rate now outruns the 20M UNI/year Labs budget.
I think design quality is high. They solved the constraint that killed every prior vote by not paying holders, burning float, wrapping the DAO, and making Labs a vendor.
Legally, it’s probably the constrained optimum for a US-touched major. Respect the engineering.
But magnitude is still mid. If we want this to look like HYPE economics, we’ll be waiting a long time unless they turn PFDA / UniswapX / the rest of v4 into real take.
DYOR.