@contang_o in the past couple weeks i've done several "vetting only" deals where charter essentially lifts stem and cma by putting the ship on subs and needs to show supplier or receivers rejection of the ship in order to fail/drop the ship.
@contang_o i think this is quite common across all segments in hot markets. every deal is subject to s/s/r/cma, suppliers approval, stem (the cgo-subject to enough merchandise), receivers approval, charterers mgmt approval. even on smaller ships...
@contang_o assume this is sparta? are they looking what products like usgc diesel are worth east? problem with looking at arbs in a vacuum are yes that may be "open" vs freight but is nwe the most profitable place in the world to sell ulsd net of freight?
@contang_o i think we just see trade lanes change for a bit. wti wont land into europe at current prices anyway as asia is bidding it up-hence td25 ffa dumping. asia will scoop every bbl and ship they can while AG is off limits. i dont think less cgoes matters if all the voys are longer
@contang_o is asian demand for oil elastic or inelastic? if asia's closest source of oil goes away, they will simply pay more for oil further away, not put up more solar panels. higher landed prices will kill *some* demand, but i think the ton miles would increase in net.
@MakaiMarine@NikolajWinther6@olaharaldmoen1 also, i would argue that as long as the venez crude comes back to the USG, in theory that original nap cgo just gets recycled back into another diluent stem and eventually has net zero effect on nap exports.
@MakaiMarine@NikolajWinther6@olaharaldmoen1 the diluent nap trade into venez tends to trade on dpp vessels, especially panamax vsls that owise tend to trade fuel oil. hellespont protector is last dpp. it doesnt require a last clean boat. this primarily puts pressure on freight for usg & caribs fuel oil.
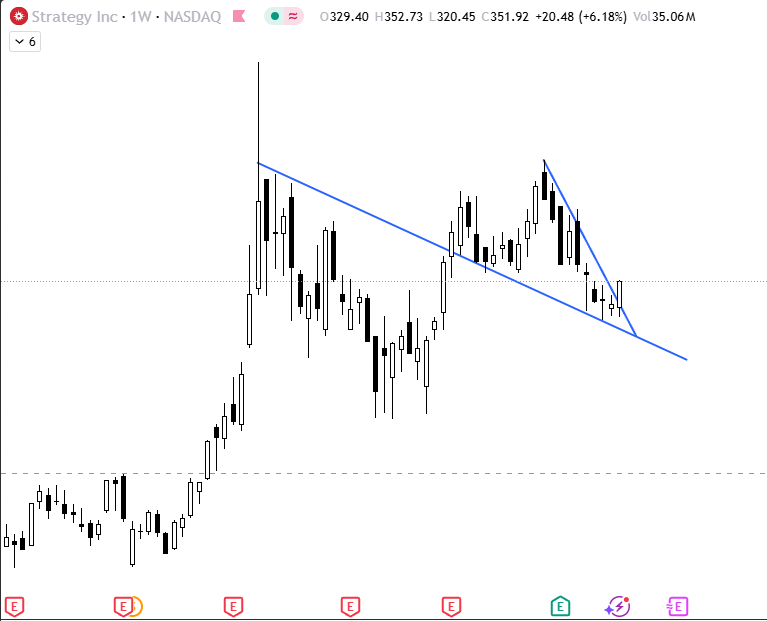
@Prof_heist i think if it breaks down and closes below that ely nov low then yes. so far, still in a channel doing an odd asymmetric head and shoulders looking move.
@Big_Orrin this is a very simplistic scenario to outline a point, but if china is buying less ESPO and more WTI, isn't there an argument that there necessarily has to be more oil on the water to supply the same amount of demand... like 10x more.
@2_contango most deals go subs with no owners subjects, just subject to s/s/r/cma (suppliers, stem, rcvrs, charterer's mgmt approval). if owners are pulling ships that are already on subs, that is a very extreme/naughty move. havent heard any ships being pulled yet or owners subs given...
@2_contango i still think td3c can be the rising tide that lifts all other mkts, but it doesnt feel like there is strong oil demand pulling from anywhere just yet, just bullish sentiment from owners.