@DavidOndrej1@grok how does Serviceware $sjj sit with the claims and direction of this article? The AI native ESM platform, is it well built for the modern AI agent era?
Serviceware $SJJ increases guidance for FY
Sales to grow 10-15%
EBIT/EBITDA to increase "significantly" vs earlier "slightly"
Contrast vs turbulent Servicenow development
Good add after the Forrester ESM "Strong Performer" recognition earlier
@NordicOpps So yes, there are ifs.
If growth stays double digits
If mix is same or better (more own saas)
Then it should be possible to have 10%+ margin q4 2026 and >10% full year 2017
Not the easiest case, but it is cheap and it can take off
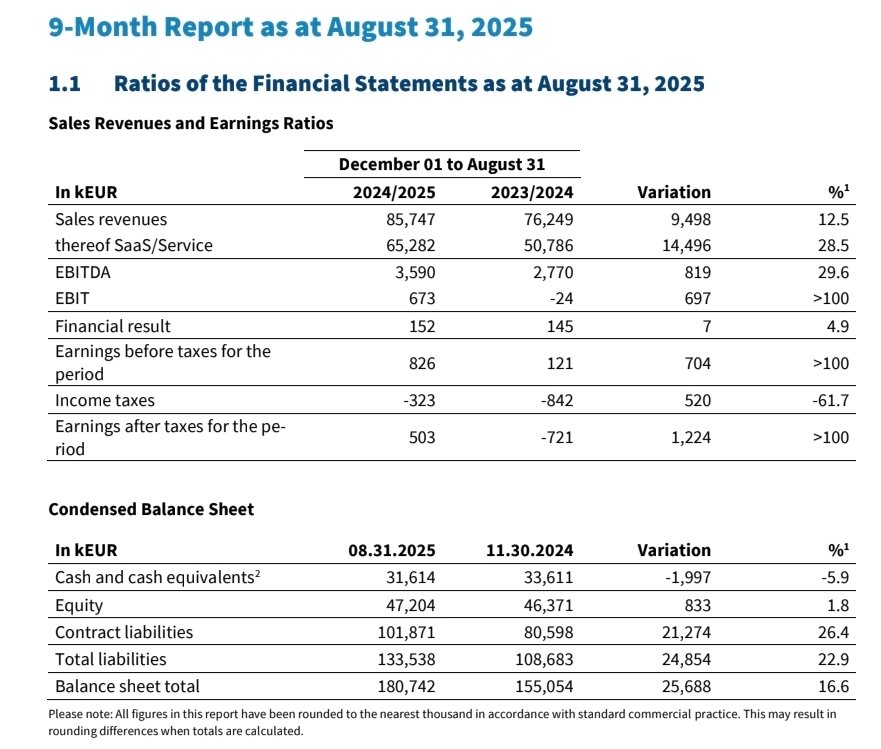
Serviceware $SJJ Q3 25 was released on Friday
Sales growth up to 17% on q3, driven by license sales (down H1, now up 9%)
Strong licenses caused a margin surprise --> black figures!
Expecting strong scaling in profitability 2026
Strong order growth, back at over 100meur
@NordicOpps Agreed. They need to open the 3rd party (crowdstrike etc) sales. Then we know the margin levels and drivers to which the case scales towards when it grows
Margins wont most likely be double digits 2026, but scaling is likely to accelerate. Due to faster growth and better mix
Cash is 3meur lower qoq, probably due to some larger contract prepayments
Annoying, that they do not comment nwc development
Over time however, Serviceware operates at strongly negative working capital due to heavy customer pre payments
@siyul Embracer Group $embrac
Heavy insider buying +new buyback program
Spinning extremely profitable Coffee Stain in Dec 25
Remaining company owns IP's worth multiples of the ev
(Owns: Lord of the Rings, Tomb Raider, Remnant, Kingdom Come etc.)
@darkfloatz Yes always. But its a small company with handful of orders per Q
Q1 was crazy good, so there probably was long durated deals/payments received
As long as the current contract liabilities grow from Half to Half >10%, im happy (they only split it in H1 and H2)
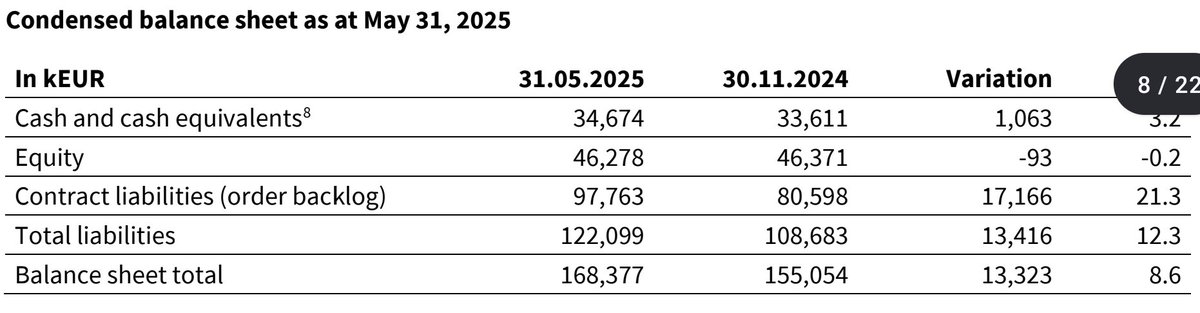
Serviceware $SJJ H1 2025 out today
Solid 10% sales growth, but it hides the >40% SaaS growth in declining service and license sales
EBIT is positive, and has accumulated by 1 MEUR to over 34 MEUR
When service and license are done with, this should scale like a proper software
There isnt much licenses (5MEUR) or consulting (6 MEUR) left to get rid of
These are 80-100% gm in Serviceware accounting, so the lowered GM will start to recover after these are insignificant
Outlook was good and also promised growth in FY26
Contract liabilities (orders) grew 21 % yoy, but decreased slightly qoq
Book level is great, and we should expect to see new bumps in the upcoming quarters
Serviceware major deal #7 YTD and more
https://t.co/SuLUnjcROh
AI platform SaaS order intake 7digits just in Apr-Jun 25
$SJJ reporting Q2 July 29th
Solid momentum. Already more deals vs FY24
Orderbook Q1 25 was 102 MEUR (+26% qoq)
Why havent they increased sales guidance?