🚨BREAKING: The Information reveals that Anthropic has quietly signed a previously UNANNOUNCED multiyear cloud deal with IREN, the former Bitcoin mining company turned AI infrastructure provider.
IREN disclosed an unnamed frontier AI customer in August. The report now identifies Anthropic as a customer.
The Information also estimates Anthropic's 245 MW Louisiana data center could generate $1.3 BILLION in monthly revenue at full inference utilization, against just $200 million in monthly chip rental costs, implying an 85% inference gross margin before training and other expenses.
$IREN: What Wall Street Will Do
Let me start with the conclusion: after despair comes a reversal.
IREN has been consolidating for a year. During that year, the company accumulated more milestones than at any other point in its history. There are at least 20 significant developments to list, many of which are not just company milestones but industry milestones as well. This is a company with exceptionally strong execution. The problem is that what it is doing does not produce immediately visible results. Take its 5.8 GW of secured grid power, for example. This required years of preparation, and its scarcity value will become increasingly apparent over time. Many people do not understand just how valuable this confirmed 5.8 GW really is. IREN is the only neocloud company that discloses power capacity backed by PPAs. Not only is its power supply supported by legal agreements, but its sites also possess multiple forms of scarcity value in terms of location, scale, and access to green energy. Time will gradually reveal the distinctive value of these assets.
IREN could have started monetizing these assets right here and now. That would have been relatively easy for the company. But just as it demonstrated foresight years ago by surveying locations around the world and securing high-quality sites, its management team has concluded that it can pursue greater and more sophisticated opportunities over the longer term. So, just as IREN laid the groundwork for its global site portfolio years ago, it is now planning something much bigger. This is a complex, integrated engineering undertaking involving multiple external partners, far beyond what was involved in planning several gigawatt-scale sites back then.
IREN follows a slow-first, fast-later model. Investing in IREN requires patience, but even more importantly, it requires a deep understanding of the company. The issue is not that the company communicates poorly or cannot tell its story. Rather, it is the complexity of the integrated engineering undertaking itself, which spans an exceptionally broad range of disciplines. Management has already provided a great deal of information, but understanding the interactions and causal relationships among the various elements, and how they contribute to building a unique moat, requires investors to conduct their own in-depth research and learning.
There are many neocloud companies, but IREN stands out as the one with the greatest concentration of high-quality, unique advantages. I can name at least 10 of them off the top of my head, each of which other companies can no longer realistically replicate. These are essential ingredients for differentiation and the development of a powerful competitive position. (If you have invested in IREN, try to see how many you can name yourself.)
Wall Street has historically paid the most attention to companies with multiple high-quality, distinctive advantages. Once those advantages are progressively demonstrated in practice, such companies also tend to command the highest valuations. Do not assume that IREN's year-long consolidation means Wall Street has been ignoring it. Institutional investors approach a company in stages. Once they establish that its multiple distinctive advantages are real, they will certainly study every aspect of the business more deeply than ordinary investors do.
Given IREN's slow progress in the early stages, sufficient patience is essential. After IREN announced so many milestones this year, its recent share-price performance has completely extinguished the once-high expectations of many investors, with sentiment even turning negative. This kind of market behavior is already approaching the classic setup for a reversal.
Let me discuss two recent developments.
Semianalysis's negative assessment
Semianalysis gave IREN's Canadian sites a negative assessment. Setting everything else aside, the facts are straightforward: there have been power outages, and redundancy has been insufficient. There is no need to explain away the causes. Those two facts alone are enough to support criticism of the company's execution and cloud infrastructure capabilities.
At the same time, however, Semianalysis acknowledged that Childress and Sweetwater are substantially better. Overall, IREN's Canadian sites are being upgraded, and they account for only a small proportion of its total capacity. Investing has always been about the future. The two much more important sites, both far larger in scale, have received positive assessments.
Yet problems at one relatively small site triggered a massive sell-off in the stock. The force driving that sell-off came not from a deterioration in the company's overall fundamentals, but from negative investor sentiment.
Wall Street will make full use of that sentiment to acquire shares with substantial underlying value. A little rational analysis makes the distinction clear: how can problems encountered during the upgrade of one small site outweigh the strength of the company's overall technical capabilities? The major sites have received validation from both Microsoft and NVIDIA. More importantly, IREN remains the sole partner for NVIDIA's flagship AI factory under the DSX framework.
The impact of renewed interest-rate hikes on financing capacity and economics
This is a negative development for the entire industry, and the pressure is greater for a fully owned, vertically integrated model like IREN's. The resulting share-price decline is understandable. However, a closer look suggests that this round of rate hikes is more likely to be temporary, with a limited overall impact. It is a countermeasure against persistent inflation, rather than a response to an established upward trend in inflation. These are fundamentally different situations, even though the market's short-term reaction has been intense.
AI industry development is a core driver of US economic growth. Short-term volatility does not change that underlying trend.
With stock market indices repeatedly hitting new highs and other neocloud stocks surging, IREN has spent a year consolidating before declining recently as sentiment collapsed. Based on my long-term experience, this could well represent the final stage of the current trend. Shares sold under the pressure of negative sentiment are rapidly accumulating in the hands of institutions with deep research capabilities and the patience to wait.
I have compiled the figures, and institutional ownership of IREN has continued to increase over the past year. Particularly notable is the prominence of institutions with a long-term, conservative investment orientation, including banks and sovereign investment institutions. Compare this with NBIS: institutional ownership has also increased, but hedge funds with shorter investment horizons and growth-oriented capital account for a larger share. In a nutshell, long-term, patient capital represents a relatively large proportion of IREN's institutional shareholder base.
IREN is working hard to realize its ambitious plans. Veteran data center expert @brianfry01 has pointed out that existing data center architectures are not suited to AI factories and require structural modifications throughout the system. Under these circumstances, the faster companies rush ahead today, the more constrained they may become in the future. IREN, by contrast, is focusing on this fundamental industry pain point and developing standardized solutions.
Liquid cooling will be a technological transformation of decisive importance. Veteran IREN progress investigator @FransBakker9812 has predicted that IREN will bring about a major transformation in this field. Given John Gross's position as Vice Chair of ASHRAE's liquid-cooling standards committee, along with his extensive experience in thermal architecture, engineering standards, and the design and commissioning of Tier IV data centers, there is a solid basis for expecting such a transformation under the leadership of an industry-recognized liquid-cooling authority. This is absolutely worth looking forward to.
IREN is deeply immersed in the practical implementation of fundamental changes to AI infrastructure. Its key partners are AI industry leaders NVIDIA and Dell. Dell industrializes NVIDIA's compute architecture into standardized, mass-replicable liquid-cooled server modules, upgrading compute deployment from something assembled piecemeal in server rooms to factory-scale production.
IREN's relationship with Dell dates back to the company's early days as a publicly listed business, and the collaboration runs deep. This year, Dell has already been revalued by the capital markets. The engineering integration IREN is undertaking is even more complex. Many of NVIDIA's and Dell's concepts and initiatives need a physical factory in which to be implemented. That is precisely the role of Sweetwater's flagship AI factory under the DSX framework.
The transformative significance of what this factory could bring is enormous. It is on an entirely different level from the question of whether IREN signs orders, or with whom it signs them. Many people have yet to pay attention to this. This is the real anchor that could eventually drive IREN to command a super-premium valuation.
Today, IREN announced that its subsidiary Mirantis has completed NVIDIA certification for the GB200 system and launched a full-stack AI cloud virtualization solution that combines performance with isolation. This is significant news and marks progress in a fundamental transformation of AI infrastructure. Understanding the full implications of this development requires a substantial base of technical knowledge. Anyone seriously investing in IREN should make an effort to understand its deeper significance.
I have consistently disagreed with the argument that IREN's poor share-price performance this year is a management communication problem. People who hold this view underestimate the capabilities of the capital markets. Capital markets are professional value-discovery mechanisms. Over the long term, they will not overlook any genuine gold mine. They simply behave differently at different stages.
Nor will more intensive management communication fundamentally change the situation. What the market ultimately follows is the development of the industry itself. Most of 2026 has been a preparatory phase, and it is entirely normal for the stock price to show little progress during such a period.
The encouraging news is that the results are gradually becoming visible, and the payoff is now within sight. Multiple major developments are expected to emerge within the next 90 days.
Further selling remains possible. But the most likely turning point may come precisely when despair is at its deepest.
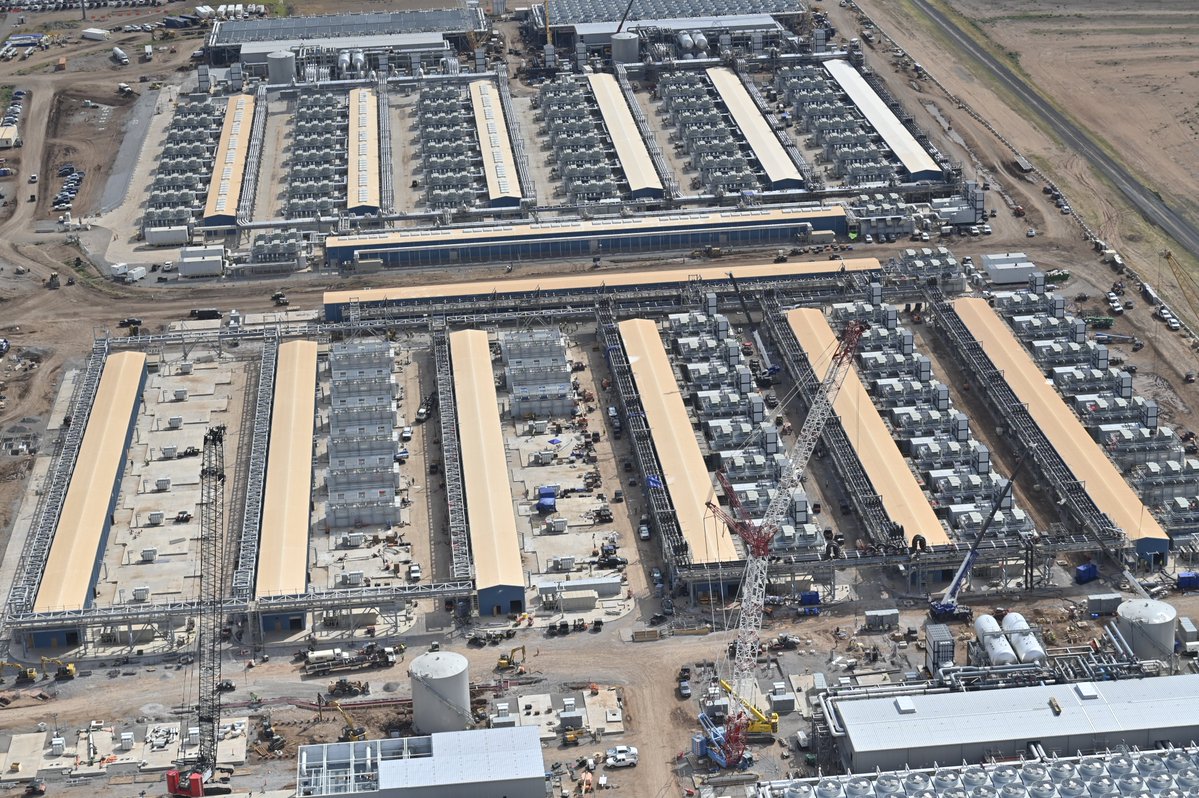
Today I will be educating you with some construction progress at $IREN sites in Texas.
Additionally, I will try to explain why the current strategy is the optimal one, and attempt to clarify some misunderstandings around the company and its trajectory.
$IREN: Addressing the Semi-Analysis FUD on Reliability
What's the Issue?
I heard of these issue in August and the only customers that $IREN has had long enough to report "multi-day power outages, network upgrades, storage failures, air quality controls leading to link flaps, XIDs everywhere" are FireworksAI and TogetherAI at Prince George. Mackenzie is undergoing GPU commissioning as we speak (1) so I don't know why @SemiAnalysis_ mentions Mackenzie having customer problems already when there are no customers there yet.
What @dylan522p says is true but convinently omitting critical industry context makes this a cleverly disguised Semi-Hit-Piece. I had heard that TogetherAI filed this complaint to IREN and Dylan was able to obtain the information from TogetherAI's CEO. I was also told that Dylan is personal friends with TogetherAI's CEO and are from the same region in India and speak the same Indian dialect which is how Dylan is able to get the info.
I will show that these are industry wide problems and the affected customers renewed despite these issues.
First Industry Fact
First, the most important fact that @SemiAnalysis_ conveniently leaves out is that on August 27, 2026, it was confirmed that “Together AI and Fireworks AI have both renewed and expanded” (2).
Despite all these problems, why did TogetherAI and FireworksAI renew? Let's look at the rest of the industry facts.
Second Industry Fact
Second, I will address the most alarming sounding issue: multi-day power outages. Down-time happens to everyone in the industry. @SemiAnalysis_ Platinum Cloud, $NBIS, had a outrage spanning August 19-August 20, 2026 (3). It's not narrated by SemiAnalysis in hit piece voice but the results are similar: "a storm-related event affected the building of the data center facility hosting the us-central1 region, taking the facility’s building management system offline and shutting down the chilled-water cooling loop. With active cooling lost, the data halls overheated within roughly two hours, and servers, network switches and rack power systems began shutting down on thermal protection. This caused a region-wide disruption of us-central1 services: GPU and CPU compute, external network connectivity for virtual machines, object and block storage, Managed Kubernetes, Token Factory, managed platform services, and the regional API and console endpoints" (3).
"Storm-related event" makes NBIS outrage explained. SemiAnalysis's biggest bias is that they conveniently leave out the reason for IREN's outraged: BC Hydro's grid had a brown out. That's why TogetherAI renewed, not because they were okay with unexplained, random multi-day power outrages. At the time, IREN did not have enough backup generators in BC since generators produce significantly more pollution than a hydro powered grid and are hard to obtain licenses for. By March, IREN was able to obtain license to put generators for all of PG and multi-day power outrages will no longer be a problem. IREN has designed Childress and SW1 with full N+1 backup power since MSFT which requires a higher uptime which is why SemiAnalysis says those sites "look much better".
Third Industry Fact
Third, let's address the rest accusations: "network upgrades, storage failures, air quality controls leading to link flaps, XIDs everywhere". Using fancy technical terms without explaining them is a hallmark of a hit piece, so I'll give definitions. Link flaps means a network connection is going in and out. XID is an error code logged and reported by Nvidia GPUs.
Link flaps are common: SemiAnalysis Platinum Cloud $CRWV (4), Silver Cloud Lambda (5), $MSFT (6) all had 2hr15m (4), 5hr14m (5), 4h57m (6) network out rages due to link flaps this year. Why? Because when optical networking links and transceivers collect dust particles the connection can be interrupted. SemiAnalysis conveniently uses "air quality controls" to make it sound even more scary.
"XIDs everywhere" sounds scary too but they have a much larger frequency on GPUs than other compute types. $META had a paper showing that they had 419 XIDs in 54 days on their infrastructure. No other AI Cloud is this transparent about reporting problems but $META blog is one of the most honest tech blogs out there bcause META culture is "Move Fast and Break Things".
Network upgrades or other control/management plane upgrades do cause problem from time to time. AWS had a DynamoDB DNS defect (8) and GCP had a policy update trigger crashes globally (9).
Storage outrage is the most outrageous accusation as those are the most common across both GPU and CPU Clouds. In a completely separate incident from the storm-incident, NBIS had a storage outrage in 2025: "we had an outage of the S3 service in the eu-north1 region triggered by a steady increase of migration traffic accompanied by unexpected behavior of the program" (10). Storage downtime are not typically reported these days but in the past generation, they use to more commonly reported by GCP (11), Azure (12), AWS (13). Storage is check pointed and there is often none to very little data loss.
Managed Services
Don't know why SemiAnalysis has such strong shade on "Managed Services". It's a twist of the facts. IREN has no managed services but Mirantis does. Mirantis provides managed services with 99.99% uptime SLA (15) to customers like Adobe, Cornell University, PayPal, MetLife Insurance, Royal Bank of Canada (14). With the Mirantis acquisition closed, I don't know why SemiAnalysis says that IREN advertisement of managed services is misleading, NBIS is advertising the results of their acquisitions on full blast.
Conclusion
@SemiAnalysis_ gives a master piece lesson on how to write FUD pieces without straight up lying but cleverly crafting context. I unravel their knots for you.
So if the situation isn't clear, I'll spell it out for you once more.
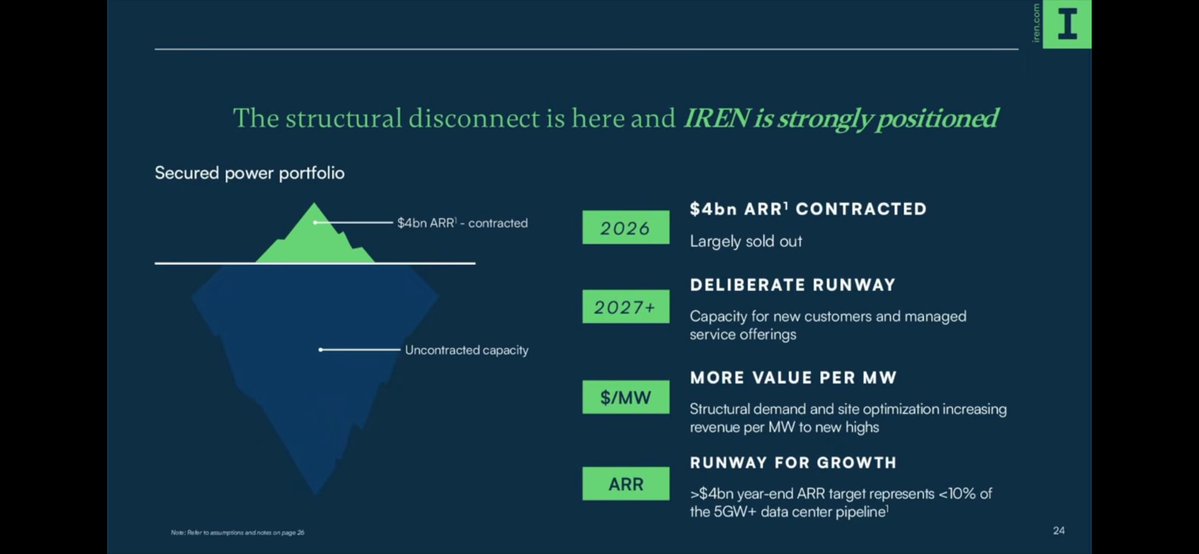
- $IREN will build their 2026 ARR capacity inside the given time frame. (Source: me).
- Iren will monetize their 2027 capacity (Source: demand environment).
- Iren IS CHOOSING their 2nd cycle clients now, THIS IS A POSITION OF STRENGTH YOU FUCKING RETARDS.
- Stickiness is baked into the cake you idiot hedge funds.
Have a good weekend.
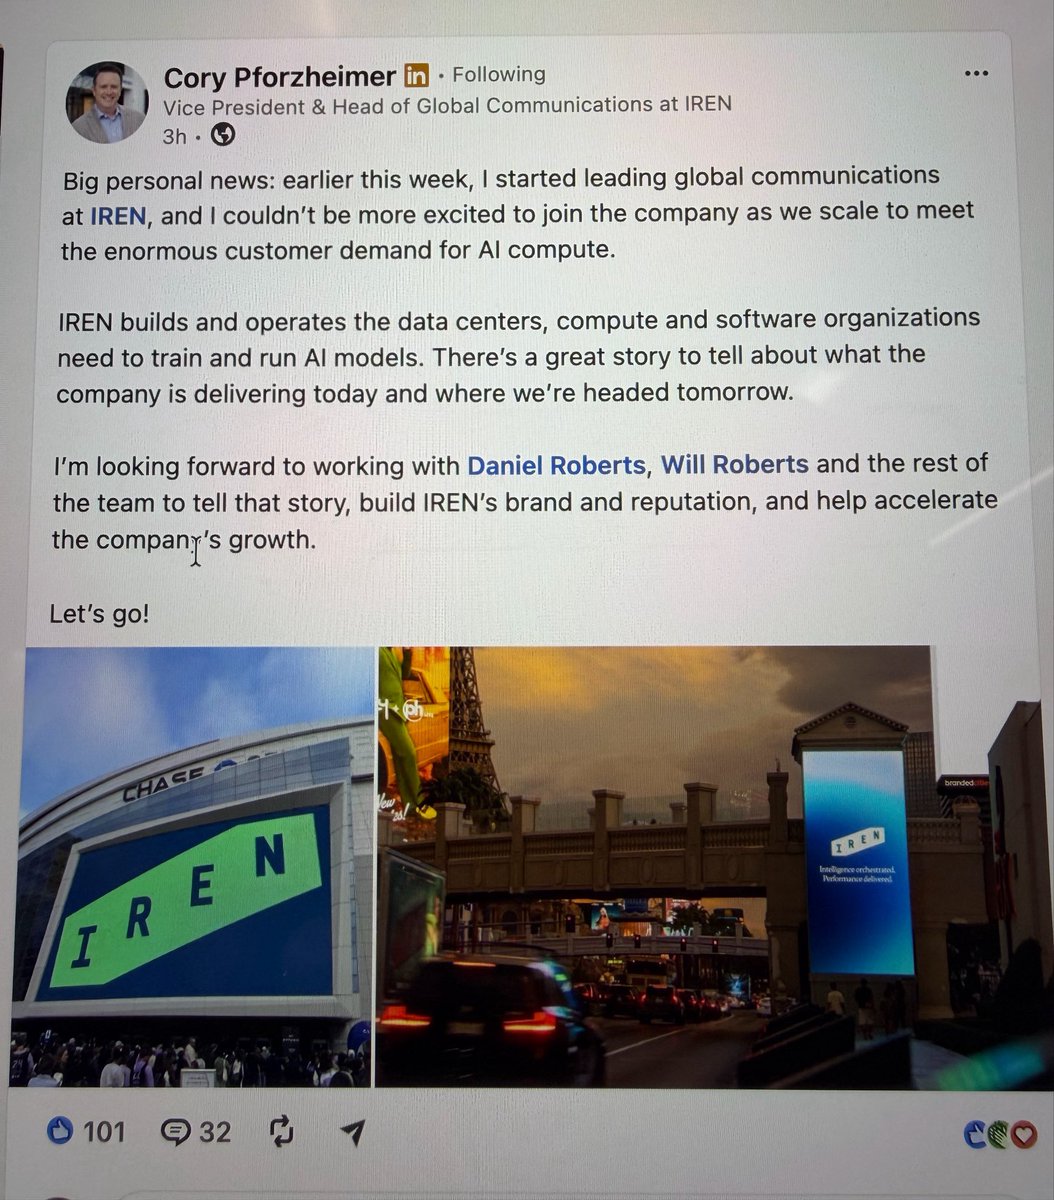
IREN keeps landing great execs. Cory joins from Intel, Equinix, HP and Yahoo. Comms has been a weak spot for years, glad to have him in the seat to help tell the story! @FransBakker9812 $IREN
Great to welcome @kentpdraper, Chief Commercial Officer of @IREN_Ltd on the Power Analysis podcast to discuss highlights from their 2026 FY and provide the outlook for 2027 and 2028, plus much more!!!
➡️ https://t.co/BMtTwGKMX1
JUST IN: $IREN CCO Kent Draper says IREN has already "sold out" their 2026 capacity
"Demands still far exceed supply. That's great for us as a provider because if we can get compute online, there will be a revenue stream."
@XCapitalMgmt@danroberts0101 Indeed! We are still early! Next year belongs to IREN, and rerate will happen in a sudden that most bears has no time to recover!