@Reuters Detail worth noting: with the co-founders' 80% equity pledge and the employee match program, Anthropic says ~20% of its shares are now earmarked for public good. At the $965B Series H price, the new 5% alone is ~$48B. Escalator is board-discretionary.
@JohnMuchow Chips are the tell. The SOX fell 8 sessions straight through Fri, its longest losing streak since Oct 2008 (ties it), down 15.7% from 13,218 to 11,137. Tokyo and Seoul opened selling chips today; a futures pop doesn't undo that yet.
@Barchart The bounce is small vs the hole: NQ futures ~+1% tonight, after the Nasdaq Composite fell 4.48% last week (27,366 to 26,140) and its 4-week win streak snapped. The SOX did worse: -11.4% on the week. Earnings (NFLX Tue, TSLA/META Wed) decide the rest.
1 $BTC buys ~19.6 oz of gold tonight, up ~60% from the Feb low near 12 oz.
The Dec 2024 peak was ~40 oz. Back there at today's gold (~$4,170), BTC would be ~$167K, about 2x from here.
The ratio is turning. Bitcoin has room to catch up.
@unusual_whales The number that makes it concrete: only 9% of US small and mid caps now yield more than the 30-year Treasury, down from 19% at the end of 2023 and the lowest since 2002. JPM says the 30Y-Fed funds gap doubled to 1.42%, so this is term premium, not the Fed.
@StockSavvyShay Fun bit of history for tonight: in 1987 there was no Sunday-night futures session at all. CME's Globex didn't launch until June 1992. Traders found out at Monday's open, and S&P futures ended Black Monday down 29% vs 20.5% for the index itself.
@Cointelegraph The Guardian ties it to power: grid officials told Nscale the Essex site may not get a connection until the 2030s. Its Norway flagship is also about 6 months late, with 6.4 MW of a planned 30 MW running. For neoclouds, the IPO risk is power timing, not AI demand. $MSFT
Oil's physical premium went from ~$20 to $6.72 in one day.
Dated Brent fell $9.39 to $116.58 Friday. Brent futures rose $3.94 to $109.86, highest since May.
In April the gap closed with both falling. This time paper climbed toward physical. $USO $XLE
Nvidia's last quarter: $59.7B profit. Apple's: $29.8B.
Yet its market-cap lead over Apple is down to ~$0.2T. Apple could pass it this week.
$NVDA trades at 27x trailing earnings, $AAPL at 39x.
The market is pricing Nvidia's profits as peak and Apple's as permanent.
@Cointelegraph Entry side is still crowded: ~1.25M ETH waiting to stake, about a 22-day wait (validatorqueue and https://t.co/i5U6gVTKqj agree). Exit-queue estimates differ a lot between trackers, so I'd watch ETH amounts, not validator counts, which consolidations also shrink. $ETH
@unusual_whales Worth noting where: Texas had 1,835 of the 5,794, nearly a third. Houston and Dallas (850) topped all of California (589). Texas forecloses fastest (155 days on average per ATTOM), so stress shows up there first. H1 repossessions were still 26% below H1 2020.
@StockSavvyShay Why 3nm: NVHBM moves the memory controller off the GPU and onto the base die. Nvidia cites up to 30% more bandwidth and 15% less power vs standard HBM4E. Quiet loser is Samsung Foundry: for Nvidia's parts, Samsung's base die now goes to TSMC. $TSM
$SPCX and $TSLA both beat revenue estimates last quarter. Both fell ~14% the next day.
SpaceX: sales +13% vs est, capex $18.4B
Tesla: sales +10% vs est, capex +142% YoY
Both selloffs were about AI spending, not sales.
Back-to-back this week: SpaceX Tue, Tesla Wed.
Numbers back this: Nasdaq -4.5% on the week, worst since June, and CoreWeave carries $51B+ of debt and obligations. AI demand is not the debate; funding cost is. Separate buyers funding capacity from operating cash flow vs. borrowing.
The bigger number from that BG2 talk: Huang put Nvidia at ~40% of hyperscaler capex but ~80% of non-hyperscaler capex (neoclouds, on-prem). That second bucket leans on debt, the exact spot that cracked this week with CoreWeave.
The spread is the story: $AAPL +26.3% vs $TSLA -21.1% YTD. TSLA closed $354.72 Friday vs $449.72 at end of 2025, even with Q3 deliveries beating. Margins and free cash flow are what the market is pricing, not demand.
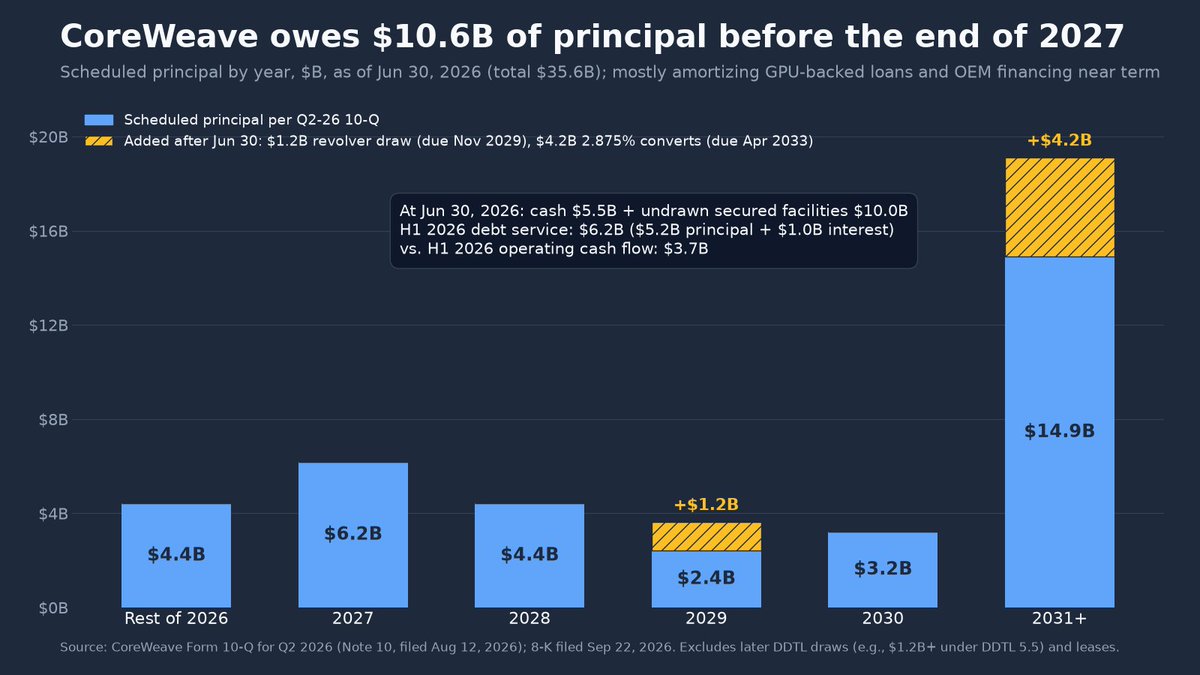
$CRWV owes ~$35.6B (Jun 30 10-Q) and ~$10.6B is scheduled to come due by end of 2027.
H1 2026: $6.2B of debt payments vs $3.7B operating cash flow. Unsecured bonds yield ~15-16%.
Backlog: $104B. Q3 report is the next test.
Not financial advice.
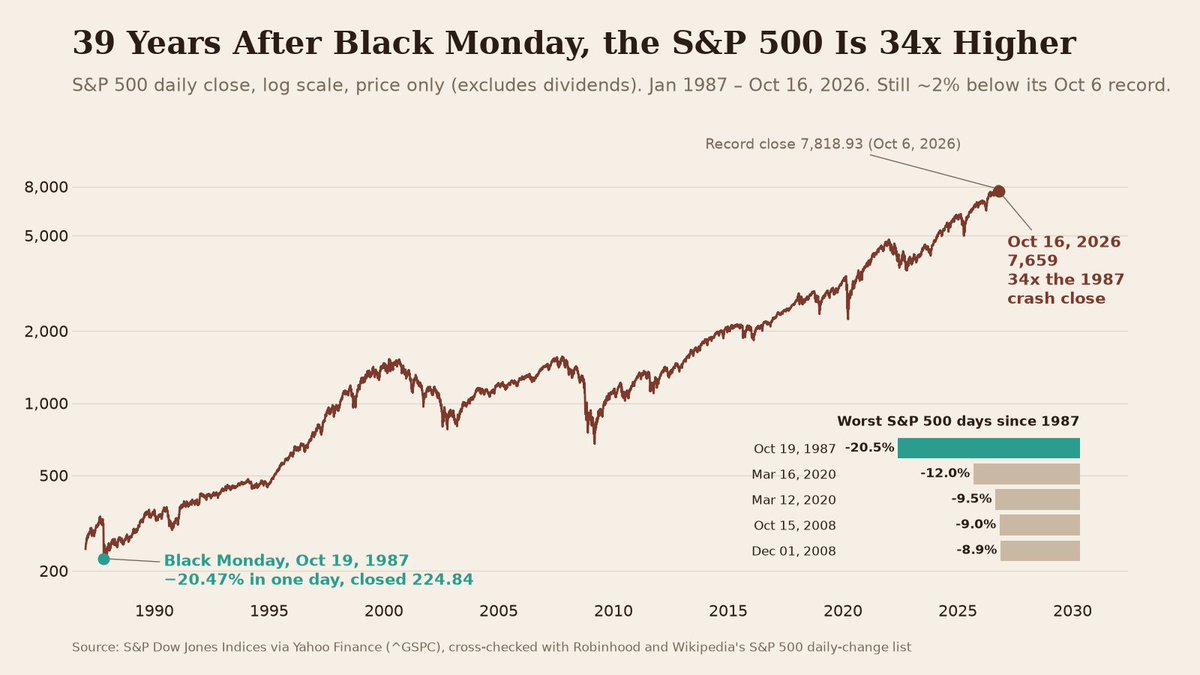
39 years ago tomorrow, on Black Monday, the S&P 500 fell 20.47% in a single day to 224.84.
Friday's close: 7,659, about 34 times that level (price only).
Even buying the Friday before the crash, at 282.70, is still up 27x.
$SPX $SPY
Fair point. The 2008 line is only about how long the streak is, not that it's another 2008. The KBW Bank Index has fallen 6 weeks in a row for the first time since July 2008, but it's only 12.8% below its August record. Big bank Q3 results didn't show a credit blowup, so for now I'd read this mostly as a rates and margin worry. The thing to watch is charge-offs and reserve builds in the next quarters.
Bank stocks just logged 6 straight weekly losses, the longest losing streak since 2008.
The KBW Bank Index closed Friday at 169.0, down 12.8% from its Aug 14 record.
The last streak this long ended in July 2008.
Big bank earnings didn't stop the bleeding.
Bitcoin is down ~24% in a year and ~35% from its Oct 2025 record.
Stablecoin supply? Still ~$305B, flat YoY and within 3.5% of May's peak.
The money didn't leave crypto. It's parked in dollars, waiting.
That's dry powder. $BTC