Bottom line: ~$1.4B EV for a CMI with maybe the best gradient/EF profile in class, funded through 2 Ph3s.
Bull: best-in-class oHCM + nHCM + HFpEF option.
Bear: China data doesn't translate, or "good enough" incumbents keep it.
No position. Not investment advice. DYOR.
$BRVE Braveheart Bio: the 3rd cardiac myosin inhibitor. Late to the party, licensed from China... and maybe best in class?
~$1.9B mkt cap, ~$0.5B cash, Phase 3 underway.
An HF cardiologist's read 🧵
Catalysts:
• Nov 6: AHA late-breaker, 52-wk oHCM extension data
• 1H27: Hengrui China Ph3 oHCM topline (N≈216, placebo), first big de-risk
• 1H27: NOBLEHEART nHCM Ph3 start
• 2H27: LIONHEART interim, possible early filing
• 2H27: HFpEF Ph2
Cash into 2029.
So: bankruptcy or blockbuster?
The science says maybe blockbuster. The balance sheet says maybe bankruptcy. A ~€22M valuation prices almost only the second.
The deal decides which story wins.
Disclosure: small long position. Not investment advice. DYOR.
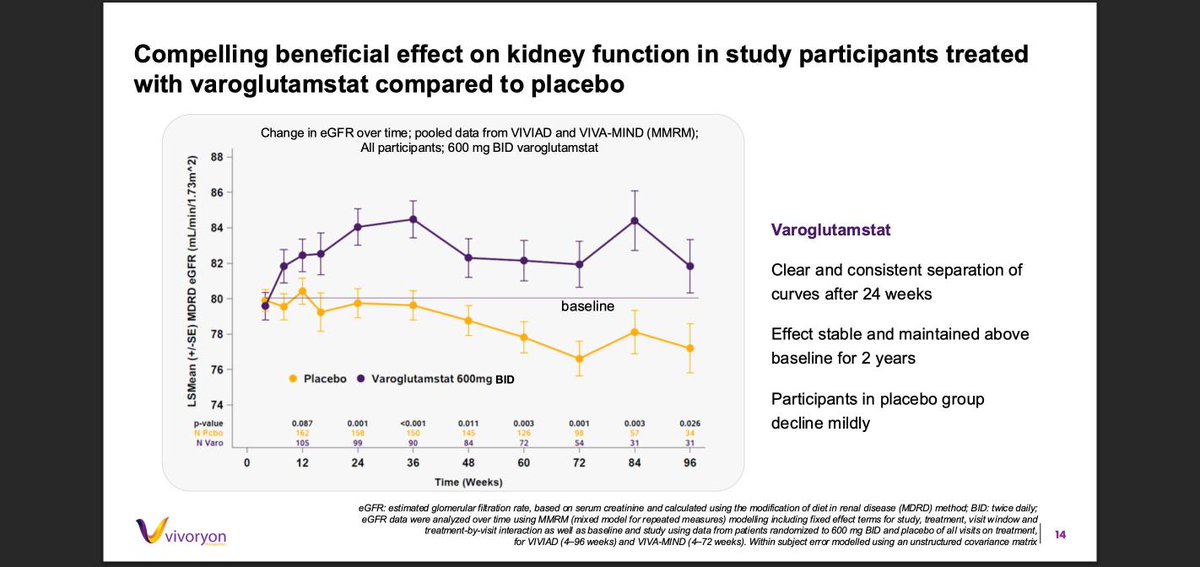
$VVY Vivoryon: set to bankruptcy. But is this a blockbuster?
~€22M mkt cap, runway "into Q4 2026", auditor going-concern flag.
Yet its oral drug did what no DKD drug does: it RAISED eGFR vs placebo, in 2 independent trials.
A physician's read 🧵
Catalysts:
• Q3 results early Nov, with updated runway
• Partnering: "advanced negotiations with different parties" (Oct 26) + a kidney investor doing diligence
• If funded: Ph2b in stage 3b/4 DKD, N=120, on SoC. Interim ~15 mo, primary ~24 mo. Needs ~€15M to interim, €30M total