We published this article a while back predicting hyperliquid:native price at $105 based on buybacks and burns.
The reason its easier to sell hyperliquid:native to wall street is because of its structured buybacks and burns, you can build models such as these to value the token.
The point is not that our model is accurate, the bigger point is you can build models like these to price the token. Do give it a read if you have time.
https://t.co/VVu9x0o6TT
Built a Claude-Native terminal as a fun side project. It's called Yardmaster.
We have been running three, four, five Claude Code sessions at once — but our terminals had no idea. To iTerm, a Claude that's been grinding for 20 minutes, a Claude waiting for permission to run migrations, and a dead pane all look identical: a rectangle of text. Moving between these tabs is another problem and lot of times you would even wonder which project is this instance of claude handling.
And yet nobody wants to leave the terminal. Devs live here. The terminal doesn't need replacing — it needs to learn what an agent is.
So Yardmaster is a real macOS terminal where Claude sessions are first-class:
→ Every session named, grouped by project, with live status — working, waiting on you, idle — straight from Claude Code's hook protocol. No output scraping, no guessing.
→ One-keystroke git worktrees: run several Claudes on the same repo without collisions, then diff, merge, or open a PR from the app.
→ An inbox of every session that's blocked on you, with the exact question it's asking.
→ Token spend per session, live on every row.
→ And when you just need a terminal? It's still just a fast, multi-tab terminal.
Now the part that actually keeps me up at night: this took two days to build. Two days, working alongside Claude, to solve our own workflow problem — a real app, with git integration, native notifications, and a packaged installer.
That's the bigger story. Software has always been take-it-or-leave-it: you use the interface the company shipped. But when an app costs two days instead of two quarters, that flips. Maybe the future isn't downloading tools and adapting to them — it's describing the tool you actually need and having AI build it around your workflow. Yardmaster is just what that future looked like for ours.
Built with Claude, for people who build with Claude. Open source, free:
https://t.co/ppWWgsH4On
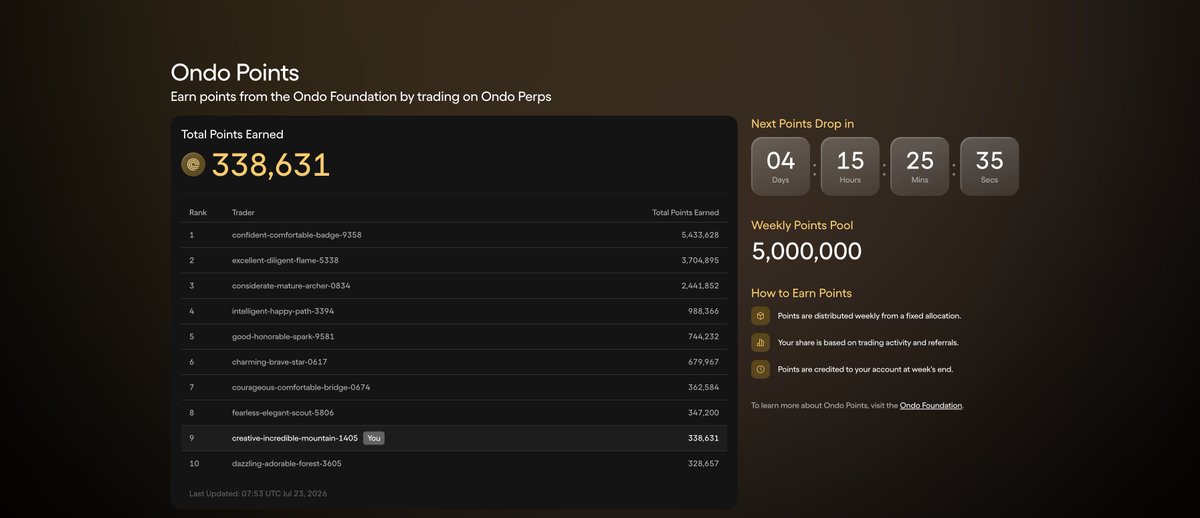
@OndoPerps is doing a great job bringing stock perps with stock collateral to market. Hope to see other protocols implement this soon.
If you don't have access you can use my referral link to start trading and earning points plus other rewards
https://t.co/K7BGKOqcBO
Apparently, it takes @Porsche nearly two months to fix a broken door arrester. The resolution for which turned out to be replacement of the door.
The process:
1. You take the car to the showroom.
2. They inspect the issue and raise a ticket with HQ for “approval” — which can take up to a week. Why is HQ approval even required to diagnose a broken door arrester?
3. They ask you to bring the car back again, take another week to analyze it, and then return the car to you without fixing it.
4. They send their findings back to HQ and wait for another approval to actually carry out the repair.
5. Once approved, if a part needs to be ordered, that is apparently another month-long process.
6. The part finally arrives, and they need another week to “prepare” it for the car.
7. You bring the car in yet again, and the actual repair takes another week.
So a relatively straightforward mechanical issue turns into a two-month saga because of approvals, repeated visits, internal bureaucracy, parts logistics, and absurd turnaround times.
At some point, you have to ask: why is the customer paying the price for @Porsche’s internal inefficiencies?
Premium pricing. Completely non-premium ownership experience.
Never ever again!
@APompliano Become $HYPE treasury, that’s the only kind of DAT which makes sense. It has native yield and many other revenue generating opportunities. Can’t say that about any other crypto right now.
@claudeai can be a great teacher.
Used it to teach myself some fundamentals about studying AI stack for investing. Hope it can help you as well.
https://t.co/1ikIlM1PFq
I have been thinking about why companies like @SpaceX and @Tesla get such high valuation multiples.
The common explanation is that @elonmusk is good at storytelling. That is true, but incomplete.
The deeper reason is that he does not build companies around normal business problems. He builds them around problems that initially sound almost impossible.
Electrify every car in the world.
Make humanity multiplanetary.
Build reusable rockets.
Solve autonomous driving.
Build humanoid robots.
These are not merely hard problems. At the beginning, they look close to impossible. And that matters.
Think about it, do you know the big problems Google, Microsoft, Facebook, Amazon are solving! You most likely don't. Most successful startups solve a big problem, raise capital, build the right team, execute well, and eventually become mature companies. Once the original problem is mostly solved, improvements become incremental. The company shifts from imagination to optimization. Margins, efficiency, distribution, market share, quarterly numbers.
At that point, the market can put the company in a box.
Auto company.
SaaS company.
Consumer hardware company.
Aerospace company.
And once the market can put you in a box, it knows how to value you. Multiples compress.
What Musk does differently is that he keeps his companies out of the box.
He starts with a mission so large that the market cannot value it through current cash flows alone. Then he breaks the impossible problem into visible milestones. Each milestone makes the original mission look slightly less impossible.
Tesla made EVs desirable.
SpaceX made reusable rockets real.
Starlink turned launch capability into global internet infrastructure.
Each step reduces the “impossible” discount.
And as the problem starts looking less impossible, more people align with the vision. Capital comes in. Talent comes in. Governments pay attention. Suppliers take the company seriously. Customers become believers. Investors start underwriting not just the current business, but the next layer of optionality.
This is the key point: capital is not just a result of the vision. Capital becomes part of the execution engine.
A high valuation allows the company to raise more money, hire better people, absorb more failures, build more infrastructure, and move faster than competitors. The valuation itself becomes reflexive.
Vision creates capital.
Capital creates progress.
Progress validates the vision.
Validated vision attracts more capital.
That loop is extremely powerful when the company keeps executing.
This is also why the companies can remain in a perpetual startup phase. Not because they are immature, but because the mission keeps expanding before the market can value them as mature businesses.
When Tesla started getting close to proving EV scale, the story moved to autonomy, robotaxis, energy, AI, and Optimus.
When SpaceX proved launch dominance, the story expanded to Starlink, defense, space logistics, Starship, Mars, and eventually an entirely new space economy.
The bar keeps moving.
But it does not move randomly. It moves into adjacent impossible problems where the company’s existing capabilities give it some unfair advantage.
This is why the multiples stay high.
The market is not only valuing what Tesla or SpaceX are today. It is valuing a portfolio of future call options attached to a founder and organization that have already made impossible things less impossible before.
Of course, this can go wrong.
If the narrative runs too far ahead of execution, the same reflexive loop can reverse. High valuation can become high expectations. High expectations can become disappointment. And when the market finally decides a company belongs in a normal box, the multiple can collapse very quickly.
So the real question is not whether these companies deserve high multiples because the vision is big.
The real question is whether they can keep converting impossible claims into partially de-risked realities.
That is the actual Elon premium.
Not storytelling alone.
Storytelling plus execution.
Vision plus capital formation.
Impossible problems broken into visible milestones.
And a company that keeps expanding the frontier before the market can call it mature.
I think it’s time to revisit the accredited investor laws in the US.
Companies are staying private longer, where only accredited investors (aka rich people!) can invest. Retail investors can only come in after IPO, when much of the upside has already been captured.
These rules were created with the best of intentions, to protect regular people from scams - a noble idea. Unfortunately, in practice they've often made it illegal to get richer, unless you're already rich. A regressive tax!
We have to judge policies based on their outcomes, not on their intentions.
These are two possible routes I see:
1) Replace the rule with something merit-based, like a financial literacy test. Pass it and you're accredited. Having a qualification based on competency rather than your bank balance or income seems far more fair.
2) Remove the rule entirely. Let consenting adults assess their own risk. Disclosure requirements stay and fraud enforcement stays to punish bad actors.
There are some massive funding rate opportunities between Hyperliquid and Ondo Equity Perps even on large names like Google. Easy 25-50% APR and because its google, its unlikely you will get liquidated on your shorts.
In case you can't access Ondo, you can use this link https://t.co/5zWtmNZyOd
We all know what happens to low MC, High FDV tokens. Thats what SpaceX is right now. The investor unlocks start next month. If you are buying I don't think you will make money for a long time on the stock. There is a very high probability that SpaceX will become much more valuable over long run but there will most likely be a much better opportunity to enter into SpaceX at a much better price.
For now it makes sense to short SpaceX. Its not really a bet against the company, its a bet against market perception of the valuation of the company. Not a financial advice, do your own research.
Former BlackRock fund manager Ed Dowd on the SpaceX IPO:
"people gotta understand... [SpaceX] raised $75 billion... [and only] floated 5% of the stock... it's a very small float"
"[But its valuation], that's a different story"
"$1.7 trillion did not go to SpaceX. [It is] $75 billion. So people need to understand that"
"then when Anthropic and OpenAI, if they ever make it to IPO, they're going to raise about $100 billion each. So the total raised actual real money is about $300 billion between these three IPOs"
"Their valuations, that's a different story. And those probably won't hold and they'll probably, you know, go down 80%. So anybody buying these stocks at these prices is probably going to lose a lot of money if they hold on to them"
@ShannonJoyRadio@DowdEdward
Our Vault has an expected drawdown of 25% based on our backtests. i.e. You should be willing to risk that much of the capital while investing. Invest only if you can tolerate this kind of risk.
Thanks @TokensWolf for pointing out that we do not include this in our vault updates. Going forward every update will have this risk disclaimer.