Bond & FX Minds is an independent, non-profit digital platform dedicated to rigorous, unbiased analysis of India’s financial markets. Views are personal.
@riteshmjn Issue is not cost...cost may be even cheaper in india...its ecosystem it lacks...once a businessman invest capital their will be politician/activist/burocrates will start their hafta.. that cost is way higher then just buying from China and selling.. no risk on large capex..
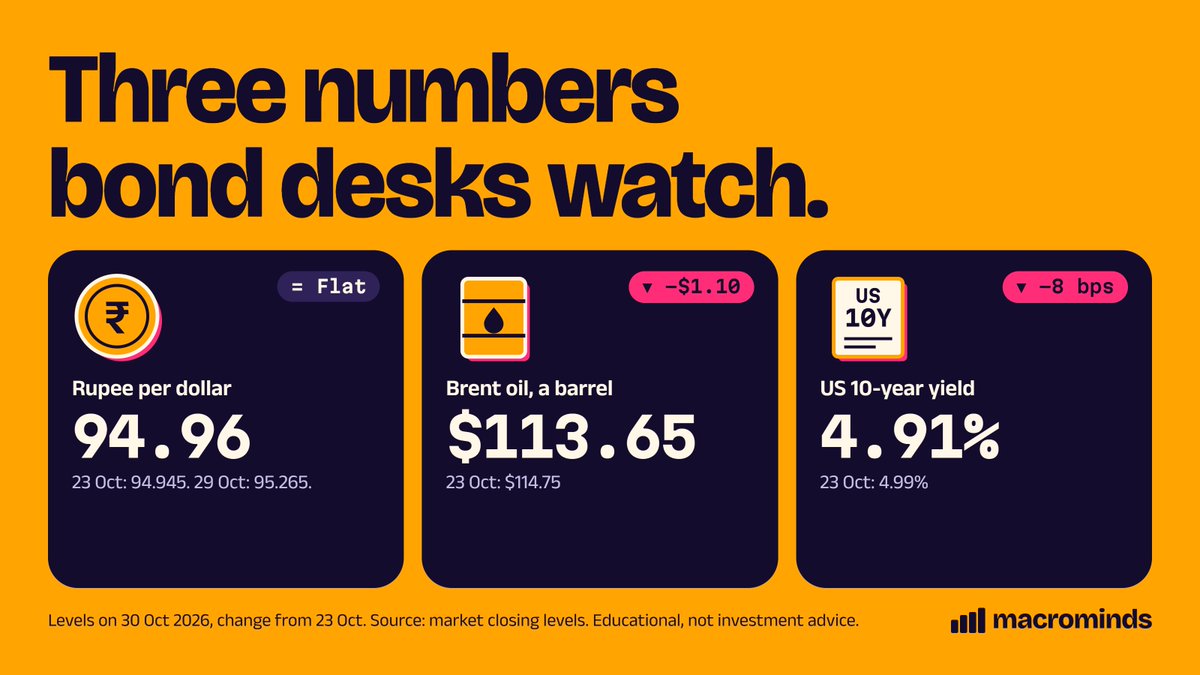
Three numbers on every Indian bond desk's screen, 30 Oct:
Rupee: 94.96 a dollar
Brent: $113.65 a barrel, down $1.10 on the week
US 10-year: 4.91%, down 8 bps on the week
Foreign funds (FPIs) cut their Indian FAR bond holdings by ₹1,676 cr this week. The real story is a swap.
6.36% 2031: −₹1,719 cr
6.53% 2031: +₹1,770 cr, as its size jumped to ₹40,000 cr
It looks like a roll into the newer bond.
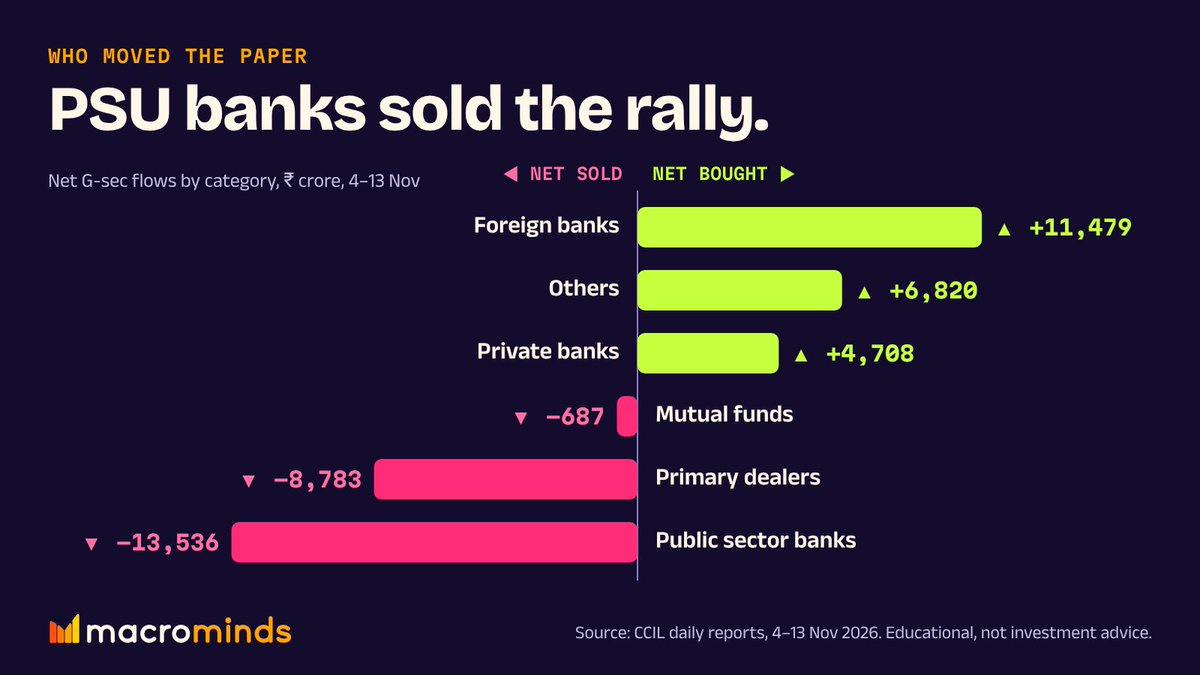
Who moved India's govt bonds this week? Net, 26 to 30 Oct:
Mutual funds: +₹4,342 cr
State-run banks: +₹4,138 cr
Foreign banks: −₹3,582 cr
Primary dealers: −₹4,068 cr
Foreign banks sold all five days. They aren't the same as FPIs.
The rupee ended the week flat. We think hedging it got dearer.
MIFOR, a rupee swap rate that builds in dollar funding costs, 23 to 30 Oct:
2-year: +17 bps
3-year: +19 bps
5-year: +8 bps
The Oct forward rose from 415.5 to 431 points on Friday alone.
Short rates rose this week while India's 10-year yield fell.
182-day T-bill: +21 bps
1-year OIS: +14 bps
5-year OIS: +4 bps
10-year G-sec: −6 bps
OIS is the market's bet on overnight rates. 1 bp = 0.01%. 23 to 30 Oct.