🚨BREAKING: $IREN just got the green light for the Buyback Bomb.
The shareholders have overwhelmingly approved the authorization to repurchase shares (Proposal 7 & 8).
Translation: Management says the stock is dirt cheap AND they have a new tool to crush the float. Don't ignore the SEC filings.
The buyback battle is coming.
Why is there such an appetite to short the semiconductor space?
Just because something has run up hard, does it mean it has to pull back?
We’ve previously shared how to use IV/HV patterns to identify tops in parabolic moves—a strategy that successfully called the crashes in gold and silver.
However, we aren't seeing that same divergence between IV and HV this time around.
As a result, I don't currently have a model with high conviction that supports an immediate pullback for chip stocks.
Being "up a lot" is never a valid reason for me to short.
Valuation might be, but there are plenty of "vaporware" stocks in this market that are much better short candidates. Shorting semis carries massive risk—simply put, this is a generational trend.
$OKLO $SMR $CCJ $UUUU $LEU | The Holtec Palisades nuclear plant is set for a historic restart, backed by $1.52 billion in federal loan support.
As the first-ever nuclear facility in U.S. history to be brought back online, this 777MW plant is slated to provide carbon-free baseload power to over 800,000 homes starting in 2026.
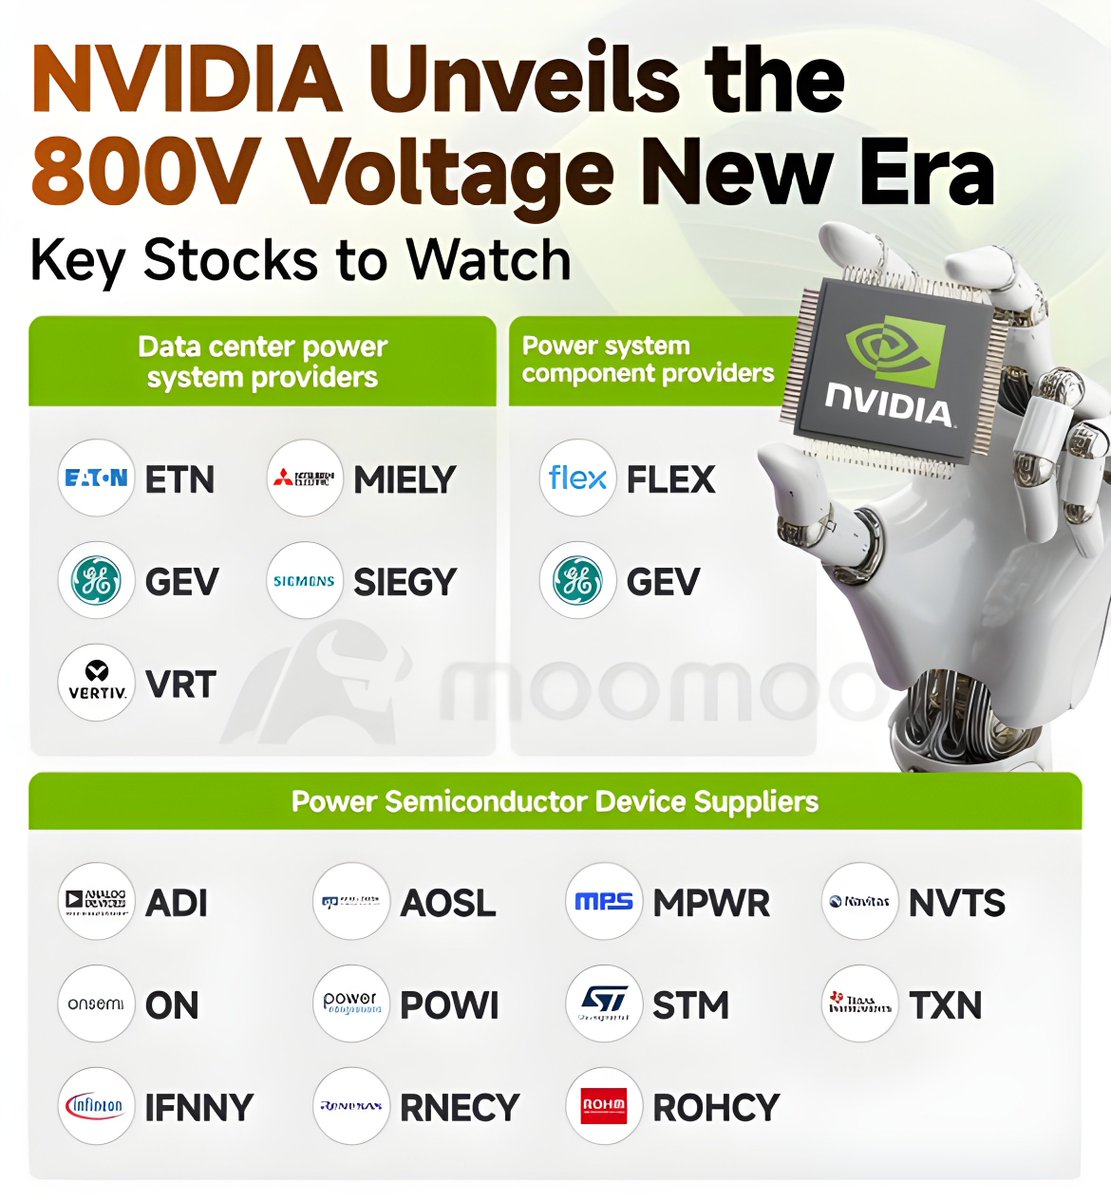
NVIDIA has ushered in a new era of 800V power architecture.
Data center power system providers:
$ETN $MIELY $GEV $SIEGY $VRT
Power system component providers:
$FLEX $GEV
Power semiconductor device suppliers:
$ADI $AOSL $MPWR $NVTS $ON $POWI $STM $TXN $IFNNY $RNECY $ROHCY
$IREN finally broke out again.
The new wave of mid-term swing trades is rolling out.
The entire data center cohort , $WULF, $IREN, $CIFR, $NBIS, $CRWV, $APLD — have held up well lately.
$WDC and $STX are also looking strong recently. $BE keeps trending higher.
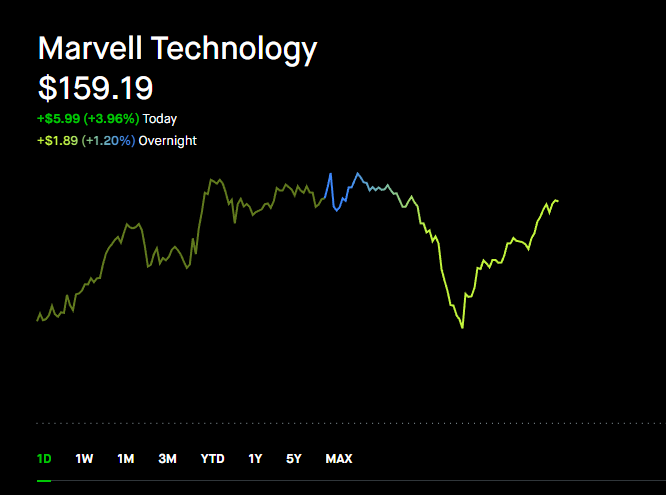
$MRVL is acquiring Swiss optical company Polariton, positioning itself early for next-gen 3.2T optical modules.
$MRVL has true empire-builder potential , a possible 20x story.
It’s already the #2 ASIC chip design player, right behind Broadcom.
Both of its core tracks — custom ASICs and optical interconnect — are trillion-dollar TAM arenas.
At this valuation, it still looks seriously undervalued.
$TSLA Releases Q1 2026 Earnings Report
On April 22, 2026, Tesla, the largest electric vehicle and solar energy company in the United States, released its earnings report for the first quarter.
Key Financial Highlights:
Total Revenue: $24.9 billion, an increase of 16% year-over-year (YoY).
Automotive Sales: Revenue increased by 16% YoY, while vehicle production grew by 13%.
Net Income: $480 million, up 17% YoY. The net profit margin was 2.1%.
Trailing 12-Month Profit: Over the past year, the company generated $4.2 billion in net profit (approximately 28.7 billion RMB).
Company Overview & Performance:
Workforce: Tesla employs approximately 130,000 people globally. On average, each employee generates $32,000 in net profit annually.
Market Position: Founded in 2003, Tesla currently boasts a market capitalization of approximately $1.45 trillion, ranking it 8th among U.S. companies.
Stock Performance: The company has achieved an average annualized return of 37% over the past 10 years. Since its IPO in 2010, the stock has delivered an average annualized return of 43.6%.
Index Inclusion: Tesla is a constituent of both the S&P 500 and the Nasdaq 100 indices.
Core Offerings:Tesla's primary business segments include electric vehicles, energy storage systems, solar products, autonomous driving software, and robotics.
$INTC is taking off again.
Intel’s primary strategy this year has been to build partnerships with major tech companies
essentially hitching their wagon to the industry giants.
With the stock nearing $70, they’ll need a major catalyst to keep this rally going.
I'm sure $TSLA will mention them in their earnings call, but the IV is just too high for tomorrow's print. It’s a tough trade.
Tesla CEO Elon Musk said Tesla plans to use Intel’s $INTC 14A process for its large-scale “Terafab,” calling it the right move as the node matures. He wants memory, logic, masks, and packaging under one roof for faster chip iteration.
TSMC said it will hold off on deploying $ASML's latest chipmaking tools until 2029, arguing the newest machines are still too expensive to justify for now. - Bloomberg
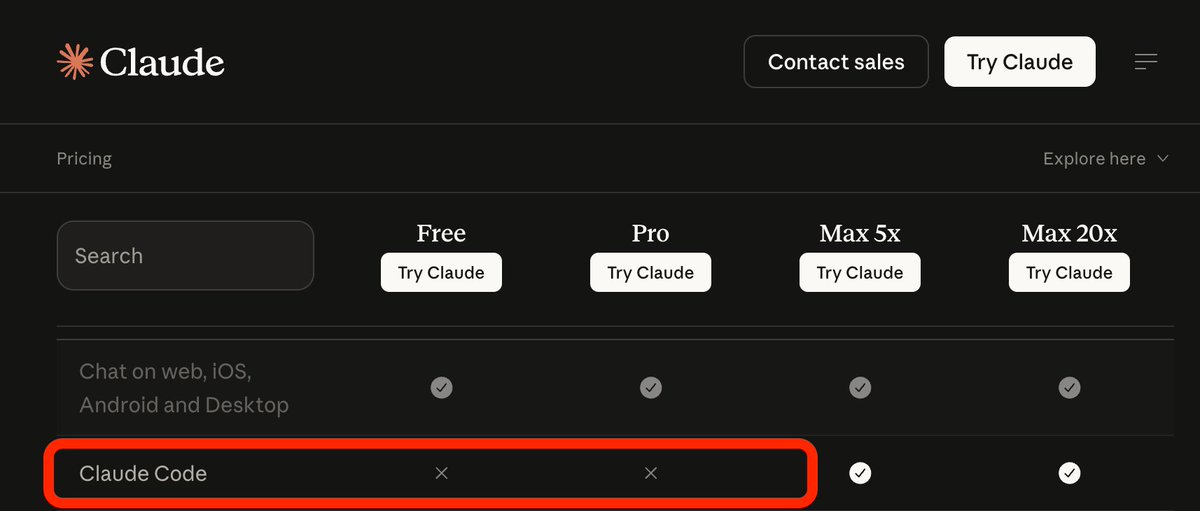
Anthropic’s pricing power is clearly getting stronger.
At the $20 tier, Claude is no longer included—basically signaling a shift away from mass subscriptions toward a token-based monetization model.
On one hand, this helps address compute constraints by increasing profit per token. On the other hand, it reflects Anthropic’s ability to keep raising prices, backed by having one of the strongest models on the market.
Anthropic just pulled Claude Code from the Pro plan.
Pro users wanting it need Max now.
$100/month minimum. 5x jump.
I'm on Max 20x so I'm fine.
Flagging for anyone on Pro who's about to find out.
No announcement. Just a pricing page edit.
A lot of people are calling $LWLG the next $LITE.
But the valuation looks stretched. It’s still a long way from true commercialization, so I wouldn’t chase it here.
This is more of a “buy on dips” name—better to trade it with the broader optical cycle than go all-in at these levels.
The smartest thing the company has done is not trying to disrupt the existing silicon photonics or InP ecosystem, but instead positioning itself to integrate into it.
In 2026, they announced partnerships with foundries, and it seems like the market has started to recognize their credibility within that ecosystem.
The 10x move over the past year kind of reflects that shift in perception.
The main issue, though, is still valuation.
There’s a lot of uncertainty, and even though the company has some revenue now, it’s not really meaningful enough to anchor the valuation yet.
$NBIS seems to be running into issues with power delivery.
The laws of the physical world are unforgiving,my sense is the next wave of market fear could hit around data center power constraints, and that might end up putting real downside pressure on today’s overheated semiconductor sector.
$RKLB CEO Peter Beck dropped some wildly direct takes at a recent in-person event:
1.“When it comes to satellites, we’re basically at the point where we can build almost anything we want.”
2.“The moment Neutron actually rolls onto the launch pad, there’s a very real chance Falcon 9 pricing starts to come down.”
3.“On the question of a SpaceX IPO and what it means for RKLB stock — at least internally, across our board and management team, the general view is:
on balance, it’s probably a net positive.”
Way more direct than his usual podcast interviews.
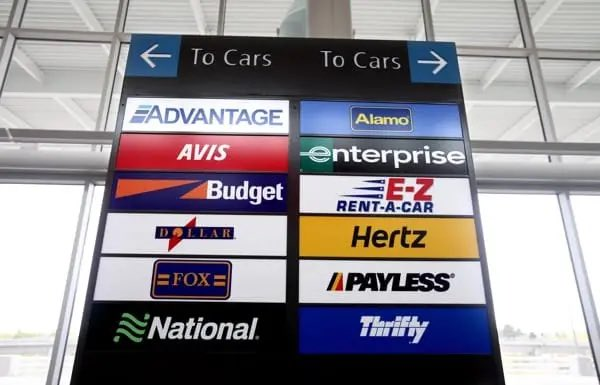
$CAR is up another 14%.
The car rental space is notorious for these monster'speculative stocks,look no further than $CVNA.
Analyzing the capital flow dynamics for these types of names is a fascinating area of research.
They are undoubtedly being targeted by institutional funds as Alpha-generating opportunities at specific points in their cycle.
$AEHR rallies 7.8% as it clears dilution overhang and lands record AI test orders.
The News:Aehr completed a $60M ATM equity offering. While offerings usually pressure the stock, the market is rallying now that the uncertainty of further dilution is gone.
The Catalyst:The company landed a $41M production order from a top-tier hyperscaler for AI ASIC testing.
The Outlook:Bookings for the second half of the year are now over $92M.
Demand for reliable, high-compute AI chips is hitting a new gear.
$AMD's Competitive Advantages:
High yields at TSMC: Consistently exceeding 70%.
Cost-efficiency: Leveraging chiplet architecture to optimize production costs.
Core counts: Leadership in high core-count performance.
$INTC Competitive Advantage:
Domestic manufacturing: A U.S.-based foundry footprint.
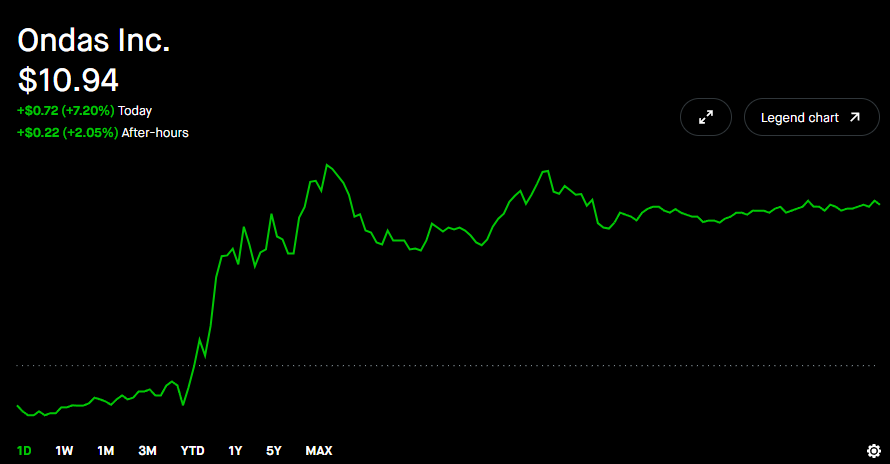
$ONDS surges 7.5% on $50M Israeli demining contract.
Ondas is a leading provider of private wireless networks and drone/robotics data solutions.
Its core business operates across two key segments:
Ondas Networks: Providing secure, private broadband wireless connectivity for rail, energy, and government sectors.
OAS (Ondas Autonomous Systems): Includes 4M Defense and Airobotics, focusing on autonomous drone platforms for AI-driven monitoring, mapping, and security.
The Catalyst:Subsidiary 4M Defense announced a $10 million initial order today, part of a broader $50 million "Eastern Border" mine clearance program in Israel.
When factoring in previous projects, the company currently has approximately $80 million in active tenders across Israel and the surrounding region.
The Thesis:The market is increasingly validating the company's AI-driven robotics technology for defense and automated demining as it reaches a commercial inflection point, fueling today’s rally.