Market thoughts, dip buys, and trend ideas.
I’m building my own process in public—sharing what I see, what I’m watching, and what I’m wrong about.
Always thinking in risk/reward, not certainty. Not financial advice.
Long term investor, AI bull, $AMD shareholder
$AMD's EPYC 'Venice' CPUs look sold out a year early. It’s been reported that 2027 volumes are fully booked, with AMD already selling 2028 allocation. Morgan Stanley projects 6.75M Venice units in 2027, which is 17% above Nvidia's Vera and 5.4x AMD's 2026 shipments — as 256-core TSMC-2nm parts ride agentic-AI demand, setting AMD up for record server-share gains.
BREAKING $META announced @Muse for small business 😃👀
@Meta announced today (September 29, 2026): Muse for Small Business. It is not a new model. It is a workplace-oriented version of Muse, the personal AI agent Meta launched for consumers on September 8
Muse is an agent, not a chatbot. You give it a goal (run the business, find customers, review the books) and it works across connected tools instead of only answering questions. The SMB version adds connectors so it can start with context about the company rather than a blank slate.
Ads still pay the bills. Muse is the attempt to become more than an ad company: take a cut of commerce, sell compute via subscriptions, and lock businesses into Meta’s agent + ad + social stack. Zuckerberg’s “future is for everyone / personal superintelligence” framing is the public narrative; the product move is “give the owner an always-on operator that already knows their Page, ads, and books.”
Consumer Muse already showed traction (App Store charts; Sensor Tower ~2.8 million downloads in the first two weeks). SMB is the logical next surface because Meta already has the identity graph and the ad account.
@farzyness@KrisPatel99 I remember you saying this a while back. You’ve been consistent with this, and I think you may be right.
Volatility in the market should be seen as a buying opportunity for long term investors, which the chance of a short term rally
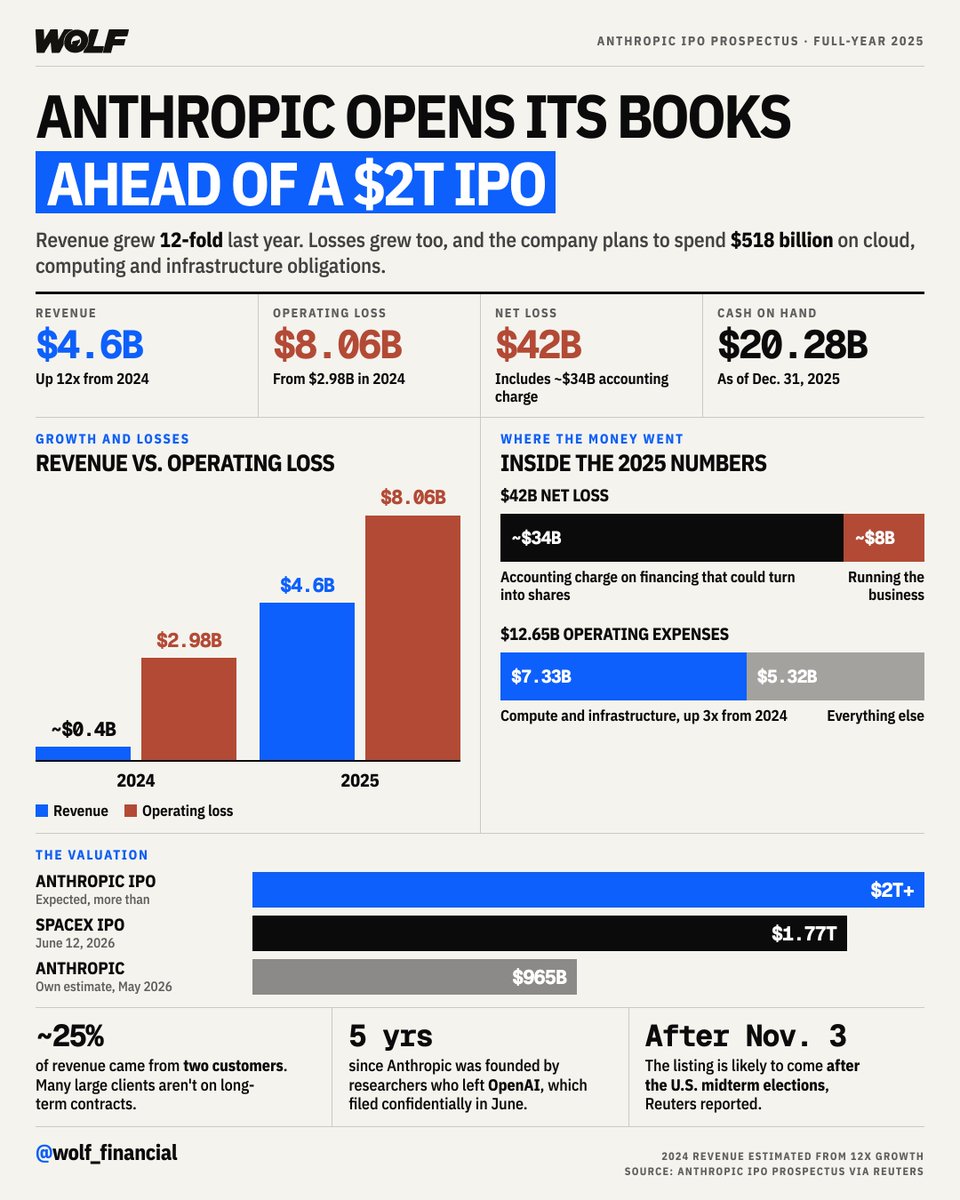
Anthropic has filed for an IPO, with its prospectus seen by Reuters, potentially targeting a valuation above $2 trillion.
The listing is reportedly likely to come after the November U.S. midterm elections.
Some numbers behind that potential $2T valuation:
• FY25 revenue: $4.59B, up 1,088% YoY
• Operating loss: $8.06B
• Compute + infrastructure spend: $7.33B, up 190%
• Cash + short-term investments: $20.28B
• Future cloud, compute + infrastructure obligations: roughly $518B
At a $2T valuation, Anthropic would be valued at more than 400x its FY25 revenue.
The filing gives one of the clearest looks yet at what public markets may be asked to pay for frontier AI growth, and just how capital-intensive that race is becoming.
Source: Reuters
@Jruss23x Yes I have both. Apple Card used to be my main, now Robinhood Gold card took that spot. The Robinhood banking app is so nice, and 3% on everything is hard to beat!
META PLATFORMS $META JUST ANNOUNCED A NEW BUSINESS UNIT
Meta Enterprise Platform
This is what CEO Mark Zuckerberg just said about the move:
"We believe superintelligence will create significant new opportunities for all people and businesses. Meta already serves billions of people at scale and helps hundreds of millions of businesses reach customers. Today we are starting the next major pillar of our business, Meta Enterprise Platform, to help businesses use AI to grow and transform in new ways as well.
Meta Enterprise Platform will use our strengths that few other companies have: advanced models, leading agents, large-scale infrastructure, and years of working closely with many businesses. Initially, we will focus on bringing our full technology stack, including the Muse agent, Meta Business Agent, Muse API, Muse Code, and more to businesses and developers to help them grow.
To lead this effort, I’m excited that Chirantan “CJ” Desai will join Meta as Chief Enterprise Platform Officer, reporting directly to me. CJ is an experienced enterprise leader with a track record of building full-stack software and delivering results in AI, infrastructure, business applications, and security. He has an extensive industry network that we look forward to partnering with. He joins us from MongoDB, where he was CEO and President. Before that he led product and engineering at Cloudflare and spent nearly eight years at ServiceNow, including as President and COO.
I’m excited about beginning this new chapter for Meta and looking forward to working closely with CJ."
@LongGameEquity Love the pick, don’t love the timing, and still have questions around the CEO track record. Diversification away from Apple has been a success, but also a headwind.
But as the saying goes… time in the market beats timing the market
@FunOfInvesting Interesting take. Does China have that much incentive for them to reach an agreement? I believe they do, and also don’t for different reasons. Would like to hear a different perspective
$META Muse AI can be connected directly to Instagram, making edits on your profile by simply asking to do so.
This is particularly useful for businesses and content creators, who can manage their Instagram as well as retrieve analytics on their page, which can help them increase engagement, market more effectively, and overall sharpen their social media strategy
$AMD at $630/share is dirt cheap on 0.1-0.6 PEG🧵
Not Financial Advice! DYOR! I do own AMD shares!
Projected FY2026 Revenue: $55-$60B ($57.5B Mid)
Net margin keeps rising with better operating leverage
PEG = (today’s price ÷ that year’s EPS) ÷ EPS CAGR from 2026.
2027 will have explosive YoY growth "well over 100%", which we can think of 120-140%. Fwd PE is in the 26-29x with 3 digits growth, that is cheap. And yes everyone is trying to project 2028-2029 growth RIGHT NOW. I'm sticking to my $800 Personal PT by end of 2026. AMD this week broke my old $620 PT.
This thread is more of average revenue growth projections for the next 3-5 years to judge its PEG Ratio. Less than 1 is mad cheap for @AMD growth and potential.
I believe 40-50% CAGR is very reasonable base case for AMD in the next 3-5 years. 60%+ is the bull case where AMD gets more TSMC allocation as #1 TSMC customer in term of WPM.
Dr. Su has been explicit that the old 1:4 / 1:8 CPU to GPU host ratio is moving toward 1–2:1, and that lots of agents could mean much more CPUs than GPUs. In recent discussion, people are talking abt 40 CPU : 1 GPU in extreme Agentic AI case. In a $META @Muse Consumer Agentic world, the most logical Ratio would be 8-12 CPU : 1 GPU IMO. Consumers are actually find AI Agents useful, and Muse is WINNING!
Projected GPUs market share FY2027 15-25%
CPUs market share will be in the 50%+ medium-long term.
Net Margin Path assumption, the advantage of Fabless:
40% case: 24% → 26% → 28% → 30% → 32% → 33%
50% case: 24% → 27% → 30% → 32% → 34% → 35%
60% case: 24% → 28% → 31% → 33% → 35% → 36%
Revenue > Net Income > EPS > PE > PEG
1. 40% revenue CAGR
2026: $57.5B, $13.8B NI, $8.31 EPS, 76x
2027: $80.5B, $20.9B NI, $12.61 EPS, 50x , PEG 0.97
2028: $113B, $31.6B NI, $19.01 EPS, 33x, PEG 0.65
2029: $158B, $47.3B NI, $28.51 EPS, 22x, PEG 0.44
2030: $221B, $70.7B NI, $42.58 EPS, 15x, PEG 0.29
2031: $309B, $102B NI, $61.48 EPS, 10x, PEG 0.21
2. 50% revenue CAGR
2026: $57.5B, $13.8B NI, $8.31 EPS, 76x
2027: $86.2B, $23.3B NI, $14.03 EPS, 45x, PEG 0.65
2028: $129B, $38.8B NI, $23.38 EPS, 27x, PEG 0.40
2029: $194B, $62.1B NI, $37.41 EPS, 17x, PEG 0.26
2030: $291B, $99.0B NI, $59.62 EPS, 11x, PEG 0.17
2031: $437B, $153B NI, $92.06 EPS, 7x, PEG 0.11
3. 60% revenue CAGR
2026: $57.5B, $13.8B NI, $8.31 EPS, 76x
2027: $92.0B, $25.8B NI, $15.52 EPS, 41x, PEG 0.47
2028: $147B, $45.6B NI, $27.49 EPS, 23x, PEG 0.28
2029: $236B, $77.7B NI, $46.82 EPS, 13x, PEG 0.17
2030: $377B, $132B NI, $79.45 EPS, 8x, PEG 0.10
2031: $603B, $217B NI, $130.76 EPS, 5x, PEG 0.07
=> 3 year PEG (2028)
40% 0.65 / 50% 0.40 / 60% 0.28
=>5 year PEG (2030)
40% 0.29 / 50% 0.17 / 60% 0.10
AMD may look like at a premium with TTM, but we are only more than a month away from Q3 Nov ER, where Q4, the first biggest J-curve quarter guidance will be issued.
Analysts, Investors and Institutions are fighting on where Q4 guidance is going to land. Otherwise if "they" just strictly judging AMD on TTM, AMD would just trade in the $300-$400 range at most.
I do not believe in outdated/old(TTM) data, market is forward looking. You may be able to buy stocks at a discount in businesses that have declining revenue/profitability or slower growth, but most will not get to buy high quality businesses when growth is ACCELERATING! Get it?
Not Financial Advice! DYOR! I do own AMD shares!
That goes back to the point of this post.
At the Goldman Sachs event earlier this month, Matt Ramsay spoke on behalf of AMD saying that they will do significantly more than $20 EPS over the strategic timeframe.
The strategic timeframe, which was set in 2025, was a 3-5 year timeframe calling for just $20 EPS at the time.
Based on what I’m seeing between the Muse app, continued forecast raises, and the fact that Lisa Su has been historically conservative with her estimates, I believe there is a strong chance that EPS is $30 before 2030.
I’m seeing lots of chatter on X regarding $AMD and whether we should be selling, trimming, or holding shares here.
What you decide to do with your portfolio is your own decision based on your own risk/reward tolerance. I’m not here to tell you what to do, but I will give you some insight into what I’m seeing so you can make educated decisions for yourself.
Recent price action for AMD has driven the stock to over $1trillion market cap, the first time ever by a Women CEO and a historical accomplishment for AMD. The recent move in price action as been accompanied by a violent swing in $META , who has broken out near ATHs on the back of their new Muse personal AI assistant, and to a lesser extent, the VR glasses that were showcased earlier this week.
This move is important in understanding the AMD story. Meta, a large customer for AMDs data center segment, has proven that they are able to develop a consumer app built around personal AI agents. Muse has scaled quicker in its launch than chatGPT. While I do think this is a skewed way of looking at the apps success, it is impressive nonetheless.
As someone who has been testing Muse since its release, I will say that it is impressive, but it needs to be better. This is where AMD comes in. What we’re seeing in front of our faces when using Muse is the agentic AI story playing out in front of us. The story, which depends on higher CPU to GPU ratio, where AMD is the most dominant player in the CPU space, has already been a story creating a tailwind behind AMD stock.
The numbers that Lisa Su has given for CPU TAM have grown throughout the year, and seeing this play out in front of me, I am confident that those numbers will continue to grow. AI assistants need to be lighting fast in the future. They’re nowhere near that yet. The demand for CPU will be so high in the near future, analysts will have to increase their projections on AMD.
Pair this with the scaling of mi400 series with 14GW already committed from hyperscalers, and you have a recipe for a company that will continue to grow faster than estimates. The only thing that can slow AMD in the near term is the time it takes to ramp production.
If you’re selling AMD today, I would ask yourself if it’s because you need to maintain a balanced portfolio for your risk tolerance or because you think there just isn’t any room to run anymore.
If it’s the latter, I would recommend that you try Muse AI, and then go back to this post and reconsider your thoughts. Then imagine this scaling across all the hyperscalers, understand that the $20 EPS target is the floor for AMD over the next 2-3 years, and that EPS will likely surpass $30/share by 2030.
On top of that, the market can front run the growth as expectations continue to get raised, which can lead to continued momentum in the stock price.
Looking forward to AMD earnings early November where Lisa Su will give us updates on the business. I am most excited for hearing about CPU TAM, but am also hopeful that we will hear new commitments on Mi400 series deployments.
$AMD