$TSLA
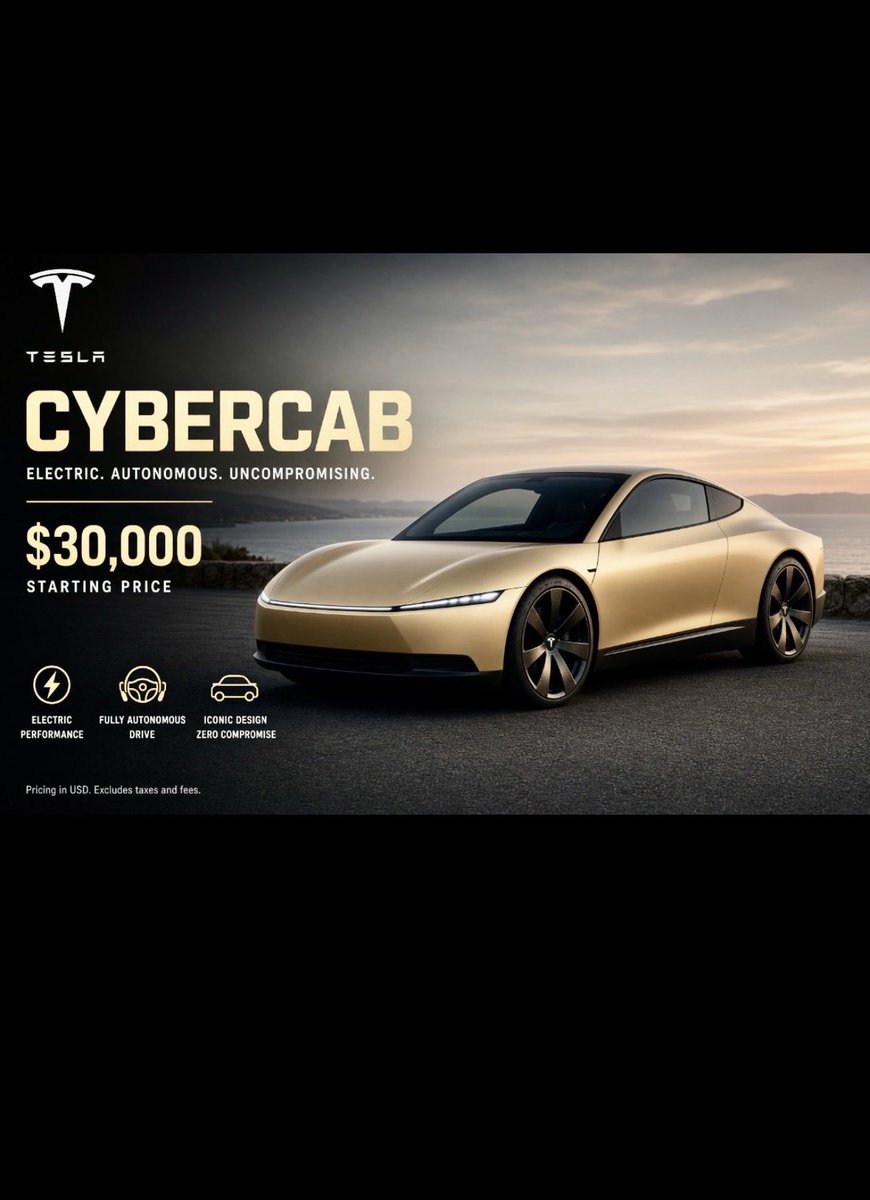
Cybercab just entered public service in Austin with ~45 registered units.
The existing Robotaxi fleet is still a few hundred vehicles, not thousands. Waymo is already at ~4,000 vehicles and ~500k paid rides/week and still isn’t a material line item for Alphabet.
Tesla has the manufacturing advantage if unsupervised FSD generalizes and regulators allow it.
Until utilization, cities, and insurance math show up in the 10-Q, Robotaxi is an option, not earnings.
On valuation:
a 2026/27 P/E in the 150–210x range against Street long-term growth in the mid-30s is extended versus the rest of Mag 7 on PEG.
That’s not childish. It’s the multiple. The bull case only works if Robotaxi + Optimus change the earnings base faster than competitors and regulators allow.
Until that shows up in units and dollars, caution on the stock is just reading the tape.
@garyblack00
Cybercab just entered public service in Austin with ~45 registered units.
The existing Robotaxi fleet is still a few hundred vehicles, not thousands.
Waymo is already at ~4,000 vehicles and ~500k paid rides/week and still isn’t a material line item for Alphabet. Tesla has the manufacturing advantage if unsupervised FSD generalizes and regulators allow it. Until utilization, cities, and insurance math show up in the 10-Q, Robotaxi is an option, not earnings.