1
Masai halkı zararlı yağlar tüketmiyordu elbette ama belki de kalp hastalıklarının asıl ve öncelikli nedeni bu değildi..?!!
Zira Masai halkı aşıları ve ilaçları da hiç tüketmiyordu..
Tıpçılar dikkatleri kendi üzerlerinden başka yerlere çekmekte ziyadesiyle ustalar..!
Kanser tedavisi için kansere neden olan ilaçları veren Modern tıbbın teşhisi de, tedavisi de hastalıklardan çok daha tehlikelidir
Olmayan C19 teşhislerinde ve tedavilerinde, sonrasında da aşılarında bunu açıkça gördük
Modern tıp en güvenilmez ve en şeytani sistemdir
$META bull thesis in a nutshell:
It’s is projected to overtake Google in ad revenue this year.
Search will be mostly AI, so advertisers will shift spending from $GOOG to $META. Thus, it’ll will also capture a higher share of incremental ad dollars.
How can you be bearish?
This looks concerning initially, but it’s actually bullish.
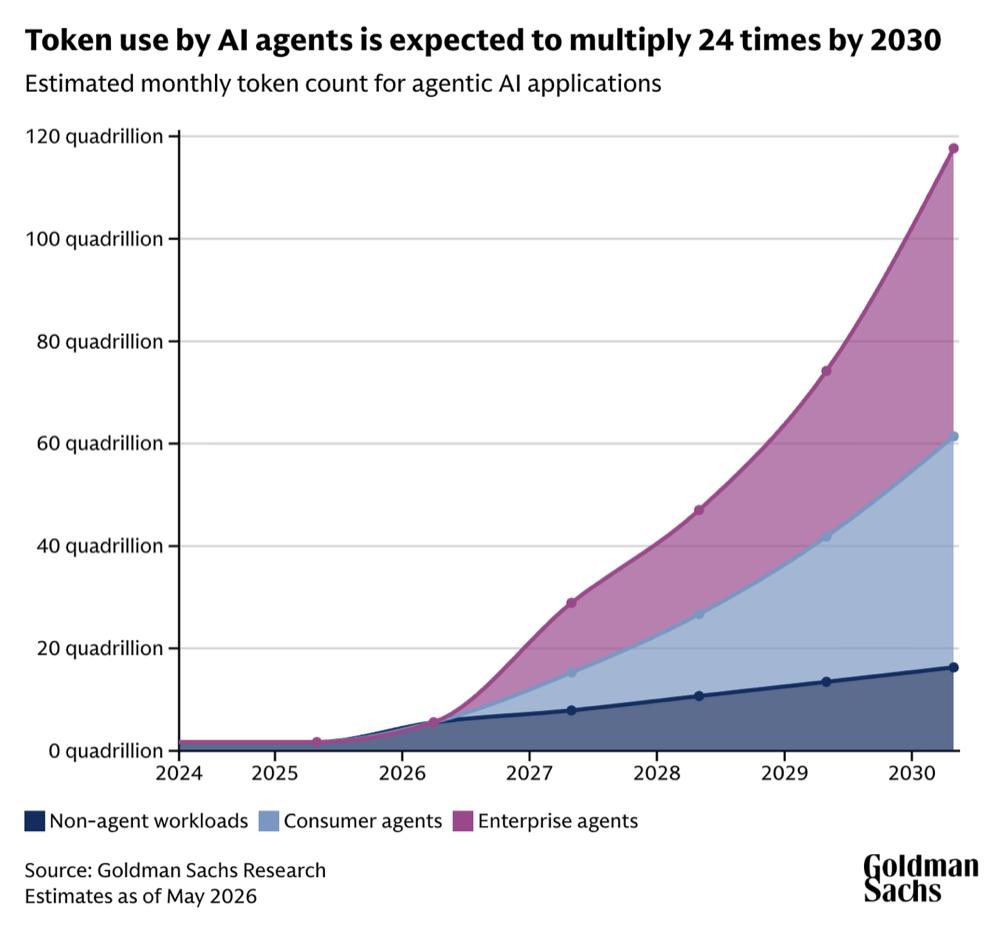
If $MSFT can generate $24.1 billion AI revenue from OpenAI, think about OpenAI’s total revenue potential.
And then think about the total potential of the AI complex as token consumption is expected to grow 24x by 2030.
I think this sell-off won’t get much deeper.
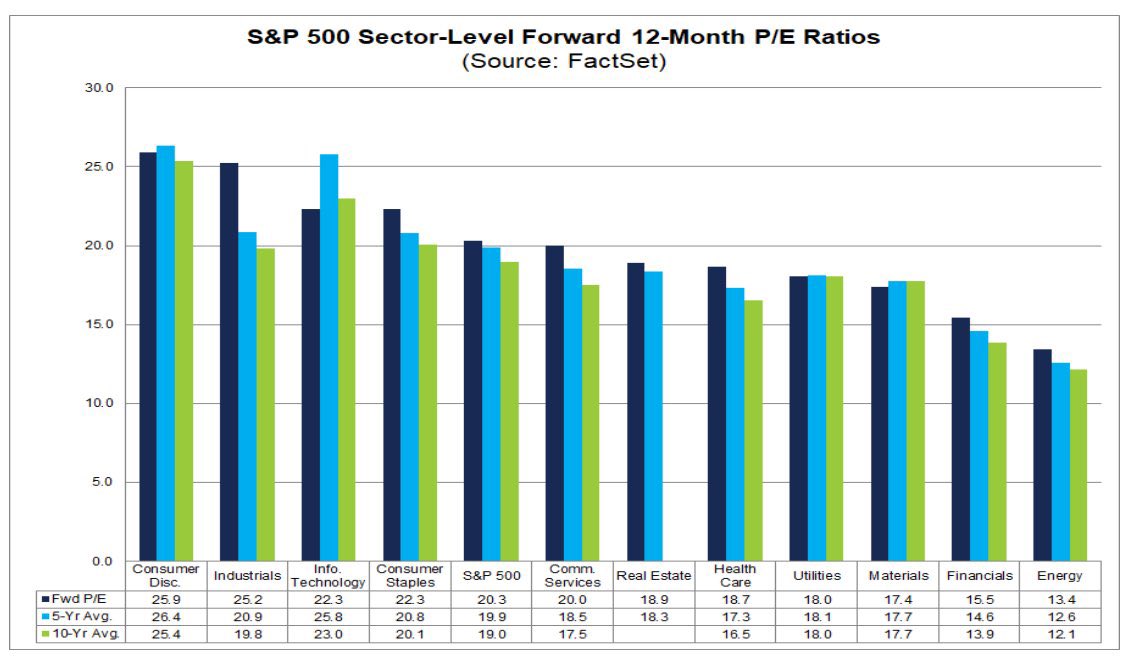
The market still looks overvalued across the board but not that much, given 5-10 year averages.
There is nothing on sight to trigger systemic outflows, so I don’t see how we can go much lower from here.
$META now is $GOOG in 2024.
$GOOG was sold down to 18x fwd earnings in 2024.
It’s doubled since then.
$META has also been sold down to 18x fwd earnings because the market doesn’t think it’ll be able to generate ROI on its AI capex.
I think it’ll play out similarly to $GOOG.
Merhaba kızlar, benim gibi olan bakımlı temiz sevişmeyi bilen eğlenmeyi bilen Cross dresser arkadaş arıyorum bakireyim lütfen uzun süreli düşünenler sevgili olmak isteyenler yazsın tecrübeli olursa benim için daha iyi olur💕😘😘😋😛 @gayroskop
4 days ago, I shared these 10 tickers with you all.
If you had allocated capital equally across all 10 names, the portfolio would be up 8.14% in just a few days.
No hype, just transparency.
Top Performers
- $DGXX +36.95%
- $SRXH +21.13%
- $MBLY +15.83%
- $SLNH +13.11%
- $EOSE +8.11%
Decliners
- $OPEN -8.38%
- $IBRX -4.41%
- $ONDS -1.43%
Follow for more high-conviction stock ideas, swing setups, and market insights.
Bank of America just raised its AI data center forecast to $1.7 Trillion by 2030.
Yet the companies actually building this infrastructure are still tiny:
• $IREN → 1.4 GW energized + >4.5 GW pipeline (~$20B market cap)
• $CIFR → ~3.4 GW pipeline (~$8.3B market cap)
• $WULF → ~2.8 GW pipeline (~$11.5B market cap)
• $SLNH → 4.3 GW+ pipeline (high risk, high reward, execution yet to be proven~$230M market cap)
At @DavidSacks $50B per GW estimate, each additional gigawatt is worth tens of billions in market cap.
This is not financial advice, but holding any of this stock for the next 3 years will make you rich.... Mark my words.
$IREN IREN
$HUT Hut 8
$DGXX Digi Power X
$WULF TeraWulf
$APLD Applied Digital
$CORZ Core Scientific
$SLNH Soluna Holdings
$GLXY Galaxy Digital
$RIOT Riot Platforms
$CIFR Cipher Mining
$MARA MARA Holdings
$CLSK CleanSpark
$BTDR Bitdeer Technologies
$HIVE Hive Digital Technologies
$NBIS Nebius Group
$CRWV CoreWeave
$WYFI WhiteFiber
$OPEN Opendoor
$ONDS ONDAS Holdings
$BB BlackBerry
Investing carry risk.... Do your own research and Invest wisely
$SMCI
THIS IS A 200$ STOCK CHILLING UNDER 35$
Don’t miss the next $DELL sitting in plain sight completely washed out.
AI infrastructure pure play.
Bottomed sentiment.
Explosive growth still intact.
-4% today.
Sitting right on a 4-year trend line.
This is the dip.
Bookmark it.
~19B market cap vs ~$152B for $DELL
$DELL remains the cleanest comparison:
• AI server infrastructure
• GPU rack deployments
• Enterprise + hyperscaler demand
• Massive NVIDIA exposure
But here’s the difference:
$DELL = diversified giant
$SMCI = high-beta AI pure play
And that’s where the upside sits.
$SMCI Q3 FY26:
• $10.24B revenue (+123% YoY)
• AI/GPU platforms = 80%+ of sales
• Gross margins recovered to ~10%
• EPS beat expectations
• FY26 guide raised again:
→ $38.9B–$40.4B revenue
That’s hypergrowth at scale.
Meanwhile:
• Blackwell systems already ramping
• Liquid cooling leadership
• Massive manufacturing expansion
• AI rack demand still accelerating
SMCI is evolving from “server assembler”
→ into full AI data center infrastructure.
New Silicon Valley mega-campus.
Malaysia expansion.
Rack-scale deployment growth.
Management targeting:
~6,000 AI racks/month capacity by FY26 end.
And this is the part people miss:
AI isn’t just chips.
The REAL bottleneck becomes:
• power
• cooling
• rack density
• deployment speed
That’s exactly where $SMCI dominates.
The risk?
• Thin margins
• Heavy debt/work-capital scaling
• NVIDIA dependency
• Extreme volatility
But the growth is undeniable.
Current setup:
• ~19B market cap
• ~$40B revenue run-rate
• One of the fastest-growing AI infra companies on earth
That disconnect won’t stay forever if execution continues.
Same category:
AI infrastructure ➝ hyperscale buildout
$DELL already scaled.
$SMCI still in the rerating phase.
If the AI infra cycle keeps running…
This could look absurdly cheap in hindsight.
You’ll see below:
$ANET $GOOGL $AMD $INTC $AMD $SNDK $MRAM $MU $ASML $AAPL $NVDA $NBIS $MSFT $META $VOO
DONT MISS THIS GENERATIONAL OPPORTUNITY.