We're proud to share that Rocket Doctor has been named a Best in Class Finalist in the Civic Health: Affordability, Access & Health Equity category at the Digital Health Hub Foundation's 8th Annual Digital Health & AI Awards!
Winners will be announced live at HLTH in Las Vegas!
Canadian heavy oil is selling at its biggest discount since 2023.
Western Canadian Select (WCS), Canada's main heavy crude, settled $26.40 a barrel below WTI, the US benchmark, on 15 Oct.
A year ago that gap was more than $15 smaller.
Why?
Because heavy oil is thick, harder to move and harder to refine. Right now more Venezuelan heavy crude is competing for the same US refineries, the Trans Mountain pipeline is essentially full and tanker costs have jumped.
So producers get hit twice: they sell each barrel at a discount, and they pay for expensive light diluent just to make it flow through a pipeline.
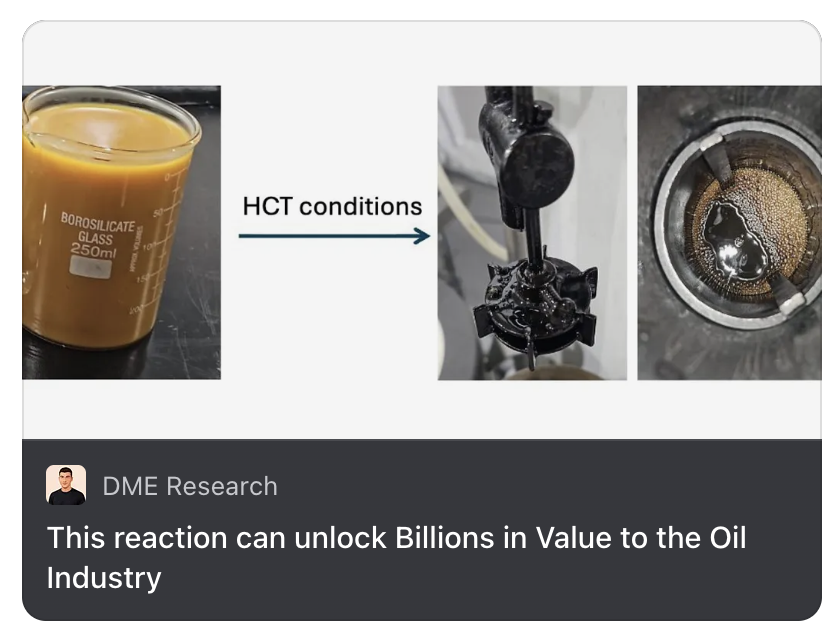
That's the problem I wrote about in my $ADUR piece: upgrading heavy oil near the field so it flows more easily and is worth more.
The opportunity is big and $ADUR is aiming directly at this problem.
First, let me count my blessings. I was invited to an investor presentation with fund managers and investors to meet with $ADUR management this week in Europe. This was Aduro's first time presenting to what I consider front-of-the-line Money Managers in Europe, and after both presentations, I came out with the highest level of conviction I have had in a while. You see, when you are sitting on large paper gains, the temptation to cash out is always there, so I have to say, outside of trading around my core position. I came out more interested in expanding my core position.
Now back to the presentation and my key observations for now, which I may add to once I get to Dubai:
1. Everything shared there is publicly available, but when you sit through an hour-and-a-half session and hear the founder and CEO speak, plus the questions that get asked, you realize how rare @AduroCleanTech is. Aduro also made it clear that they are not here to raise capital; they have what they need till closer to the end of the FOAK (my assessment: closer to Q3/4-27)
2. Two fund managers, after realizing how huge the opportunity is, asked management bluntly, " Why are you public. This company should have been a VC-backed company that would go public later in 2028/2029, post the FOAK, and I quote, "5 to 10bn Euros". The answer was equally impressive; Ofer said that when he and Marcus decided to finally go public (after they were poached for a buyout in 2020), it was to preserve their independence and allow Aduro to sprout its multi-vertical platform without being under the gun by a VC or a strategic investor that might have wanted shortcuts or shift the company's focus towards fast-tracking the process. To him, the key learnings from failed multi-billion-dollar pyrolysis companies were the same: he didn't want to skip steps, and he wanted the IP protected, and he wanted to commercialize the technology right.
3. Regarding strategic money and investments, Ofer made it clear that there were attempts by industry players to invest earlier; however, the main pushback was that Aduro did not want to give exclusivity, "being hugged by one company" too early. He believes they are closer than ever to commercial scale in two verticals, each of which could easily be worth multi-billion dollars, so giving exclusivity early could jeopardize the opportunity in the same way outlined in point 2.
3. Ofre's vision is for Aduro to be a worldwide Energy and Sustainability household, and he views that whilst the plastic and paraffinic oil verticals will be the first to go to market, the company is and continues to be focused on expanding its IP to new verticals.
4. The company's HCT platform is now being followed by all the major players in the Energy sector. Ofer made it clear that they don't see any other chemical recycling technologies as competitors, and he said Aduro is in a league of its own.
5. Their IP is iron-clad, with 7 patents issued and 4 pending, and many more in the works, and Mena made it clear that, based on what they know today, their IP is worth way more than the current market cap.
6. Ofer does not believe in shortcuts; the company, relative to the Energy space, is going at rocket speed, but they will not, for the sake of short-term gratification, rush the process. The first recycling commercial unit is set for 2028. However, the paraffinic oil vertical felt like it could be the first to go to market, at least to me.
7. They set up their commercial plan with regard to the plastic vertical that would benefit significantly from the European regulations, which want to protect their chemical industry. Europe is pushing back against imports of cheap products from the Far East, and to protect the industry, it has new mandates that disallow the use of such feedstock without applying a penalty for non-recycled material (a penalty of 160+ Euros per ton). These regulations will tighten by 2030, with demands for recycled materials to reach 30%+ of plastics. Europe produces over 11M tons of waste plastic a year, and that keeps growing.
8. The Parrafinic Oil sets Aduro miles away from anyone else. This vertical can add $ 11 to $25 in value to each barrel produced at the Unita Basin, when energy players are scrambling for cents/barrel. The vision is to get to a place where just the Utah Basin could go from 185k barrels a day to over 1M (clearly will take years to get there), but I suggest you pause here and get your calculator out as I did, and you will realize what Aduro is sitting on with just this vertical alone
9. The world is moving towards energy independence, meaning this is not a Utah matter. Aduro views the same opportunity in Alberta's heavy oil, Venezuela, etc and these are massive opportunities in front of the company, again, in my view, each of which can be a company maker on its own.
10. I spoke with a few of the money managers post both meetings and was positively surprised by how many are keen for follow-ups and for potentially putting the name in front of their investor base. They realize that once this company is known and the FOAK, or the first Parrafinic, moves closer to commercial scale, the window of getting a meaningful alpha may lapse by then
My personal view is that if I take a step back and look at $ADUR today as an investment, it is a very compelling/rare one if I am sitting my watch for the next 24-36 months instead of looking in the rearview mirror at when I got lucky in 2021 to find this company.
As always, these are my personal views; do your own diligence. This is not financial advice
$ADUR Aduro shareholder Vicus transfers one million shares
Aduro Clean Technologies Inc (2) (C:ACT) Shares Issued 35,733,749 Last Close 9/25/2026 $17.83 Friday September 25 2026 - News Release
Mr. Avshalom Vicus reports
AVSHALOM OFER VICUS FILES EARLY WARNING REPORT FOLLOWING ESTATE PLANNING TRANSFER
Avshalom Ofer Vicus (the reporting person) has provided an update on his securityholdings with respect to Aduro Clean Technologies Inc. The reporting person transferred one million common shares of the company to a family-owned-and-controlled company pursuant to tax-driven estate freeze transaction. While the reporting person no longer exercises any voting control or dispositive authority over the transferred shares, he and members of his family retain an indirect economic interest in the shares as a result of the reporting person's long-term estate and succession planning. There is no intention for the transferred shares to be sold into the market.
The reporting person owns 24.9 per cent of the shares, calculated based on 35,871,442 shares, which consists of 35,733,749 shares outstanding as of Sept. 25, 2026, and 137,693 shares that may be acquired on exercise of stock options.
Prior to the transaction, the reporting person directly and indirectly owned and controlled an aggregate of: (i) 9,794,875 shares; and (ii) 137,693 shares that may be issued on exercise of options, of which 47,693 are exercisable at a price of $6.50 per share and 90,000 are exercisable at a price of $13.50 per share, which represent 27.69 per cent of the shares, calculated based on 35,871,442 shares, which consists of 35,733,749 shares outstanding as of Sept. 25, 2026, and 137,693 shares that may be acquired on exercise of options.
After the transaction, the reporting person directly and indirectly owns and controls an aggregate of: (i) 8,794,875 shares; and (ii) 137,693 shares that may be issued on exercise of options, of which 47,693 are exercisable at a price of $6.50 per share and 90,000 are exercisable at a price of $13.50 per share, which represent 24.9 per cent of the shares, calculated based on 35,871,442 shares, which consists of 35,733,749 shares outstanding as of Sept. 25, 2026, and 137,693 shares that may be acquired on exercise of options.
The shares were transferred for estate planning purposes. The transaction was not effected through the facilities of any stock exchange and was undertaken solely in connection with the reporting person's estate planning arrangements. The transaction does not reflect a reduction in the reporting person's support for or commitment to the company.
The reporting person has filed an early warning report pursuant to National Instrument 62-103F1, The Early Warning System and Related Take-Over Bid and Insider Reporting Issues, describing the above securityholdings with the applicable securities regulatory authorities. A copy of the early warning report is available on SEDAR+ under the profile of the company.
$ADUR talking with and posting a picture of them together with PepsiCo's Senior Manager of Circular Economy Packaging & Recycling for Latin America.
It's probably nothing, just keep ignoring this and move along.
We presented today at the PepsiCo Sustainability Innovation Hub in Mexico City—one of 10 companies invited to the event's second edition.
Representing Aduro on-site: Chief Revenue Officer Eric Appelman, Head of Corporate Development and Investor Relations Abe Dyck, and Country Manager Mexico Humberto Parra. Eric presented Hydrochemolytic™ Technology as a chemical recycling solution for polyolefin-rich waste plastics, with a focus on flexible films and multilayer packaging—formats that today have limited compatibility with established recycling pathways. Joined by Carolina Vega, Senior Manager, Circular Economy Packaging & Recycling LATAM at PepsiCo.
#CleanTech #EcoInnovation #ChemicalRecycling #PlasticRecycling #PepsiCo #SustainabilityInnovationHub