@ElMonoGran42994 He works in the industry, but I guess that might give him too heavy bias. If he personally wouldn't prescribe envu, doesn't mean the market doesn't exist for it.
𝐀𝐒𝐂𝐎 𝟐𝟎𝟐𝟔: Fresh off an IPO, @EikonTX's Chairman & CEO Roger Perlmutter describes the scientific idea behind the company, and walks us through the leading programs. $EIKN #ASCO26
Full video: https://t.co/5ygqk6OQyo
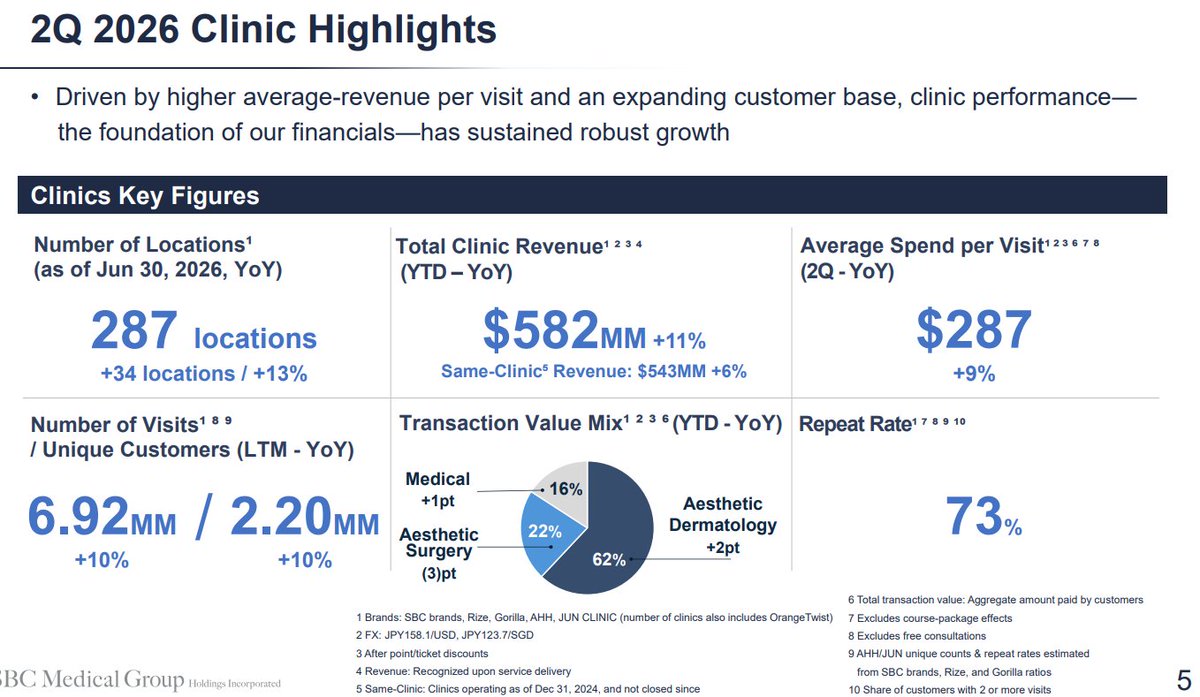
$SBC looks compelling here. SBC is a leading aesthetics and medical services franchisor/MSO in Japan, trading at roughly a 20% forward FCF yield on enterprise value and ~3x forward EV/EBITDA on my estimates.
The stock has struggled over the last two years due to its de-SPAC history, low liquidity, franchise fee restructuring, and a more competitive operating environment. Those headwinds now appear to be easing. Revenue grew sequentially in both Q1 and Q2, and Q2 revenue increased 13% Y/Y while adjusted EBITDA increased 32% Y/Y. Management has also indicated that the competitive environment has improved.
While the stock has started to react to these developments, I still believe the valuation remains very depressed relative to the underlying earnings and cash flow profile.
A large portion of SBC’s revenue is recurring, contractual, or tied to ongoing clinic activity. Gross margins are high, operating expenses have been relatively stable excluding acquired businesses and one-time items, and capex is low due to the asset-light model. Q2 gross margin was ~73%, consistent with FY2025, and the company ended Q2 with approximately $136M of net cash.
The company’s recent service fee increases should also benefit margins, as management has indicated that the associated incremental costs are limited.
Clinic operating metrics are also improving. As of 2Q26, locations were up 13% Y/Y, same-clinic revenue was up 6%, average spend per visit was up 9%, visits were up 10%, and the customer repeat rate reached 73%.
If the current operating momentum persists, the combination of earnings growth and even modest multiple normalization could create meaningful upside
The key debate from here is whether the earnings reacceleration is sustainable and whether management can allocate its growing cash generation prudently.
This is not investment advice. Please do your own due diligence.
i deleted instagram about 5 years ago, so i had almost forgotten what it feels like to have it in your life
watching people around me use it now feels strange
you end up checking the daily lives of people you haven’t seen in ten years, people you probably wouldn’t even stop to talk to if you crossed them on the street.
random people from your past become permanent background characters in your mind.
then add the fact that a huge part of instagram is effectively a dating product
if you’re already in a long-term relationship, keeping that constant stream of attention, comparison and other people’s lives in your head has destroyed countless couples
after being off it for years, the whole thing looks much more extreme from the outside.
🚨WOW! It seems that after winning the arbitration process regarding $BEAM claims to exclusivity in using Prime Editing for AATD 🧵👇 - $PRME is moving ahead with its AATD program PM647 and fast! In yet another excellent interview by @BiotechTV’s Brad Loncar - Prime Medicine’s CEO Allan Reine has confirmed that Prime intends to initiate “a regulatory filing to start a trial - a CTA or IND filing during the third quarter, which we’re in the third quarter right now”. I guess it’s just a matter of time before an official announcement is released. $XBI