Good question. The recent pipeline growth came entirely from Pre-Design-In. I read that as many new fish entering an expanding net — that´s still undisclosed so very hard to name drop — rather than proof that existing programs have already matured for next phase. The next real signal is movement through the funnel: alpha evaluation → design-in → design win → production order. The only specified timeline PO we have yet is for Jabil, Aeva, Nokia, AllSpace and Tachyon. For still undisclosed partner check my "universe"-post, there should be som of those fishes swimming around :-)
The two riddles from $SIVE’s Q2 call:
-Six unnamed pluggable engagements — three evaluating alpha samples and three in technical/supply-chain assessment.
-One new unnamed foundry partner.
On the latter, one speculative candidate worth putting on the watchlist could be Global Communication Semiconductors, GCS.
To be clear: there is no disclosed Sivers–GCS relationship. This is a hypothesis, not a claim.
Still, several pieces fit unusually well.
GCS is a California-based pure-play III–V foundry with roots in RF, wireless and millimetre-wave semiconductors — an interesting overlap with Sivers’ heritage. It also has a long InP/optoelectronics track record and offers foundry services for lasers, SOAs and other photonic devices.
GCS has described both 4-inch and 6-inch InP capability, plus volume production, second sourcing and customer-proprietary process manufacturing. That matters because Sivers may need a partner capable of transferring and qualifying its InP100 process, not merely offering a standard PDK.
CEO Vickram Vathulya said Sivers had been engaged with the new partner “for a while”, that it was “extremely motivated”, and had “tremendous capacity allocation for Sivers” available now.
The geographic angle is also worth considering. VV spoke of long-term supply resilience, while Sivers’ manufacturing slide explicitly adds “multiple production routes” and “geopolitical flexibility”.
Sivers is expanding its own Glasgow line, expected to add capacity from Q4 2027. WIN Semiconductor provides the main external route from Taiwan. A California source could create a strategically attractive triangle: internal process control in the UK, Asian scale through WIN, and North American capacity closer to major US AI and defence customers — while reducing exposure to any single site, supplier or potential Taiwan Strait disruption.
That does not prove GCS. The same slide describes external foundry and chip-on-carrier relationships as “Asia+”, so the new partner’s location remains ambiguous.
I haven't found any clear Sivers–GCS link yet, and compatibility with the exact InP100 epitaxy, gratings, facets, coatings and array process remains unverified. So no smoking gun…. But GCS appears to be technically, geographically and strategically the best match I can come up with. At least until we get more clues in this case.
Next riddle: The six unnamed pluggable engagements.
The two riddles from $SIVE’s Q2 call:
-Six unnamed pluggable engagements — three evaluating alpha samples and three in technical/supply-chain assessment.
-One new unnamed foundry partner.
On the latter, one speculative candidate worth putting on the watchlist could be Global Communication Semiconductors, GCS.
To be clear: there is no disclosed Sivers–GCS relationship. This is a hypothesis, not a claim.
Still, several pieces fit unusually well.
GCS is a California-based pure-play III–V foundry with roots in RF, wireless and millimetre-wave semiconductors — an interesting overlap with Sivers’ heritage. It also has a long InP/optoelectronics track record and offers foundry services for lasers, SOAs and other photonic devices.
GCS has described both 4-inch and 6-inch InP capability, plus volume production, second sourcing and customer-proprietary process manufacturing. That matters because Sivers may need a partner capable of transferring and qualifying its InP100 process, not merely offering a standard PDK.
CEO Vickram Vathulya said Sivers had been engaged with the new partner “for a while”, that it was “extremely motivated”, and had “tremendous capacity allocation for Sivers” available now.
The geographic angle is also worth considering. VV spoke of long-term supply resilience, while Sivers’ manufacturing slide explicitly adds “multiple production routes” and “geopolitical flexibility”.
Sivers is expanding its own Glasgow line, expected to add capacity from Q4 2027. WIN Semiconductor provides the main external route from Taiwan. A California source could create a strategically attractive triangle: internal process control in the UK, Asian scale through WIN, and North American capacity closer to major US AI and defence customers — while reducing exposure to any single site, supplier or potential Taiwan Strait disruption.
That does not prove GCS. The same slide describes external foundry and chip-on-carrier relationships as “Asia+”, so the new partner’s location remains ambiguous.
I haven't found any clear Sivers–GCS link yet, and compatibility with the exact InP100 epitaxy, gratings, facets, coatings and array process remains unverified. So no smoking gun…. But GCS appears to be technically, geographically and strategically the best match I can come up with. At least until we get more clues in this case.
Next riddle: The six unnamed pluggable engagements.
While waiting for Sivers Semiconductors' next partnership announcement, I mapped out the full prospect universe around their Photonics division.
Six partnerships are already confirmed:
• GlobalFoundries $GFS — CPO/NPO laser partner
• Jabil $JBL — 1.6T LRO transceiver
• Ayar Labs — ELSFP laser arrays
• POET Technologies $POET — Optical Interposer + DFB
• Aeva $AEVA — LiDAR laser supplier
• O-Net — Laser array partner (Asia)
Beyond these, I count 23 companies with a logical connection to Sivers' InP CW-DFB laser arrays. The framework is straightforward: technical fit, existing relationship, confirmed test orders, featured in investor presentations, mutual research projects etc.
All together I tried to match and rank all these prospects in a straight up supply chain logic with estimated mature market revenue.
Some prospects in closer orbit:
Aeva — Already confirmed for LiDAR. Now expanding into AI datacenter optics with SOA-based architecture.
Nokia — Mutual board member (Karin Raj). Just acquired an InP fab for AI datacenter capacity.
Nubis/Ciena CIEN — Sold their own InP fab in 2016. Must source lasers externally.
Lightmatter — Indicated as test customer. Builds on the same GF SiPho platform.
See full map attached. Interested to hear which connection you guys find most compelling.
$SIVE
@PepInvestStocks @AyarLabs Great overview Pep — the confirmed partnership map keeps expanding, so which is NEXT?
I mapped out 23 companies with a logical connection to Sivers' laser arrays. Same supply chain logic, ranked by proximity. I hope you like it. Full prospect cosmos attached.
While waiting for Sivers Semiconductors' next partnership announcement, I mapped out the full prospect universe around their Photonics division.
Six partnerships are already confirmed:
• GlobalFoundries $GFS — CPO/NPO laser partner
• Jabil $JBL — 1.6T LRO transceiver
• Ayar Labs — ELSFP laser arrays
• POET Technologies $POET — Optical Interposer + DFB
• Aeva $AEVA — LiDAR laser supplier
• O-Net — Laser array partner (Asia)
Beyond these, I count 23 companies with a logical connection to Sivers' InP CW-DFB laser arrays. The framework is straightforward: technical fit, existing relationship, confirmed test orders, featured in investor presentations, mutual research projects etc.
All together I tried to match and rank all these prospects in a straight up supply chain logic with estimated mature market revenue.
Some prospects in closer orbit:
Aeva — Already confirmed for LiDAR. Now expanding into AI datacenter optics with SOA-based architecture.
Nokia — Mutual board member (Karin Raj). Just acquired an InP fab for AI datacenter capacity.
Nubis/Ciena CIEN — Sold their own InP fab in 2016. Must source lasers externally.
Lightmatter — Indicated as test customer. Builds on the same GF SiPho platform.
See full map attached. Interested to hear which connection you guys find most compelling.
$SIVE
@RealJGBanks $COHR and $LITE for revenue dominance, 💯 👍
But for stock appreciation? $SIVE no doubt. Independent InP laser supplier to GF SCALE, six partnerships, MC$1.3 about to dual list for WallStreet. The photonics player yet to be known.
While waiting for Sivers Semiconductors' next partnership announcement, I mapped out the full prospect universe around their Photonics division.
Six partnerships are already confirmed:
• GlobalFoundries $GFS — CPO/NPO laser partner
• Jabil $JBL — 1.6T LRO transceiver
• Ayar Labs — ELSFP laser arrays
• POET Technologies $POET — Optical Interposer + DFB
• Aeva $AEVA — LiDAR laser supplier
• O-Net — Laser array partner (Asia)
Beyond these, I count 23 companies with a logical connection to Sivers' InP CW-DFB laser arrays. The framework is straightforward: technical fit, existing relationship, confirmed test orders, featured in investor presentations, mutual research projects etc.
All together I tried to match and rank all these prospects in a straight up supply chain logic with estimated mature market revenue.
Some prospects in closer orbit:
Aeva — Already confirmed for LiDAR. Now expanding into AI datacenter optics with SOA-based architecture.
Nokia — Mutual board member (Karin Raj). Just acquired an InP fab for AI datacenter capacity.
Nubis/Ciena CIEN — Sold their own InP fab in 2016. Must source lasers externally.
Lightmatter — Indicated as test customer. Builds on the same GF SiPho platform.
See full map attached. Interested to hear which connection you guys find most compelling.
$SIVE
Thanks Mikael — means a lot coming from a top contributor like yourself🙏🏻
Yes it's been a long road since I started following the comapny around 2012. Plenty of ups and downs along the way. But the core technical excellence inside this company has always been there — a quiet beacon pointing toward something inevitable. It was always a matter of market timing, and it finally feels like the world is catching up to what the technology promised all along.
Ha — fair point on POET management. But here's the thing: even if you don't love the Composer, the DFB laser inside it is the part that's actually hard to replace. You can swap packaging approaches, but the InP laser source is the bottleneck everyone's fighting over right now. That's where Sivers sits pretty good… upstream of the drama.
Thanks! Your supply chain analysis earlier this week was excellent — really helped me think through the second-order effects. Would love to see a similar prospect map from your perspective covering the Asian optical ecosystem. I'm sure there are leads I'm missing due to language barriers and limited visibility into Korean/Japanese/Taiwanese players.
Fair question. The financial difficulties were pre-revenue phase and it’s not until Q3 we will see some bigger numbers from photonics biz as Sivers laser are next gen.
— they were building the tech and qualifying with partners. That's now done. GF SCALE, Jabil, Ayar Labs all signed. The revenue inflection hasn't happened yet, but the design-ins are locked. You don't get designed out of a platform after tape-out.
Seems like a lot of people get it wrong about
Sivers + Global Foundries SCALE = AMD.
It's not correct... It's much bigger than that ++++++
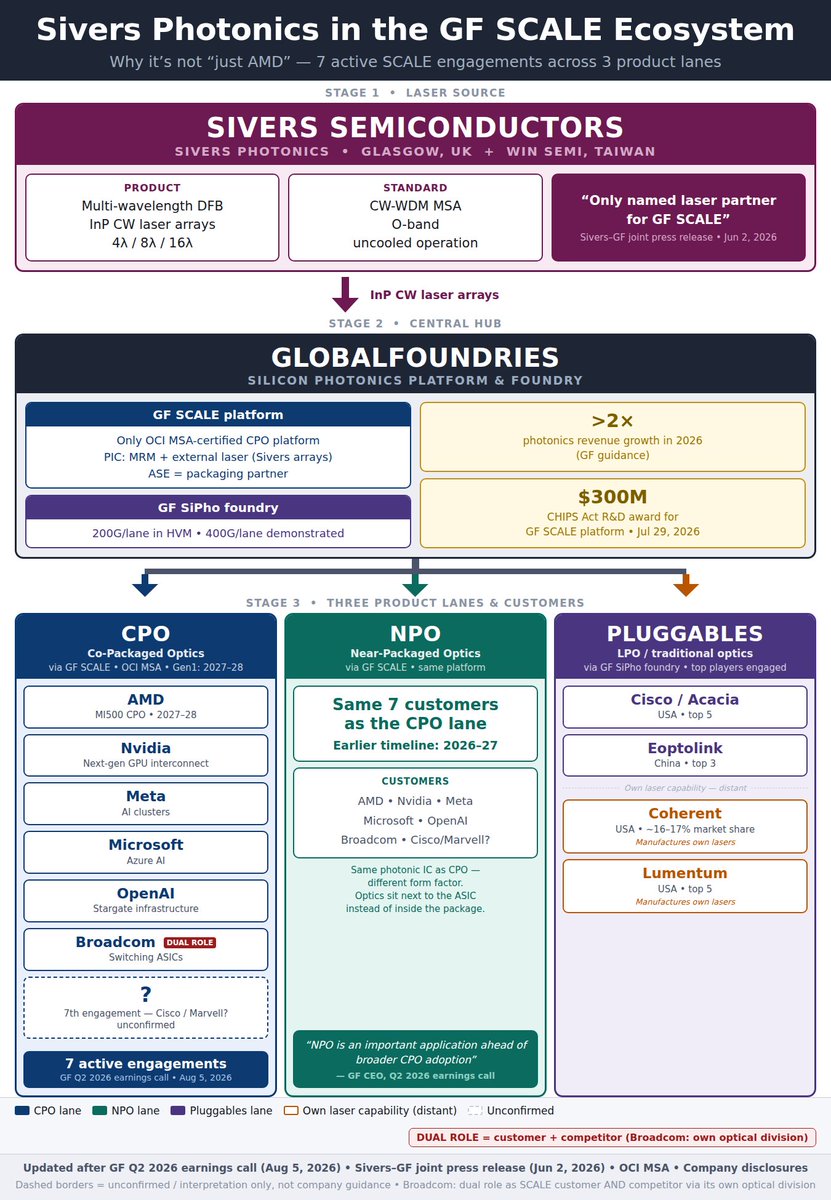
I mapped out the full GF SCALE ecosystem after today's GF Q2 earnings call.
Here's what most investors are missing:
GlobalFoundries is the ONLY OCI MSA-certified CPO platform. Every design on the platform requires external CW lasers. Sivers is the only named laser partner for GF SCALE.
Three product lanes — not just CPO:
CPO: AMD, Nvidia, Meta, Microsoft, OpenAI, Broadcom + an unconfirmed 7th(speculation in the map)
All active SCALE engagements confirmed today.
NPO: Same 7 customers above, same photonic IC, but earlier timeline (2026-27). GF´s CEO called it "an important application ahead of broader CPO adoption."
Pluggables: GF engaged with 4 of the top 5 transceiver players. Their roadmap to 1.6T and beyond is where Sivers' multi-wavelength arrays become critical.
...and more design wins taped out in Q2, another expected Q3 .
This isn't a one-customer story. It's a full platform play with 7+ engagements across three form factors — and Sivers sits at the top of the supply chain as the prime laser source.
Please check out the map and tell me if I got something backwards or needs to be clarified.
$SIVE $GFS $AMD
100% agree. Funny thing speaking of the GF SCALE collaboration… $SIVE not only get connected to Innolight… but in 2 years time… in days of future scarcity of lasers, Lumentum might not even have their own lasers in stock for their SCALE pluggable commitment as they have promised their own main customers everything they have on the shelf. Time is on Sivers side.
https://t.co/6YblrPg6v3
Seems like a lot of people get it wrong about
Sivers + Global Foundries SCALE = AMD.
It's not correct... It's much bigger than that ++++++
I mapped out the full GF SCALE ecosystem after today's GF Q2 earnings call.
Here's what most investors are missing:
GlobalFoundries is the ONLY OCI MSA-certified CPO platform. Every design on the platform requires external CW lasers. Sivers is the only named laser partner for GF SCALE.
Three product lanes — not just CPO:
CPO: AMD, Nvidia, Meta, Microsoft, OpenAI, Broadcom + an unconfirmed 7th(speculation in the map)
All active SCALE engagements confirmed today.
NPO: Same 7 customers above, same photonic IC, but earlier timeline (2026-27). GF´s CEO called it "an important application ahead of broader CPO adoption."
Pluggables: GF engaged with 4 of the top 5 transceiver players. Their roadmap to 1.6T and beyond is where Sivers' multi-wavelength arrays become critical.
...and more design wins taped out in Q2, another expected Q3 .
This isn't a one-customer story. It's a full platform play with 7+ engagements across three form factors — and Sivers sits at the top of the supply chain as the prime laser source.
Please check out the map and tell me if I got something backwards or needs to be clarified.
$SIVE $GFS $AMD
@cherryPayment Hey Mark, great post.. as always. Tell me what you think about my updated ecosystem map on Sivers/GF/SCALE since todays Q2 report🤙
https://t.co/R8v8PwqmnG
Seems like a lot of people get it wrong about
Sivers + Global Foundries SCALE = AMD.
It's not correct... It's much bigger than that ++++++
I mapped out the full GF SCALE ecosystem after today's GF Q2 earnings call.
Here's what most investors are missing:
GlobalFoundries is the ONLY OCI MSA-certified CPO platform. Every design on the platform requires external CW lasers. Sivers is the only named laser partner for GF SCALE.
Three product lanes — not just CPO:
CPO: AMD, Nvidia, Meta, Microsoft, OpenAI, Broadcom + an unconfirmed 7th(speculation in the map)
All active SCALE engagements confirmed today.
NPO: Same 7 customers above, same photonic IC, but earlier timeline (2026-27). GF´s CEO called it "an important application ahead of broader CPO adoption."
Pluggables: GF engaged with 4 of the top 5 transceiver players. Their roadmap to 1.6T and beyond is where Sivers' multi-wavelength arrays become critical.
...and more design wins taped out in Q2, another expected Q3 .
This isn't a one-customer story. It's a full platform play with 7+ engagements across three form factors — and Sivers sits at the top of the supply chain as the prime laser source.
Please check out the map and tell me if I got something backwards or needs to be clarified.
$SIVE $GFS $AMD
@pgodwinaa Spot on! …and I don't think we should underestimate the OCI MSA framework — when those big players align on a shared standard, it creates massive pull-through for whoever sits in the reference design. Platform effects compound I guess.
Seems like a lot of people get it wrong about
Sivers + Global Foundries SCALE = AMD.
It's not correct... It's much bigger than that ++++++
I mapped out the full GF SCALE ecosystem after today's GF Q2 earnings call.
Here's what most investors are missing:
GlobalFoundries is the ONLY OCI MSA-certified CPO platform. Every design on the platform requires external CW lasers. Sivers is the only named laser partner for GF SCALE.
Three product lanes — not just CPO:
CPO: AMD, Nvidia, Meta, Microsoft, OpenAI, Broadcom + an unconfirmed 7th(speculation in the map)
All active SCALE engagements confirmed today.
NPO: Same 7 customers above, same photonic IC, but earlier timeline (2026-27). GF´s CEO called it "an important application ahead of broader CPO adoption."
Pluggables: GF engaged with 4 of the top 5 transceiver players. Their roadmap to 1.6T and beyond is where Sivers' multi-wavelength arrays become critical.
...and more design wins taped out in Q2, another expected Q3 .
This isn't a one-customer story. It's a full platform play with 7+ engagements across three form factors — and Sivers sits at the top of the supply chain as the prime laser source.
Please check out the map and tell me if I got something backwards or needs to be clarified.
$SIVE $GFS $AMD
@LeifInvests Nice list! Mybe check $SIVE (Sivers Semiconductors) that topped the sector today at +20% on this news. InP laser arrays for CPO/1.6T and supplies GlobalFoundries & Jabil. Only ~$1.3B market cap, Stockholm-listed but dual-listing to US planned. Tiny pure-play worth watching 👀