ARK’s Brett Winton on the podcast
1. Over the weekend, SpaceX executives followed Tesla’s X account. That looks like a sign that something is happening internally.
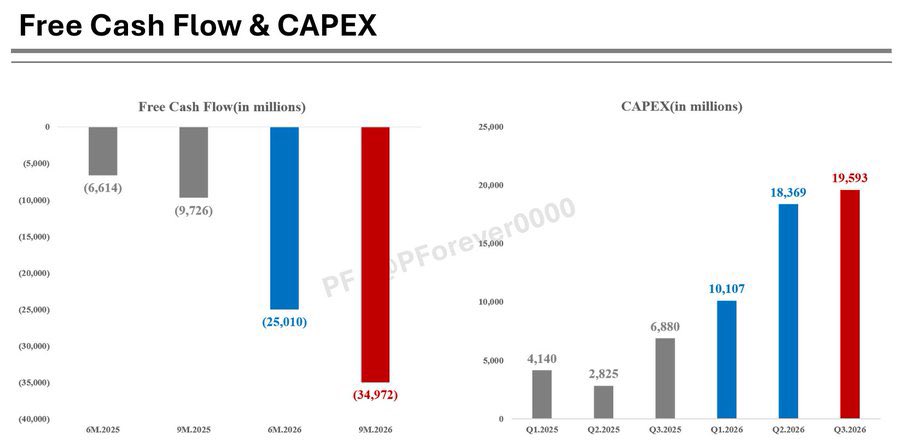
2. SpaceX is cash-flow constrained. It could raise more money in the stock market, but the investment opportunities in front of SpaceX offer some of the highest expected returns on invested capital(ROIC) of any company I’ve ever looked at.
3. Tesla, on the other hand, is about to enter the phase where its robotaxi network starts generating huge amounts of cash. And I don’t think Optimus is cash-constrained. The issue is execution. There are still challenges to solve on both the mechanical and software sides.
4. So if SpaceX could use Tesla’s free cash flow to launch AI satellites, the results could be enormous. Every business of a future-oriented company would come together under one roof: SpaceX, superintelligence, and Tesla.
In short, SpaceX has huge long-term opportunities, but it needs Tesla’s cash flow to get there.
The ones who really need this merger right now aren’t Tesla. They’re SpaceX and Elon.
If they really want to do it, they need to bring an exchange ratio generous enough to pass the shareholder vote on the first try.
Some influencers keep pushing the merger as if it’s the only option, without even mentioning a premium.
All that does is hype up retail investors and weaken Tesla shareholders’ negotiating leverage. That’s irresponsible, and it deserves to be called out.
Canaccord Genuity analyst George Gianarikas says those who viewed @Tesla’s Q3 earnings call negatively are “flatly wrong.”
"The tea-leaf readers whispering about a 'subdued' tone on the call are flatly wrong, in our opinion. This was one of the most unapologetically bullish Tesla calls in many a moon.
Think about it, on the call management said that:
• EVs have their highest backlog in 4 years, with Musk adding that "...we are producing and delivering as many cars as we can...".
• FSD attach rates surged to over 75% of new vehicle deliveries in North America (nearly a 20% QoQ increase), with active subscriptions reaching 1.74 million. Whoa.
• High-volume manufacturing of Optimus is officially underway in Fremont, yielding the company’s first production-grade humanoid robots built on a standard assembly line.
• Energy storage demand is "very strong" with Musk adding "We're actually almost sold out of all Megapacks for 2027, and we're ramping production as quickly as possible to meet demand. We also expect gross margins on that to increase meaningfully."
• Not to mention recent launches of the Cybercab, Tesla Semi, and Roadster (with the latter unlikely to be needle-moving).
Call us biased, but between that conference call commentary and shiny new product drops, Tesla appears to be dripping with growth potential. Count us in."
George reiterated a $442 price target for $TSLA.
This is f*cking insane. SpaceXAI engineer:
"99% of people use GrokBot for 1% of what it can do. They run one agent without loops or graphs
I run a team of 30+ GrokBot agents. By 7 a.m. my Chief of Staff has the day planned, my PM has handed out the work, and the workers have shipped half of it"
In this 1-hour session, SpaceXAI shows how to build that team from scratch
GrokBot → Chief of Staff → PM → Workers → Self-Improving Team
A loop sends every task back until it actually works
A graph lets one agent hand its result to the next without you in the middle
Anyone can ask GrokBot a question, almost nobody gives it a team to run
Worth more than most $1,500 agentic engineering courses
Watch it today
Then read how to build a fleet of GrokBot agents in the harness engineering guide below ↓
A lot of people seem to be putting their weight on SpaceX's near-term growth. If you look at the arguments for a Tesla-SpaceX merger "right now," that is mostly what they focus on, with Tesla playing a supporting role.
But SpaceX's current growth is all about data centers. And what props up that top-line growth is IPO proceeds and corporate bond issuance.
Cash flow over the next 1-2 years is going to get worse.
The heavy investment can only be sustained by continually raising money from outside. Credit spreads are getting worse, one macro shock could shake the whole data center industry, and even Republican areas are starting to push back on data center construction. In that environment, I don't see why these two companies need to merge right "now."
The two companies don't physically do a huge volume of business with each other, and there is no product ready for mass production yet. The synergy is only at the R&D stage, and that is entirely possible through a partnership under Elon's control. There may be some inefficiency, sure.
But what if they push the merger through under these conditions and it fails? There are plenty of cases where both sides agreed to merge and the deal still slipped on approvals in major countries (link). And the person at the center of that risk, as the key stakeholder in both companies, is Elon.
Watching everyone rush to calculate the premium as soon as merger talk came up, it seems like people aren't thinking much about Tesla's own growth, or about SpaceX's near-term growth risk. Or about the risk Elon could take on if this fails.
테슬라 로보택시 앱 26.10.0 숨은 코드 (디컴파일)
- 내 차 로보택시 등록 : 차량별로 골라서 플릿에 등록
- 등록 상태 표시 : 심사 중 / 활성 / 배차 중 / 해제
- AR 내 차 찾기 : 폰 카메라에 화살표로 방향, 거리 안내
- 사고 신고 : 승객이 앱에서 내용, 위치 입력
- 뒷좌석 원격 제어 : 등받이, 접기, 열선, 통풍, 공조
- 탑승 공유 : 실시간 위치 공유, 음악 대기열 같이 쓰기
- 고정 노선 셔틀 : 정해진 정류장 순환 (팔로알토 캠퍼스 정황)
cf. 수익 배분, 자격, 책임 조건은 코드에 없음
cf. 고객 차량 플릿 편입 (27년 2분기 전후) 준비 정황