Some love for $META recently but not nearly enough so that the stock would trade at its fair value.
Meta has so much room to grow for years to come:
- Single digit % organically (user growth)
- Double digit % ad placements (volume) think Whatsapp, Threads, Meta Glasses
- Double digit % ad pricing (sustainable as AI analytics will make these ads more valuable for buyers)
- Individual Subscriptions
- Cloud Computing
...Then add margin expansion from operating leverage.
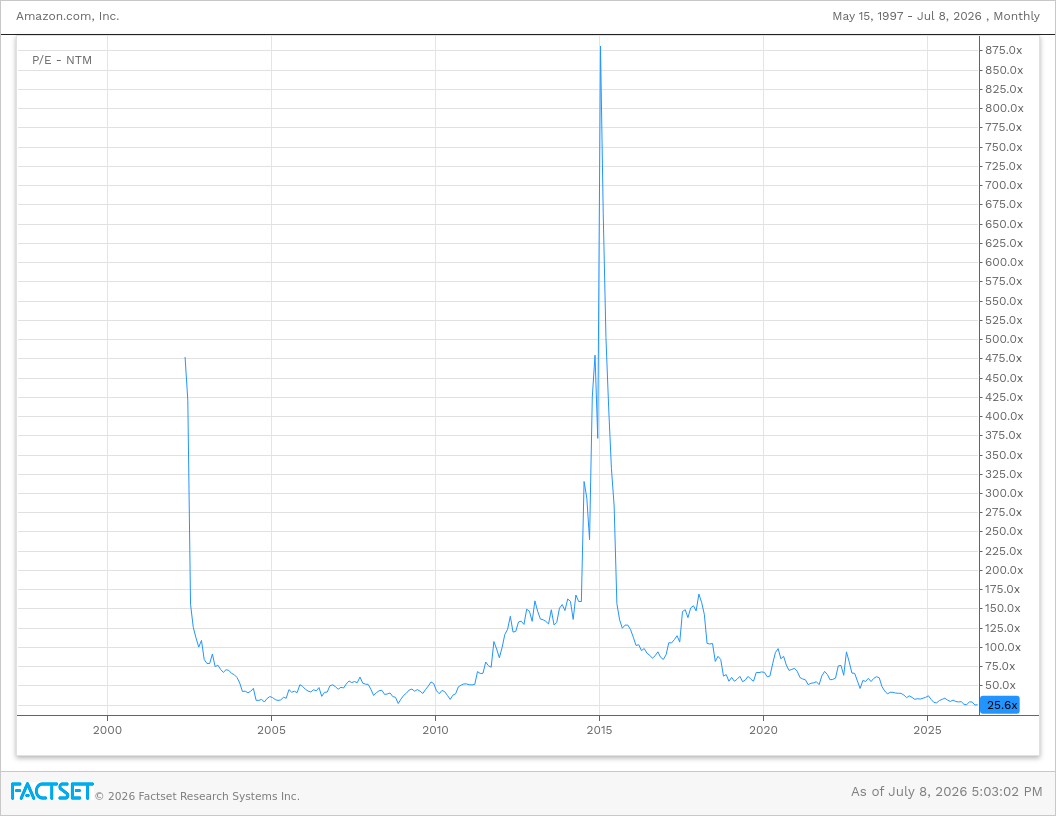
At 33% growth, which is accelerating, a 20X fwd. P/E, I simply cannot see how they will not outperform most stocks over the next few years.
Right now the AI suppliers (chips, memory, photonics) are hot but ultimately companies owning the customers and distribution will benefit.
Thats why $META is my second largest position today.
$SPY $QQQ
Of all sectors in the S&P500, the information technology sector is the most undervalued compared to its 5yr and 10yr avg forward P/E ratio.
The SaaS selloff likely did a lot to contribute to this. Nevertheless, I expect technology to continue outperforming.
Seeing some recovery already, lets see if this is the true low. Could see more volatility into hyperscaler earnings at the end of this month
$MU $NBIS $SKHY $GOOG $META $AMZN $MSFT
$HIMS
My take on HIMS earnings. 4% growth not even bad considering brutal YoY Q1 comps due to GLP-1 business discontinuation.
Guidance is super bullish, 23% YoY growth despite heavy transitioning and investments still needing time to pay off.
EBITDA margin guidance 11% -> implies last two quarters margins of 15% (above HIMS historical average)
-> do we see the unit economics inflection already despite much higher investments first?
That would be super bullish. The only other option is them guiding far too aggressive.
$AEHR
As nice as the story is, even when doubling 2028 revenue estimates of $120M -> $250M
And applying a 15X sales multiple (still fairly high) the stock would only return a total of 4%
There's simply better risk-adjusted opportunities in the market.
Nothing better than spending 30-40 hrs/week monitoring the markets, macro, and managing a portfolio
then underperforming a simple QQQ ETF
AND getting long-term anxiety from it
$HIMS
My take on HIMS earnings. 4% growth not even bad considering brutal YoY Q1 comps due to GLP-1 business discontinuation.
Guidance is super bullish, 23% YoY growth despite heavy transitioning and investments still needing time to pay off.
EBITDA margin guidance 11% -> implies last two quarters margins of 15% (above HIMS historical average)
-> do we see the unit economics inflection already despite much higher investments first?
That would be super bullish. The only other option is them guiding far too aggressive.