What you’re missing is that old long-term Treasuries can trade well below par when yields rise. Treasury can buy back $100 of face value for, say, $70, then finance that with shorter-term debt. So it can reduce both outstanding principal and near-term interest expense though it takes on more refinancing risk.
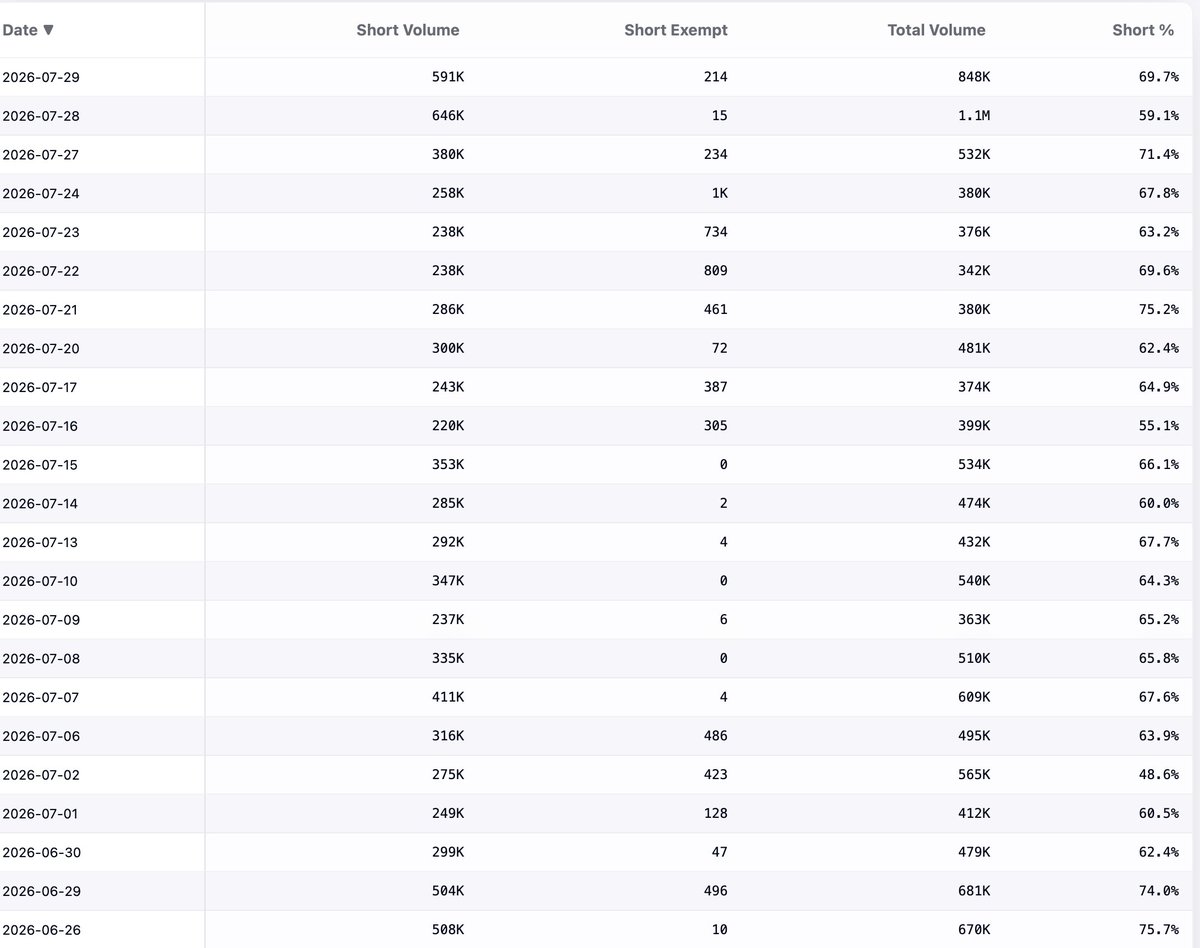
$ARE stock has been consistently shorted every single day for the past day. Assuming that it will fall in the next earnings just because the stock tanked in the past ones is a very risky bet for the short sellers, especially when peers that already reported Q2 are seeing demand coming back in the life sciences industry. Let's see how much they'll lose on this bet.
I asked Claude Code (no tickers) which companies are talking up AI in their filings, ranked by actual revenue growth.
It searched the filings, pulled the revenue figures, and ranked them via Equibles, my open-source, self-hosted MCP server.
$EBS over 20% short interest, with recent volume that is 20 days to cover. If new CDMO contracts are announced shorts can be squeezed. If management issues a non cash dividend that shorts can not replicate, they are trapped. Something like what Overstock did a few years ago can happen with EBS. A precedent was created, shorts lost in court against Overstock. Bullish.
$ARE valuation is ridiculous now. Mostly because momentum traders and algos just look that occupancy and rent forecast for the full year were revised down. What they don’t see is the footnotes that explain this happens because they no longer intend to sell a range of properties. Also capitalized interest is dropping because construction is ahead of time and thus FFO for Q4 was revised down. For me this is the most important and bullish insight of the full report.
“Our prior guidance for occupancy percentage as of December 31, 2026 and 2026 same property performance net operating income changes assumed a benefit of approximately 2% and 3%, respectively, related to a range of assets with vacancy that could potentially be sold in 2026 and/or qualify for classification as held for sale by December 31, 2026 but had not yet met such criteria as of December 31, 2025. Our updated guidance for these metrics assumes a reduced benefit of approximately 1% and 2%, respectively, related to a range of assets with vacancy that could potentially be sold during 2026 and/or qualify for classification as held for sale by December 31, 2026, **primarily due to our revised expectation that we may no longer sell as many assets with significant vacancy driven, in part, by positive leasing prospects for certain spaces that are currently vacant**”
Seems like $EBS finally has a pipeline for strong revenue growth. This 2.5x P/EBITDA makes no sense, they are literally buying 2% of shares outstanding EVERY quarter. Almost 20% short ratio. Hope to see a short squeeze, but even if it doesn’t happen my calls are going to print tomorrow.
$ARE I think this footnote makes a nice summary of how the market has already bottomed and is set for a recovery by the end of 2026.
“Our prior guidance for occupancy percentage as of December 31, 2026 and 2026 same property performance net operating income changes assumed a benefit of approximately 2% and 3%, respectively, related to a range of assets with vacancy that could potentially be sold in 2026 and/or qualify for classification as held for sale by December 31, 2026 but had not yet met such criteria as of December 31, 2025. Our updated guidance for these metrics assumes a reduced benefit of approximately 1% and 2%, respectively, related to a range of assets with vacancy that could potentially be sold during 2026 and/or qualify for classification as held for sale by December 31, 2026, **primarily due to our revised expectation that we may no longer sell as many assets with significant vacancy driven, in part, by positive leasing prospects for certain spaces that are currently vacant**”