$NBIS | We continue to expect to have 5 GW of contracted power by EO2026.
We now have more than 4 GW contracted, and have already expanded our contracted footprint with:
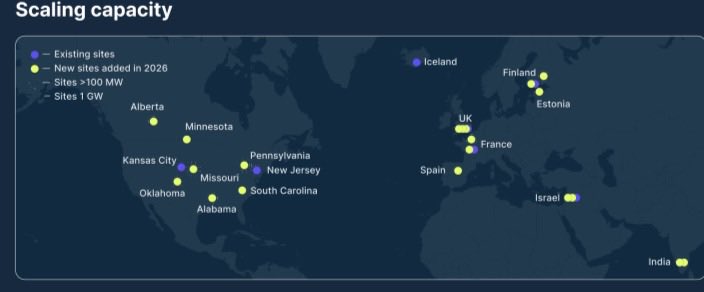
A 300 MW expansion in Missouri, where we now have 1.1 GW site under contract;
We secured exclusive site rights for a planned 100 MW multi-campus AI data center project in Alberta, Canada, with deliver targeted for 2027 and the potential to scale to several hundred megawatts.
A new 50 MW colocation in South Carolina, our eighth US site, is expected to come online in 2027;
Our first sites in the Asia-Pacific region, with two colocations in India expected to come online in 2027.
We are building across the US and international markets, selecting sites based on customer requirements, power availability, delivery economics and political environment.
$NBIS | We have secured all the power and components we plan to bring online in 2027, and are aligning construction with each site’s scheduled power connection.
$NBIS | We expect the following new owned sites to deploy capacity in 2027:
Missouri, Lappeenranta, our second Mäntsälä site, and Alabama.
At scale, these sites represent more than 3 GW, which we expect to be delivered over the next 3-3.5 years.
$NBIS | We have secured all the power and components we plan to bring
online in 2027, and are aligning construction with each site’s scheduled power connection.
$NBIS | In Q3, we delivered our biggest QoQ increase in active capacity to date.
Four new sites began generating revenue across the US and Europe, and we delivered additional tranches of capacity in New Jersey in Q3 and through November.
$NBIS | We have secured all the power and components we plan to bring
online in 2027, and are aligning construction with each site’s scheduled power connection.
$NBIS | In New Jersey, we now expect to have delivered more than half of the capacity contracted with $MSFT by EOY, with the remaining tranches now scheduled for 2Q27
$NBIS | We have secured all the power and components we plan to bring
online in 2027, and are aligning construction with each site’s scheduled power connection.
$NBIS | We introduced new pricing mechanisms to let the market set the benchmark:
Reserve auctions cleared more than 15% above our reserve price;
Live spot prices saw prices at times exceed our on-demand rate; and Short-term clusters, which are pricing at more than twice the reserved rate.
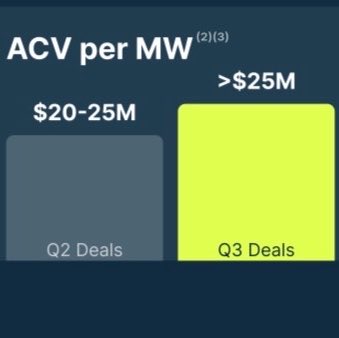
$NBIS | Annual contract value per MW exceeded $25M in Q3, up from >$20M on our Q2 deals.
Q3 prices rose, on avg, more than 20% per GPU-hour versus Q2.
$NBIS | Annual contract value per MW exceeded $25M in Q3, up from >$20M on our Q2 deals.
Q3 prices rose, on avg, more than 20% per GPU-hour versus Q2.
$NBIS | More than 90% of contract value signed in Q3 carried a prepayment, and the weighted avg prepayment as a share of contract value rose by ~20% QoQ
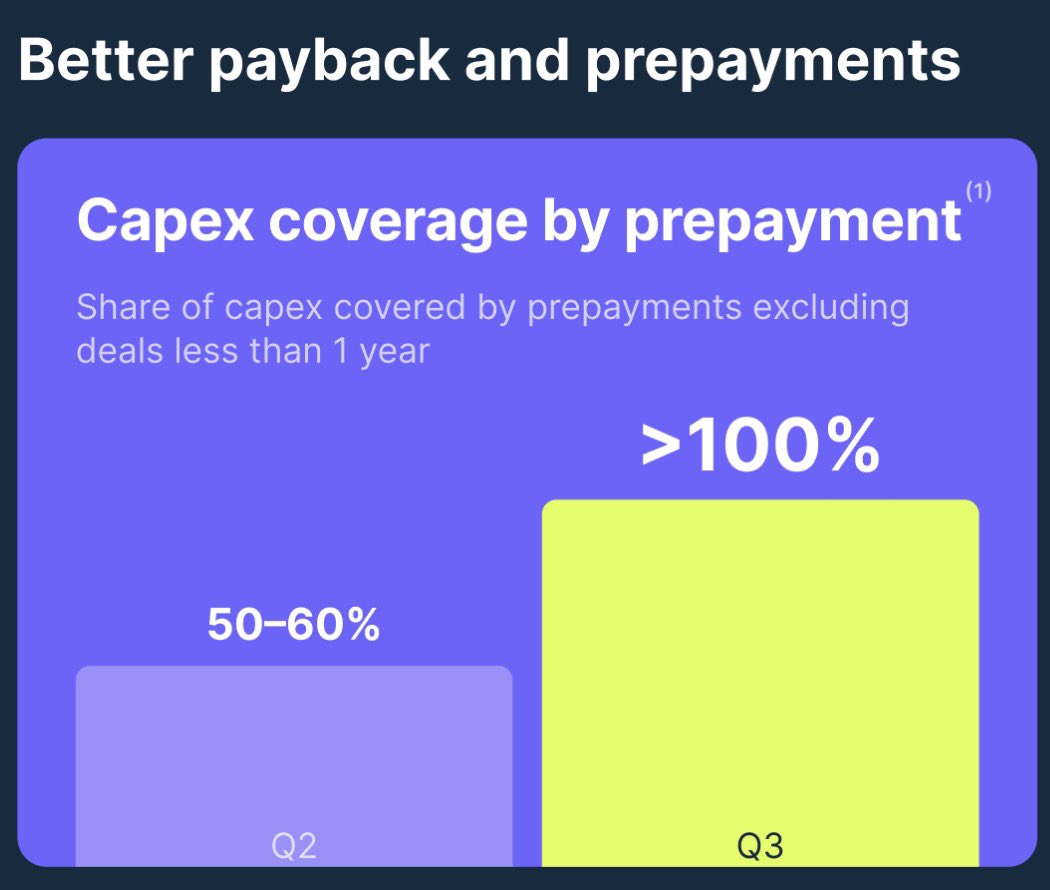
$NBIS | Prepayments on Q3 agreements covered more than 100% of the associated capex, including data center construction and networking, up from 50-60% in Q2.
This has continued rising on agreements signed so far in Q4.