“There are no beautiful surfaces without a terrible depth.”. I am not here to date or buy crypto. I don’t respond to DMs. I don’t want your investment ideas
X is a great platform. It’s a window into the minds of people who have anxieties and OCD on issues that either do not impact their lives or events that have not happened. The angst is real.
If you are distressed by anything external, the pain is not due to the thing itself, but to your estimate of it; and this you have the power to revoke at any moment. Marcus Aurelius, Meditations
Calling all RIAs, Family Offices, Emerging Managers:
A client is going to walk in and say "my brother-in-law is getting 15% on $SATS."
You need a better answer than "that's crypto."
Read the free primer ->
The Digital Credit Report
https://t.co/rJ2NEbouMX
The number I check every Monday is not the yield. It is the backing point: the bitcoin price at which each claim stops being fully covered.
By the latest filings: Strategy's senior stack about $14k. $SATA about $20k. $SATS about $36k.
Pull up bitcoin, look at the distance to those three numbers, and you know more than most of the yield chasers.
https://t.co/e1C3tSzNL0
Stupidity is not a superpower. This moronic take has to be the funniest and dumbest take because FrostByte doesn’t understand the model. It is painful to watch him post garbage with zero understanding. This is what you get from the low IQ unable to critically think people that are on X.
$OPEN - My opinion is this business model is a bad one. A seller can go to their website, enter their address and get an offer and then wait. They'll send you some follow up texts and emails.....and then they will increase the offer on the house if you don't respond (because their business model is to buy as many houses as possible). Meanwhile, you call a local realtor and ask them to walk through your house and give you an estimate on what they think you can sell it for - they know the neighborhood, they know potential buyers, they can see with their own eyes if the street is busy, if the layout of your house is weird, if there are issues that they know will hurt the value of your house. If Opendoor's offer his higher than the broker's estimate, you sell to OpenDoor. So what is the result? Likely, Opendoor has overpaid. They don't have the same knowledge of the neighborhood...AI can't detect a barking dog or highway noise or airplanes that fly overhead. $OPEN buys the house, they fix it up, put it back on the market....only to realize they need to sell it for less than they paid for it.....thus a loss on nearly every house (even if they get a 5% commission). Its a bad business model. Its been tried before and hasn't worked. @nejatian hasn't realized this yet (or maybe he has and is giving it one last push). And adding Mike Alfred to the Board is just icing on the cake...Board meetings will now last twice as long as Alfred will speak for an hour and say nothing (chart squiglers, kid analysts, squeezing the shorts, filet mignon, and his favorite wines). This is a common sense business and everyone can track their progress daily using the internet and AI. My thesis continues to show up in their numbers....please let me know when you see a change in the numbers.....would love to buy a stock at $1 and sell it at $10. If the CEO can't get the stock above $6, he is basically working for free and will move on....likely a 2027 event. Please let me know when you see a change in direction for this company....show me them buying a house and selling it for more, over and over again. This will only work in a booming housing market (for only that period of time) and then revert back. Let me know when you see a turn in the business.....would love to see it and buy the stock. But they are now projecting a Q4 EBITDA loss of $70mm - $85mm and a sequential decline in "contribution profit dollars" as they "continue selling into a difficult market" - so why the heck are they BUYING in a difficult market? To keep their market share I believe is their nonsensical response. This was a SPAC by @chamath along with Virgin Galactic, Clover Health, Akili Interactive, Pro Kidney, Desktop Metal (solana:5DxioZwEeAKpBaYC5veTHArKE55qRDSmb5RZ6VwApump), Proterra, Metromile, Latch, Sunligh Financial, ReNew Power, etc..... $CLOV $SPCE, $AKLI, $PROK
@FrostByte123456 You were a hedge fund with zero critical thinking. SBCs are front loaded. Understand the accounting dynamics. My goodness you have myopic understanding of finances
Bitcoin isn't trading on bitcoin right now. It's trading on liquidity.
When $64B has to be raised for one listing, the most liquid collateral on earth gets sold first. That's what June was. That's what this is.
The drain ends the day the deal prints. Then the bid comes back, and it comes back all at once.
This is the retest, not the top. 😎
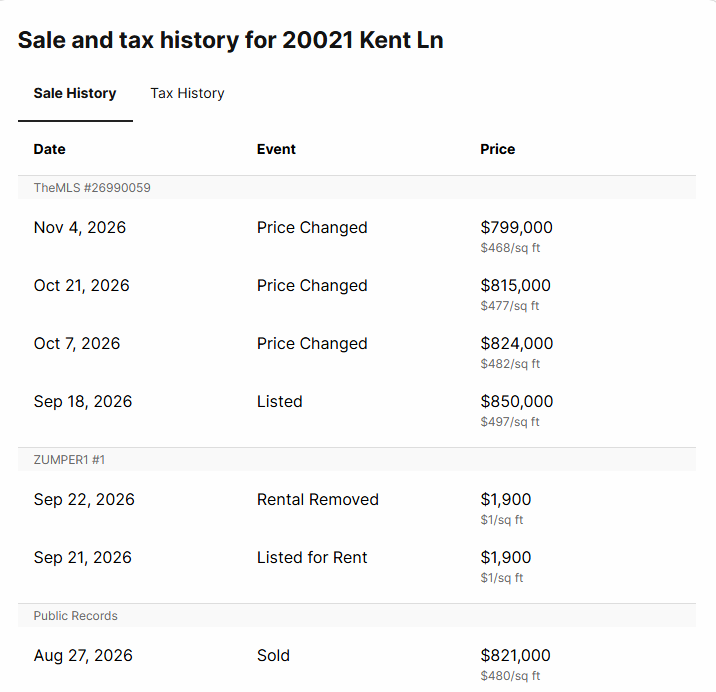
Cute math. Opendoor doesn’t pay the MLS ask — they negotiate the purchase price down with the seller, often twenty to thirty grand under list. So that eight twenty-one buy number isn’t the real cost basis. Factor in the actual negotiated price, the holding costs, and the fact that they still sold near asking in a softening market, and the loss story gets a lot thinner. But sure, screenshot the Redfin page and call it a day.
@nejatian@HiralKanaiya@grok From Redfin. $OPEN bought this house for $821,000. Nearly 3 months later, it is now on the market for $799,000. This accurate?
Ross, the $440M came from $650M in zero-coupon converts. Zero coupon means 0%. The only real interest Opendoor paid in 9 months was $80M on $3.1B of debt — about 3.5%. Your 23.7% is what happens when you take a financing cost, dress it up as an interest rate, and pray nobody reads the footnotes. Shareholders didn’t pay 23.7% on anything. They got a 5% buyback, capped calls blocking dilution below $10.38, and 4 years before those notes can convert. If you think the trade was bad, say so. But don’t manufacture a rate that doesn’t exist just to make it sound worse.
@RealOpenArmy Lets be honest.
Even if the Penalty was 200% that only binds these execs to the same price they forced shareholders to pay when they initiated that $440 million cash on hand play?
All shareholders should be asking why they were forced to pay 23.7% interest on the $440 mill?