@Flynnneil@JoshXLs_@Peterg9wd@OswaldPer4mance@fynnvestor Don’t forget from the start of the next tax year a flat 22% tax on any interest (or equivalent return) paid on cash held inside a non cash ISA, such as a stocks and shares ISA.
Positions I have mentioned publicly on X. (This is not financial advice and never was. NFA, DYOR).
Approximate move from the post date to now:
$NBIS (Jun 2025) about +379% #Bitcoin (Dec 2021 “not too late”) about +81% $CRM (Jul 2026) about +45% $BABA (Jun 2026) about +13% $BIDU (late Sep 2026) flat $GNS (Jun 2025) about −86%
4 of 6 positive (BIDU only mentioned earlier this week). Windows differ, entries were research notes not timed buys, and one loser matters.
Past performance is not a guide. Position sizing to mange risk is essential.
JUST IN: America's largest #1 investment advisor, Ric Edelman just said he recommends a #Bitcoin allocation of up to 40% for his clients.
"A 1% or 2% allocation is way insufficient. We need to increase our allocations."
"We've got the market performance on our side." 🔥
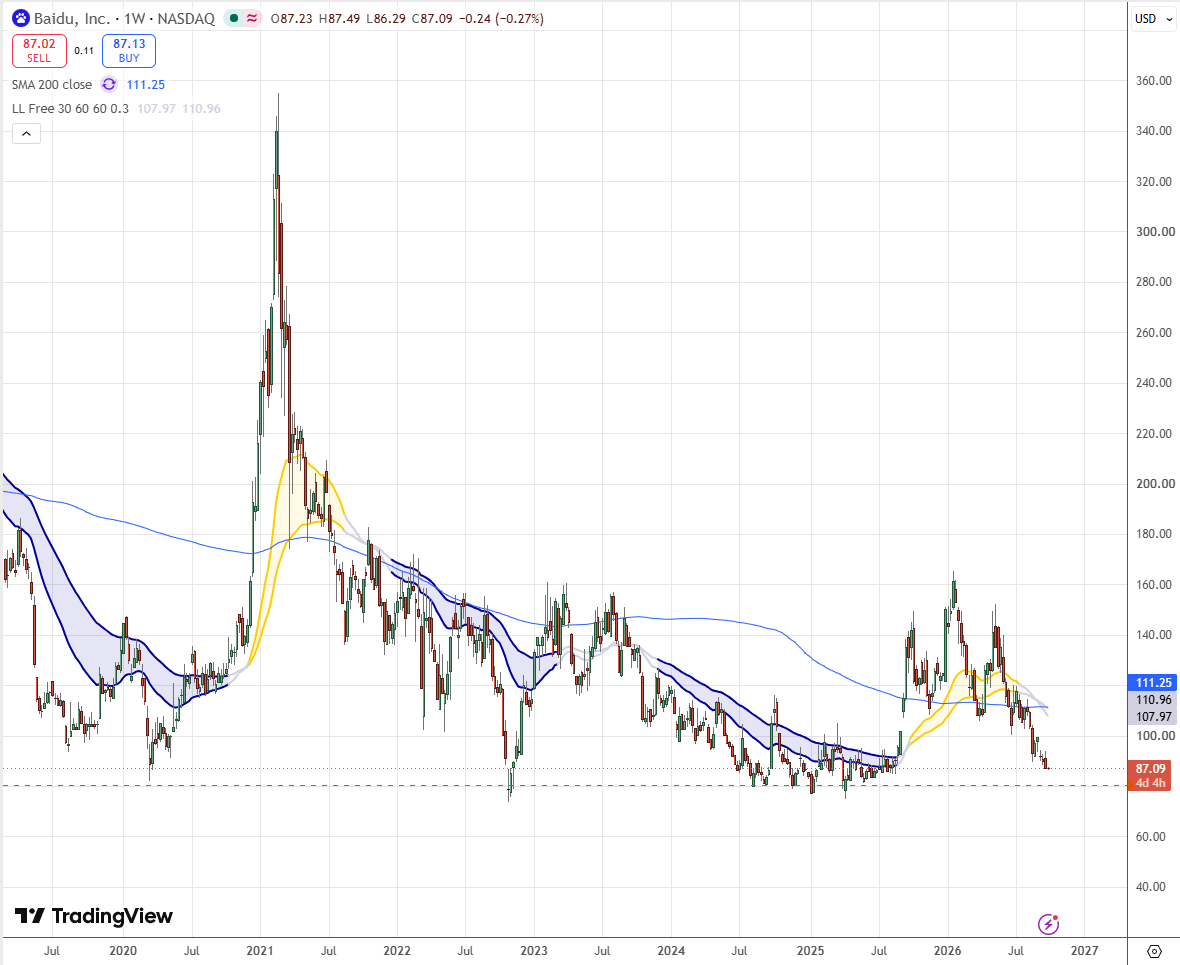
I have been researching Baidu $BIDU recently its AI chip arm "Kunlunxin" is reportedly targeting a Hong Kong IPO at around $50bn and Baidu's entire market cap is only about $30bn.
So the market is saying the subsidiary is worth more than the parent that controls it. Which is either a serious mispricing or a serious red flag. The $50bn came from a single report that Reuters picked up and explicitly couldn't verify.
But what is interesting to me is that despite Baidu's search business is genuinely declining, its Core AI revenue grew 25% and now makes up half of general business revenue. There's a robotaxi operation with 350m+ autonomous kilometres running in 28 cities, now on Uber in Dubai.
Looking to the charts, the stock is trading at a discount to its 200 week moving average and trading around a key support level. NFA DYOR
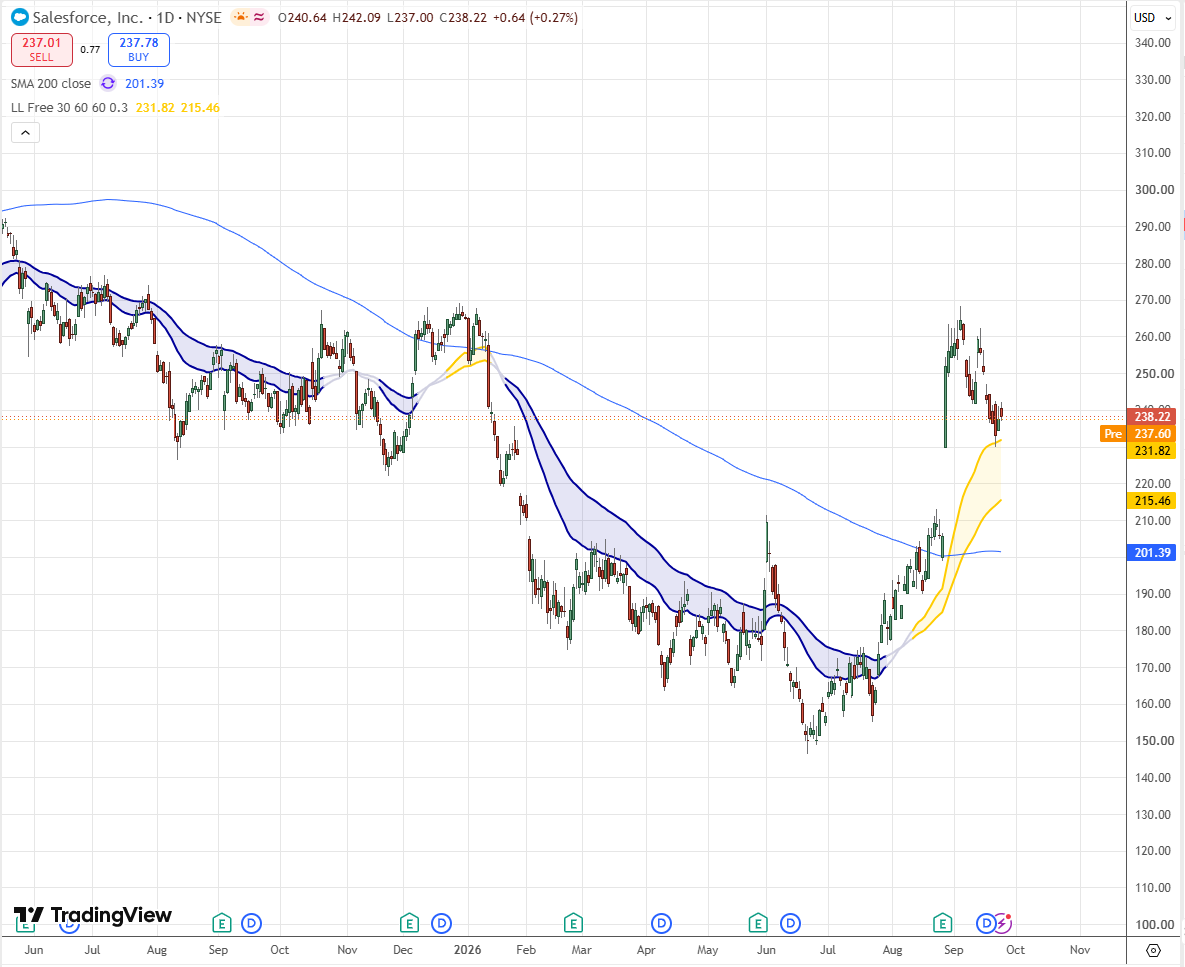
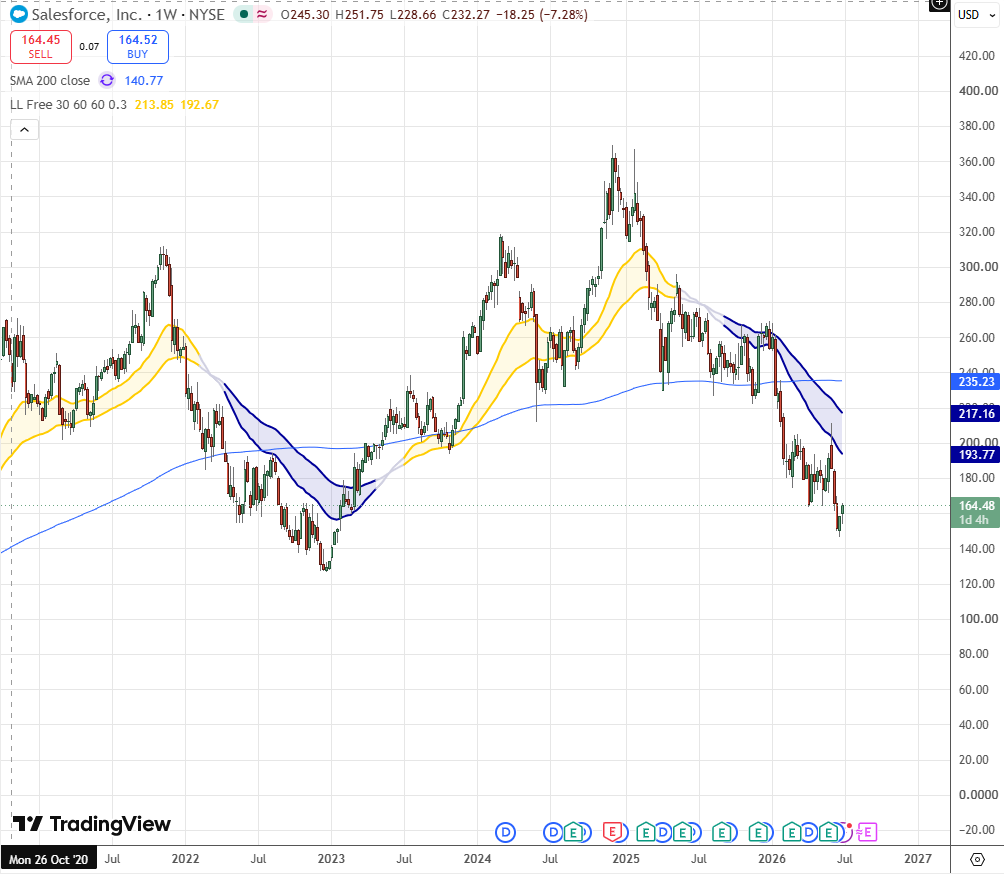
Been thinking about $CRM lately. Everyone’s scared AI is gonna kill Salesforce, but honestly? It feels like the opposite.
That data moat is ridiculous decades of customer history and integrations no one wants to rip out. Their Agentforce stuff is already taking off. At these valuations it just looks cheap if you believe the moat holds.
Am I missing something?
@001Player79318@pete_rizzo_ because they want dollar-denominated value that still settles on the most secure network without wrapping, extra validators, or a public ledger everyone can watch.
Schools won't teach your kids this. So you have to.
If I could sit every child down before they leave home, here's what I'd want them to actually understand about money:
How banks really work: When you deposit £100, the bank keeps a fraction and lends the rest out, and that lending is how most money in the economy is created. Understanding this means understanding why banks can fail, and why "my money is just sitting there" isn't quite true.
Start investing the day you can, not "when you have more": £200/month from 25 vs from 35, both to 65, at 10% average returns. The 25 year old ends up with roughly 2.8x more (around £1.26m vs £450k), despite putting in only 33% more overall. The biggest advantage you'll ever have with money is time, and you only get to use it once.
Don't pay someone to do worse than a tracker: 85 to 95%+ of professional fund managers fail to beat a plain S&P 500 index fund over 10 years once fees are counted. If the "experts" mostly can't beat a boring tracker fund, be very sceptical of anyone promising to make you rich through stock picking.
The state pension isn't a savings account: National Insurance doesn't get invested for you. It pays today's pensioners directly, and future workers will pay yours. Don't assume the state will be enough. Plan like it might not be.
Tax isn't as simple as "work hard, pay your share": Money from wages (income tax plus NI) is taxed harder than money from investments or dividends. Learning how income is classified, not just how much you earn, matters more than most people realise, and it's legal, common, and rarely explained.
Inflation quietly eats cash sitting still: Money in a low interest savings account loses real value every year prices rise faster than that interest. Saving isn't the same as growing. Know the difference.
Good debt vs bad debt: A mortgage or student loan can build wealth or earning power over time. Credit card debt at 20%+ APR destroys it just as fast. Compound interest works against you exactly as hard as it works for you, same maths, reversed.
Marketing is engineered to make saving feel bad and spending feel good: Almost everything in your financial environment, from ads to "buy now pay later" to social media, is designed to make delayed gratification feel like the loser's choice. It isn't.
If a return sounds guaranteed and high, it's not real: Anything promising "guaranteed 20% returns" with no risk is either a scam or hiding the risk from you. Real returns always come with real volatility.
None of this is taught in school. All of it shapes the rest of their life. Teach it early.
Partially. Apple posted a job for Apple Pay Financial Product Strategy Lead (Apple Card/Cash team) listing understanding of stablecoins, tokenized deposits, and blockchain as preferred quals. It's exploratory strategy work, not an announced "Crypto Lead" hire or Bitcoin/crypto adoption in Apple Pay. No product launch confirmed.
Are you learning Spanish? 🇪🇸
I’ve got 3 spare Super spots on our Duolingo Family Plan and I’d rather give them to people who are actually putting the work in.
If you already have a 100 day streak (or more), you can have one for free. Each spot is worth about $12.99 a month if you bought Super on your own.
How it works:
•Follow me here on X: @dazeaston
•Scan the QR in this post, or search @DarrenEaston on Duolingo, and follow me there too. That QR is just the follow link.
•Reply to this post with a screenshot of your Duolingo profile showing your current streak and that you are on Spanish.
I’ll pick the first 3 who have done all three things and send the Family Plan invite privately.
A few important bits:
• It is FREE. I am not selling spots.
• You cannot already have an active paid Super or Max subscription. If you do, you would need to cancel and wait for it to run out first.
• Your existing streak and progress stay exactly as they are.
• If you unfollow me on X or Duolingo at any time, or break your streak I will remove you from the plan.
If that sounds like you, follow on both, then drop the screenshot below.