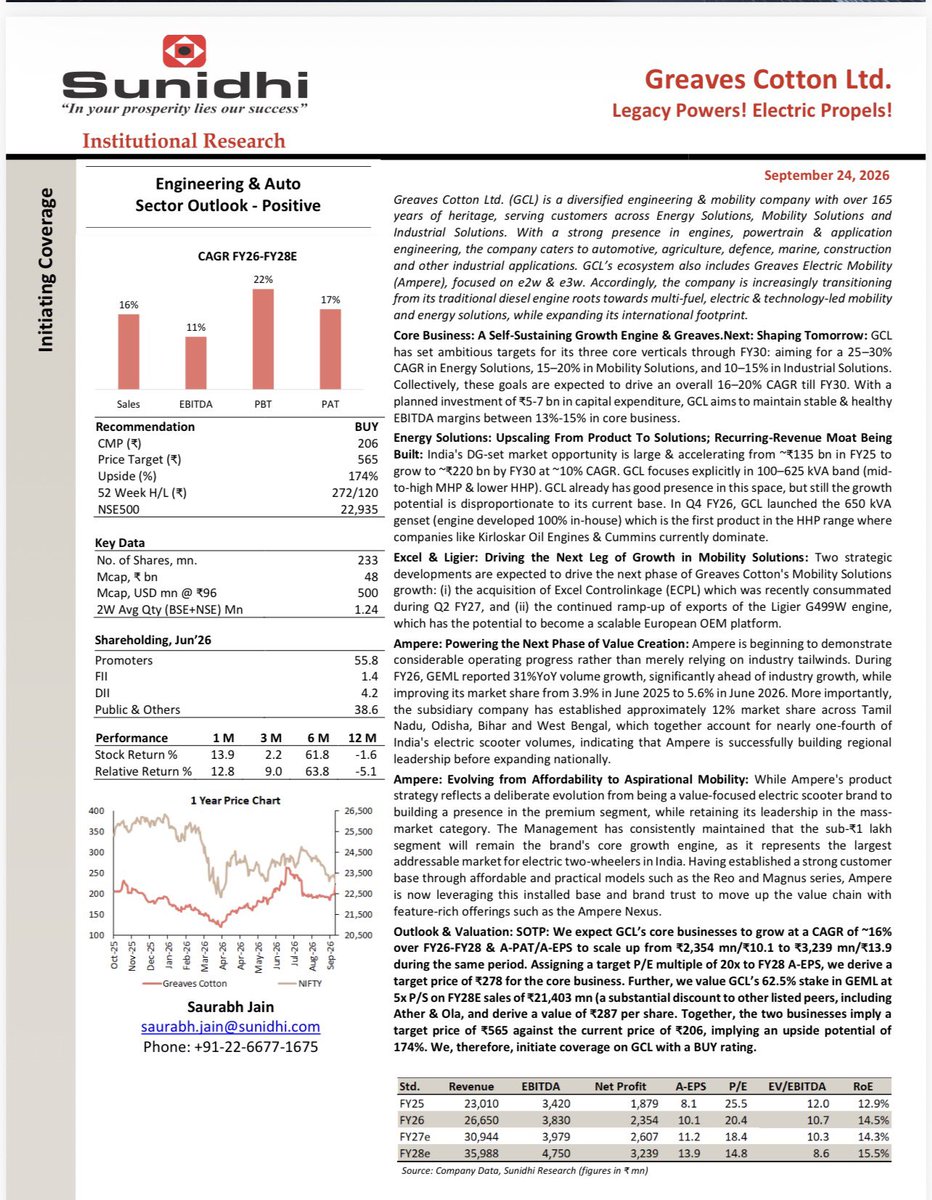
Centum has built decades of trust in regulated & high - barrier segments with DRDO, ISRO & large PSU defence players. Order book of ₹1800 Cr has grown 32% YoY. Co has guided for 25-30% revenue CAGR over medium term with EBITDA margin of 13-15%. TP ₹5900 https://t.co/KjSYD0LNhG
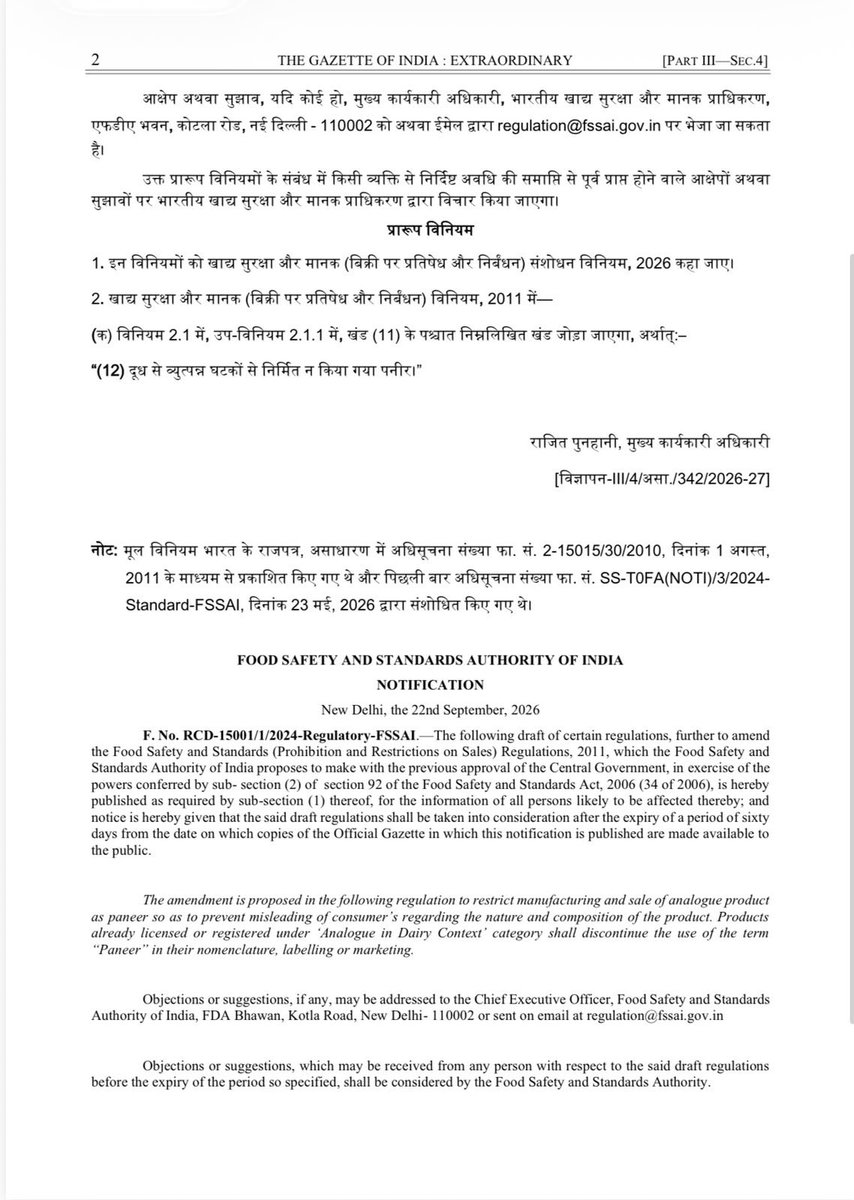
FSSAI proposes to ban the sale of analogue paneer made from constituents not derived from milk. The proposal seeks to safeguard consumer interests and ban the practice of marketing analogue products as paneer.
Can AI find a great company, or understand what makes one great for a decade?
I will explore this with long term investors and family offices at ET Alpha Wealth Summit 2.0.
What would you ask? Who knows? Your question may change the conversation.
https://t.co/GvypPHZIng
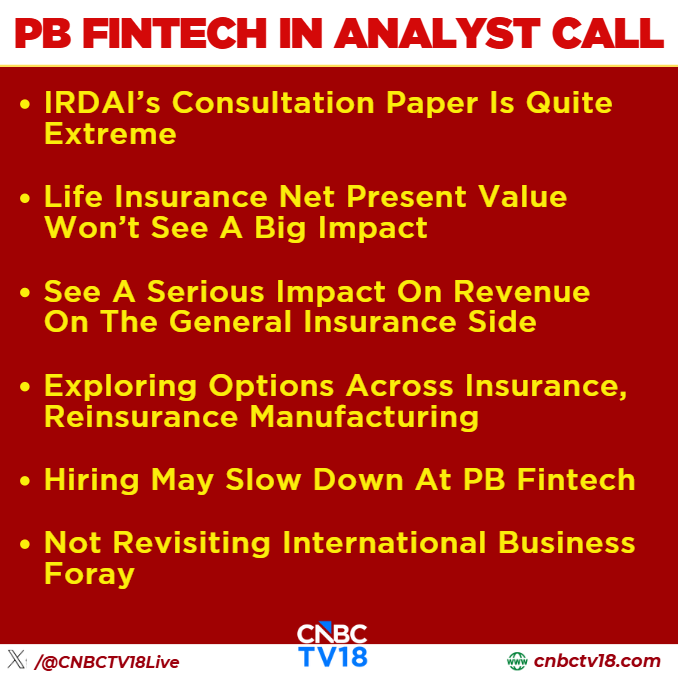
#NewsFlash | #PBFintech In Analyst Call Says Larger #Agents May Not Find It Lucrative To Sell At Proposed Commission Levels
👉If Distribution Was The Engine, Taking It Out Won’t Make The Car Lighter And Faster
👉Doesn’t Seem Convincing That Agents Get Paid Higher Commissions Than PoSP
👉We Have A Distribution Consultation Paper Without Inputs From Distributors
3 Big block deals today as per @VivekIyer72
1.Nephroplus Health
Multiple Sellers
Offer Price at 705; 5% discount
Base Offer Size*- upto 5.5% of total equity amounting to 400cr
Upsize Option - Up to 3.4% amounting to 250cr
Total Offer Size of 8.9% amounting to 650cr
2. Sedemac Mechatronics
Muliple sellers
Floor Price: Rs 3000/sh
Offer Size - Up to 10%
Offer Size - Rs 1329cr
Lock-in of 60 days on further sale of shares
3. Bluestone
Sellers: Accel India III (Mauritius) & 360 ONE AAM Funds
Floor Price: Rs 800/sh (6.5% discount)
Total Offer Size: 5.6% of total equity
Amounting to Rs 728.5 cr
Lock-in of 60 days on further sale of shares
@CNBCTV18News
🚨 Block Deal | Sedemac Mechatronics
• Sellers: A91 Emerging Fund II, Xponentia entities, Mace Pvt & HDFC Life
• Floor Price: ₹3,000/share — 1.2% discount to NSE close
• Deal size: Up to 10% of existing total shareholding, 4.43mn shares
• Offer value: ₹1,329 Cr
• 60-day lock-in on further sale of shares
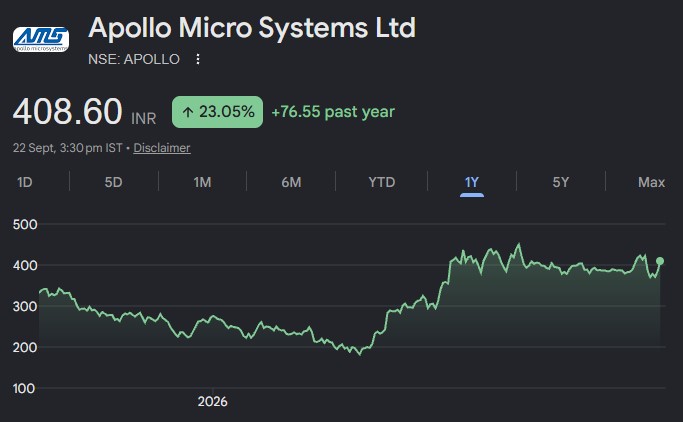
Apollo Micro Systems is transitioning into a complete integrated weapon systems OEM. Earnings growth expected to be robust in coming period led by strong execution, consistent order inflows & rising contribution in key defence systems. TP ₹485 (25% upside)https://t.co/zD0ngBvBNB
IRAN HAS INFORMED THE TRUMP ADMINISTRATION THAT IT WILL OPEN THE BLOCKED STRAIT OF HORMUZ "WITHIN SEVEN DAYS" IF IT ACCEPTS DEMANDS SUCH AS LIFTING THE US MILITARY BLOCKADE OF IRANIAN PORTS, ACCORDING TO A SENIOR IRANIAN GOVERNMENT OFFICIAL ON THE 22ND. WITH IRAN'S CRUDE OIL EXPORTS VIRTUALLY HALTED DUE TO THE PORT BLOCKADE, IRAN IS TRYING TO BREAK THE PROLONGED STALEMATE BY MAKING THIS MOVE. - KYODO
IMPORTANT: American media offers a lesson to India and the world. When powerful leaders assault a free press, solidarity is the strongest defence. United we stand, divided we fall. If media houses compete for power’s favour instead of defending press freedom, they risk losing the very freedom that allows them to exist. https://t.co/qZPA4UYL3i
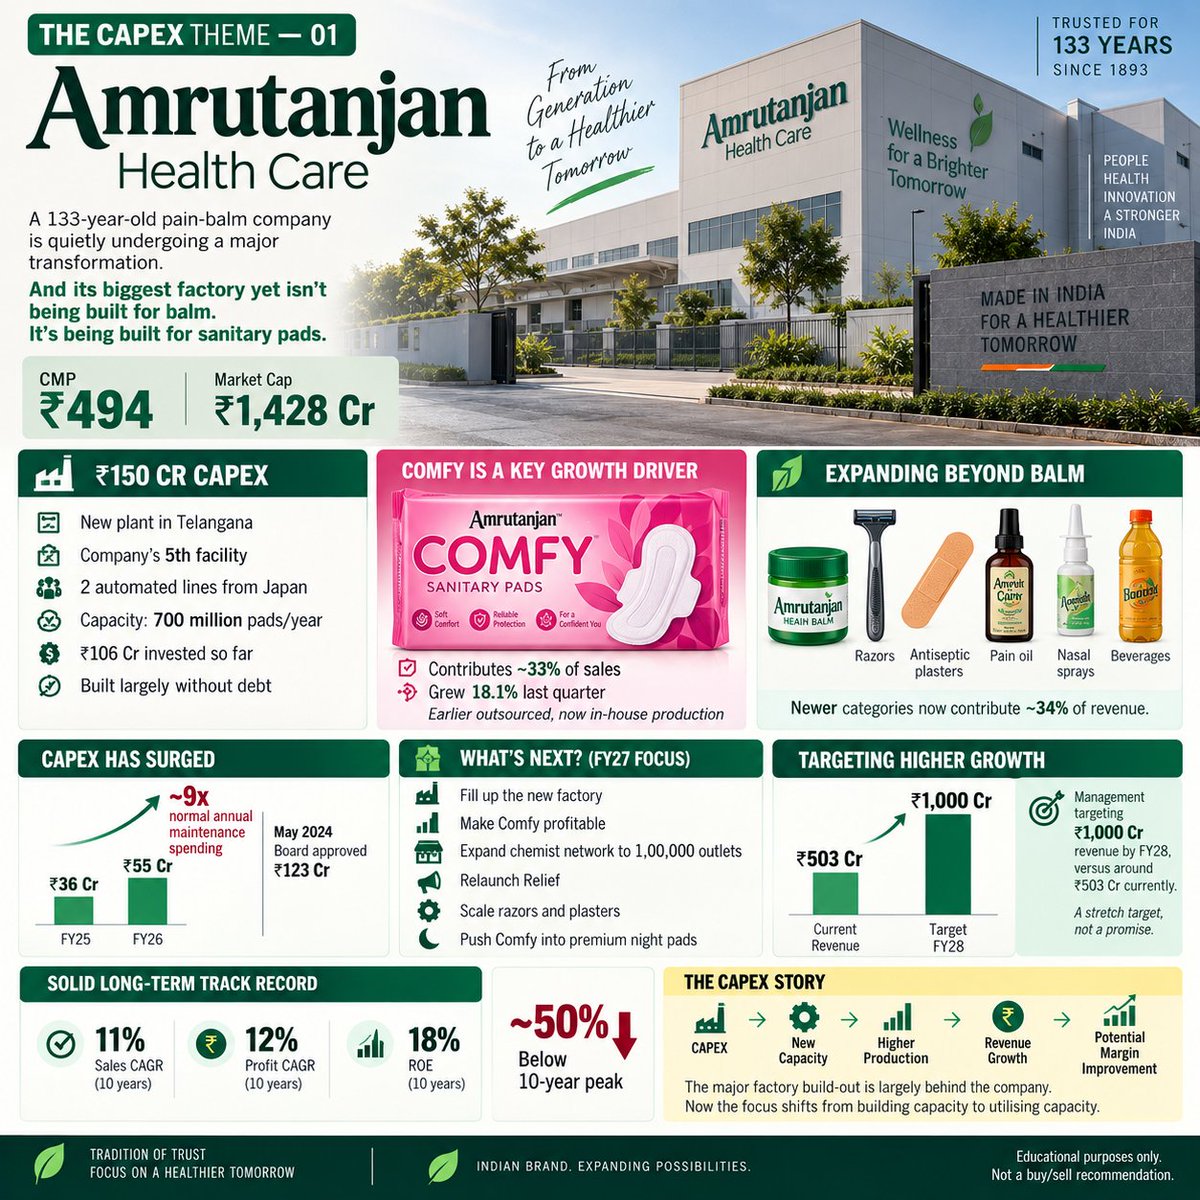
THE CAPEX THEME — 01 🏭
Amrutanjan Health Care
CMP: ₹494
Market Cap: ₹1,428 Cr
A 133-year-old pain-balm company is quietly undergoing a major transformation.
And its biggest factory yet isn't being built for balm.
It's being built for sanitary pads.
🏭 THE ₹150 CR CAPEX
🔹 New ₹150 Cr plant in Telangana
🔹 Company's 5th manufacturing facility
🔹 2 automated production lines from Japan
🔹 Capacity: 700 million sanitary pads/year
🔹 ₹106 Cr invested in the plant so far
🔹 Built largely without debt
Amrutanjan has been selling Comfy sanitary pads for years, but production was outsourced to contract manufacturers.
Now, the company is bringing production in-house.
Comfy already contributes around 33% of sales and grew 18.1% last quarter — before the new plant fully ramped up.
📈 THE BUSINESS IS EXPANDING
The transformation isn't limited to sanitary pads.
The company has expanded into:
🔹 Razors
🔹 Antiseptic plasters
🔹 Pain oil
🔹 Nasal sprays
🔹 Beverages
These newer categories now contribute around 34% of revenue.
💰 CAPEX HAS SURGED
May 2024: Board approved ₹123 Cr for the new sanitary-pad facility.
FY25: ₹36 Cr spent
FY26: ₹55 Cr spent
That's roughly 9× its normal annual maintenance spending.
The major factory build-out is now largely behind the company.
Management has indicated that there is no major foreseeable CAPEX after the remaining building expenditure.
🎯 WHAT'S NEXT?
FY27 priorities:
🔹 Fill up the new factory
🔹 Make Comfy profitable
🔹 Expand chemist network toward 1,00,000 outlets
🔹 Relaunch Relief
🔹 Scale razors and plasters
🔹 Push Comfy into premium night pads
Management is targeting ₹1,000 Cr revenue by FY28, versus around ₹503 Cr currently.
They describe this as a stretch target, not a promise.
📊 THE NUMBERS
🏷️ Nearly 50% below its 10-year peak
Yet the business has delivered:
11% Sales CAGR
12% Profit CAGR
18% ROE
over 10 years, while expanding into new consumer categories.
The more recent numbers are mixed — 5-year profit CAGR is 1% — making execution of the new capacity an important factor to watch.
🔄 THE CAPEX STORY
The interesting part is the sequence:
CAPEX → New Capacity → Higher Production → Revenue Growth → Potential Margin Improvement
The company spent heavily while the new plant was still under construction.
Now the focus shifts from building capacity to utilising capacity.
CAPEX cycle → Capacity utilisation → Business expansion
That's the part I'm tracking.
Educational purposes only.
Not a buy/sell recommendation.
❤️ Like | 🔁 Repost | 🔖 Bookmark | 🔔 Follow
CAPEX THEME — 01
More companies from the CAPEX cycle coming next.
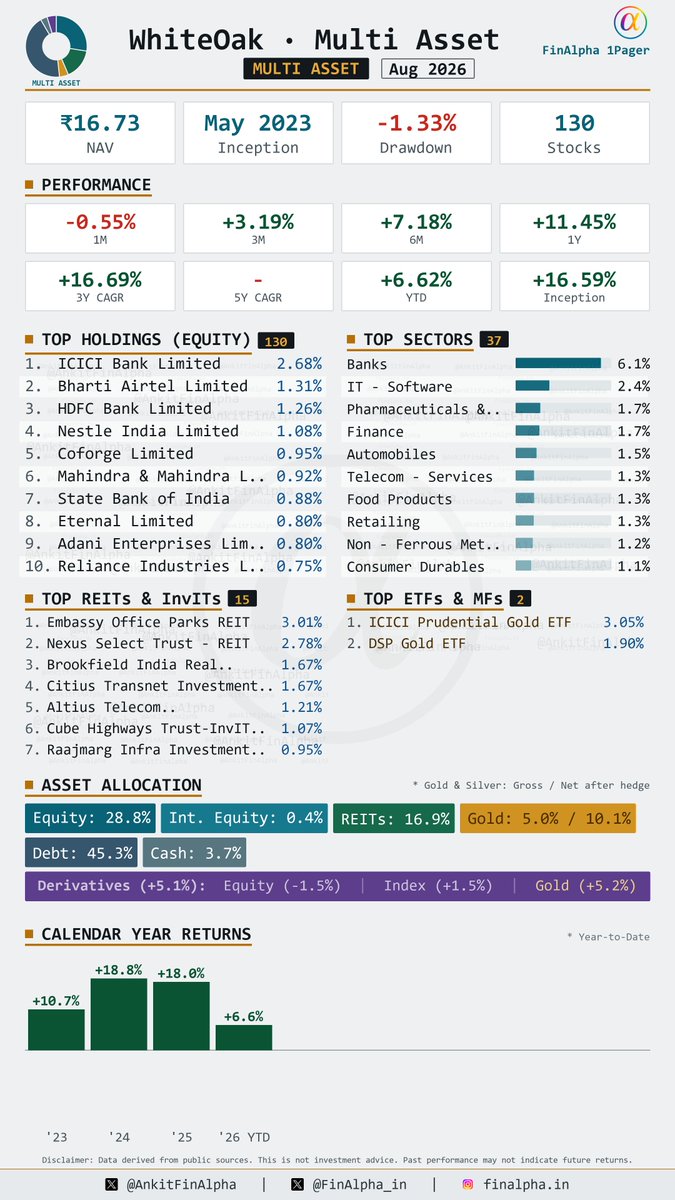
WhiteOak Multi Asset Portfolio Update (Aug 2026) 📊
A decisive move toward safety at WhiteOak this month! Debt allocation surged by nearly 9% to hit 45.3%, funded by broad profit-taking and a clean exit from 8 names including Fortis Healthcare and Jyothy Labs.
Silver is out from the portfolio ( last month also was a net zero exposure)
Asset Allocation Changes:
Equity ⬇️
International Equity ⏸️
Reits/InvITs ⬇️
Gold ⬇️
Silver ⬇️
Debt ⬆️
🟢 11 Fresh Buys (Hindustan Copper, UltraTech Cement, Shiprocket, Symbiotec Pharmalab, Horizon Industrial Parks, JSW Steel, Skyways Air Services, Molbio Diagnostics, Behari Lal Engineering, Milky Mist Dairy Food, Tempsens Instruments)
🔴 8 Full Exits (Fortis Healthcare Ltd 📉, Godrej Consumer Products Ltd 📉, GE Vernova T&D India Ltd 📉, Mastek Ltd 📉, Jyothy Labs Ltd 📉, Awfis Space Solutions Ltd 📉, Indo-Mim Ltd 📉, Cholamandalam Financial Holdings 📉)
📈 7 Increase in Holdings (Including: Embassy Office Parks REIT, Bharti Airtel Ltd, Cube Highways Trust, Axis Bank Ltd, Juniper Green Energy Ltd)
📉 16 Decrease in Holdings (Including: ICICI Bank Ltd, HDFC Bank Ltd, State Bank of India, Mahindra & Mahindra Ltd, Adani Enterprises Ltd)
⏸️ 111 Companies - No Change (Held steady on: Nexus Select Trust, Citius Transnet, Brookfield India Real Estate, Coforge, Eternal Ltd, etc.)
The fund remains highly diversified , anchoring portfolio risk with a heavy debt cushion.
Detailed 1-Pager attached! 📄