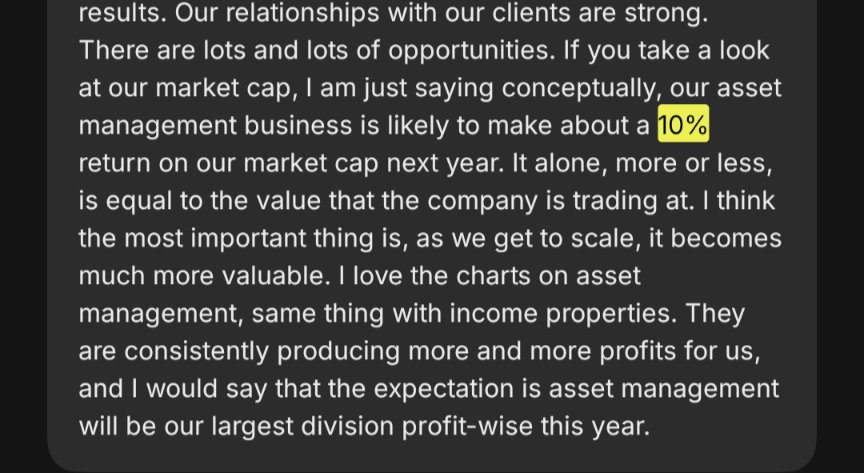
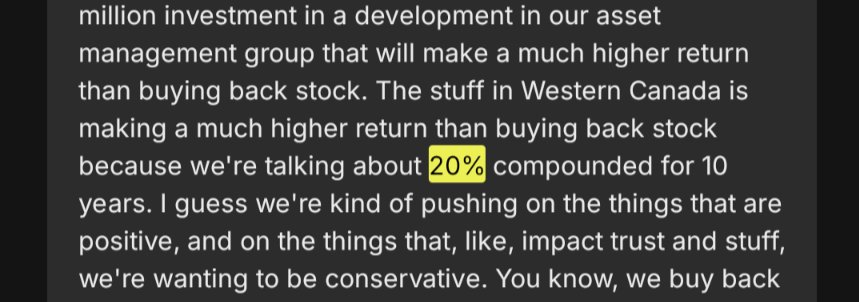
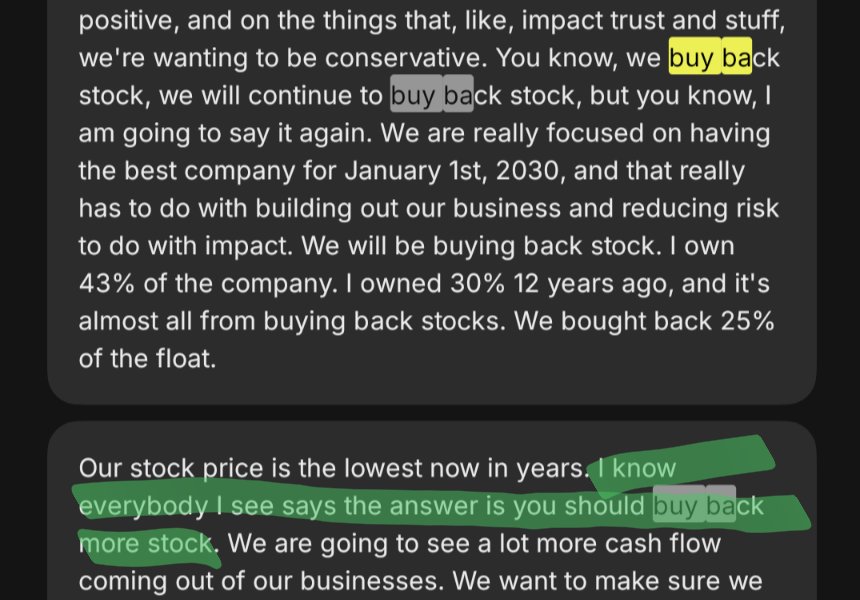
@Rodbhar Again, they should be left with a bunch of cash flow, balance sheet capacity and assets & I mean even $2B AUM mandate 50:50 D:E is like $100M cash (probably over 18months +) which would be needle moving for this size (& what western Canada can generate)
@Rodbhar I'm not going to argue much but would say that the Cashflow from WC land division should provide way more capital than it looks like they'd know what to do with already.
@Rodbhar Honestly I wonder if the play is just to be a shadow BAM and pay out 100% of the AM income via dividend and keep the assets/cashflow to grow NAV in the background
At least there'd be something for people to gravitate towards.
@Grainjones I know particularly in Ecuador, they've been working on building out the ore sourcing network for a while. They always sound more cautious on sourcing in Africa vs for Svetlana so I think they have some ideas there.
A USD$268 Billion company established a working relationship with a CAD$677 Million company so the $268B company can manufacture more efficiently... Because the $677M company has 'world class manufacturing plants'
*Not Sarcasm*
@StockTalk416 I honestly think that the market won't care about the assets more than a minor multiple of their cashflow until they get spun out.
I also think that at this point, the Asset management should be enough to move the stock going forward.
Agree some stuff is very frustrating.
@QuinnCadman My thinking was actually the time to buy would be around the gap close... If it goes another 5% it would more likely mean it's back in the range for a while.
TBD.
Would be funny and fitting if these Goeasy earnings drag Propel to close its earnings gap then have it remember it's a completely different company as its own earnings just demonstrated... So it goes on to look forward.
Dynacor $DNG.TO margins were again not great (although better than Q2)... Guidance suggests closer to normal in Q4
At least they proved that the people who were freaking out about the cash cushion in Q2 didn't understand the company/working capital.
If we extrapolate Q4 net income guidance of $4.7M-$6.7M
~CAD$8M / Q
It'd be at ~7x earnings before the 60-100% growth from Svetlana & hopefully more in Senegal.