I ask a lot of question on here, but nobody seems to answer...maybe they are so deep, complex, and philosophical that they seem rhetorical? Just me? 🤷♂️🤔
For many parents, it is a familiar, sinking feeling: Adding your kid as an authorized user to your debit or credit card – and then seeing a surprise purchase pop up on your statement. https://t.co/QGYSWd9fSr
If you’re contemplating a move out of the U.S., think hard about why you want to go. Those trying to avoid taxes may need another plan. The U.S. is one of the only countries in the world that taxes its citizens no matter where they https://t.co/4u3ZyuTBUv
Just like any behavioral change, having someone to hold you accountable to your financial goals can make a world of difference. #FinancialGoals https://t.co/Oq1bzpOJMJ
If I needed the mortgage sooner, I'd try to find a cosigner or explore new alternative solutions such as Divvy Homes. If I could wait, I'd spend the months necessary to increase my score to around 620 or better. Read more in comment section...
Some people's credit score is pretty good to get approved for a mortgage at a competitive rate, but I get there are many good folks out there who have damaged or impaired credit (and some by no fault of their own).
I care about these limits because, in short, conforming loans are cheaper than non-conforming loans. If you're curious why, visit https://t.co/lJO24FkSuy and check out the $Level T Aside.
If I live in Virginia and I want to move to San Francisco, I'd look at California's loan limits and not Virginia's. And if I live in Virginia and want to move to Virginia, I'd look at Virginia's, not California's. Why? Read more in comment section...
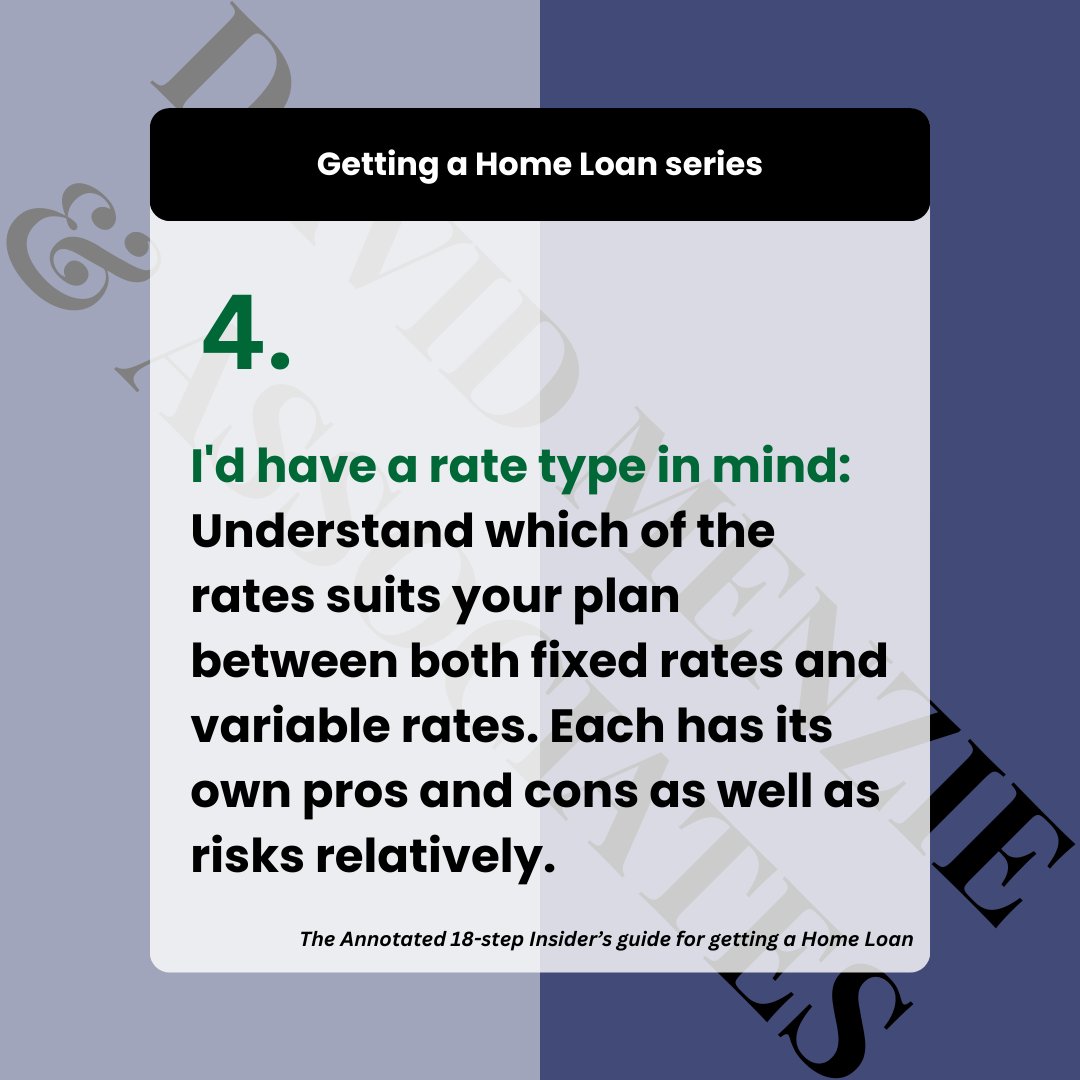
fixed rates stay, well, fixed over the loan term, while variable rates drift over the loan term. These drifts are subject to lender decisions, macroeconomic conditions, government regulations, and other "exogenous"—anything relevant, but uncontrollable by you—forces. (cont'd)
For a super recent and super brief history lesson, variable rates were extremely popular in the lead up to the financial crisis (accounted for some 30% of new mortgages), but have cooled off significantly in the last 10 years.
The question I'd ask myself here isn't necessarily how long I plan to live in the house, but how quickly I'd be able and willing to either pay off my loan or refinance. In general, the shorter the term, the lower the rate, but the higher your monthly payments will be.