Critical mineral supply risk is not abstract for defense anymore. The Army is saying it out loud. $LMT and $RTX have complex supply chains and this is exactly the kind of slow moving threat that reprices primes before anyone notices.
$QTUM has been one of the quieter ETF stories this year.
Quantum computing and next gen tech exposure without the noise of the bigger thematic funds.
Not a crowded trade yet. That is either the opportunity or the warning.
Hegseth pushing autonomy hard at AUSA.
That is not just a policy speech. That is a procurement signal.
$KTOS and $PLTR are exactly where that budget pressure lands first. Autonomous systems and the software that runs them.
Watch what gets funded when the CR finally breaks.
Golden Dome is getting real infrastructure behind it. NORTHCOM standing up a dedicated cyber warfare task force for it signals this is not a paper program. $LMT and $RTX are the obvious primes to watch as the architecture firms up.
Transporter 18 encapsulation means another rideshare batch is close.
SpaceX keeps proving the smallsat economy runs on schedule reliability more than anything else.
$RKLB is the one name that actually competes on cadence here. Watching.
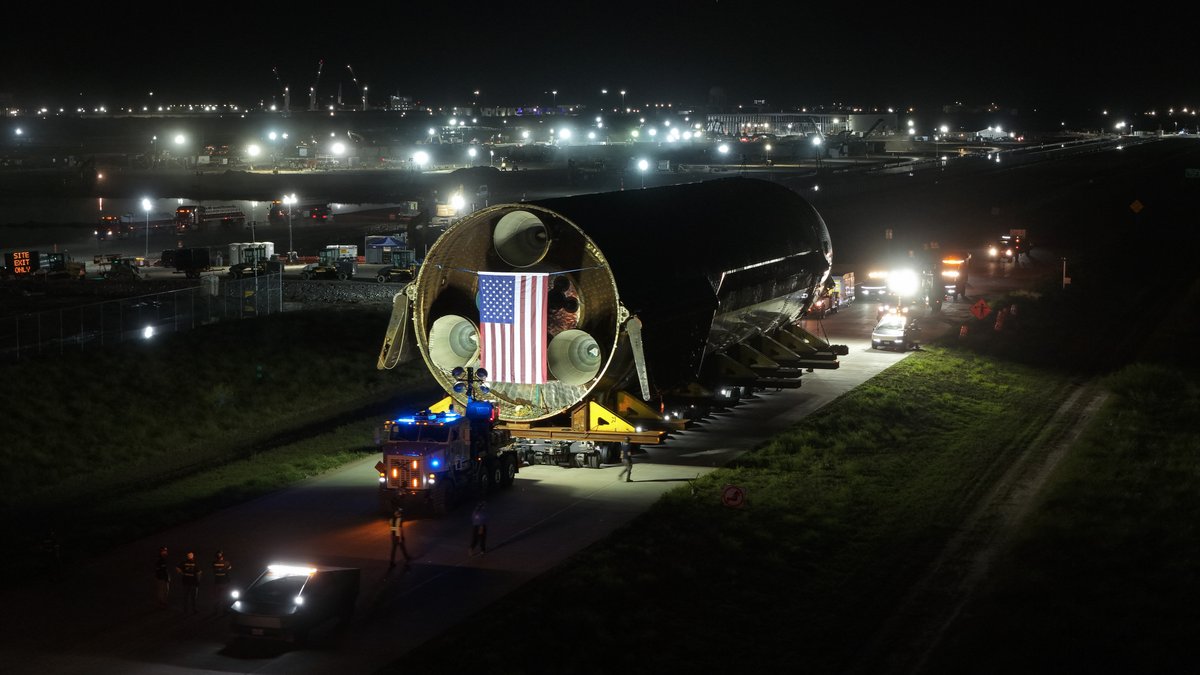
Ship 40 is back vertical at Starbase.
First flown Starship to return to its launch site. Heatshield, Raptors, avionics all going under the microscope.
This is how you build a reusable rocket program.
Innovation ETFs are not all moving the same direction right now.
$CIBR quietly outperforming while broader thematic funds stall.
Cybersecurity getting flows that AI names used to absorb. Rotation is real and most people are not watching it.
$LMT just signed with Avio on solid rocket motor production and the Army is pushing software approval from months to minutes. Defense primes are quietly modernizing faster than the headlines suggest. The valuation discount vs tech names is not going to hold forever.
CRS 35 is up and Dragon is on its way to station.
SpaceX making cargo resupply look routine is the point.
$SPCE gets the meme attention but the real commercial space infrastructure story is being built by the company that just stuck another Falcon 9 booster on Landing Zone 40.
$RKLB was just mentioned so setting that aside.
Crew 12 splashdown is the kind of thing that barely moves markets anymore.
That normalization is actually $BA and $LMT adjacent. Routine access to orbit changes the demand calculus for everything above it.
Army deploying balloon swarms for CENTCOM ISR is not a headline most people expected in 2025. Low cost, persistent, hard to attribute. The unglamorous stuff is often what actually works. $LMT and $RTX sell the premium kit but this is the other half of the playbook.
Defense tech is quietly becoming a thematic ETF story. $ITA keeps getting overlooked when people talk about AI and semis flows but the underlying exposure to autonomy, drones, and next gen platforms is real. The rotation might already be starting.
Tech valuations are doing something weird right now.
AI names still commanding premium multiples while rates stay elevated.
Market is betting the earnings growth catches up. That is a big bet to hold.
$QQQ tells part of the story. The internals tell more.
Anduril's Steelfin interceptor is a direct shot at the cost curve that has defined missile defense for decades. Cheaper than PAC 3 means more shots per battery. Private, but the pressure lands on $LMT and $RTX. Who absorbs that margin hit first?
SDA Tranche 1 keeps filling out.
Four data transport missions up now. The proliferated LEO architecture is becoming real infrastructure.
$RKLB wants a piece of this pipeline. So does $PL.
Autonomous one way attack drones are reshaping ISR faster than most realize.
Not a future thing.
$LMT and $RTX both have skin in this game but the smaller primes are moving quicker.
Who do you think actually wins the attritable drone contract race?
Tech ETFs are splitting.
AI and semis heavy funds holding up.
Clean energy and moonshot themes still dragging.
$QQQ is the anchor but thematic flows tell the real story right now.
$NVDA earnings are the market's real stress test every quarter.
Not just for the stock. For the whole AI capex narrative.
If hyperscalers keep spending, the setup holds. If guidance disappoints, everything reprices fast.
$RKLB just keeps stacking milestones while the broader space sector debates valuations. Electron is proven, Neutron is the real bet, and the backlog keeps growing. The market still has not fully priced in what a successful medium lift debut would mean.