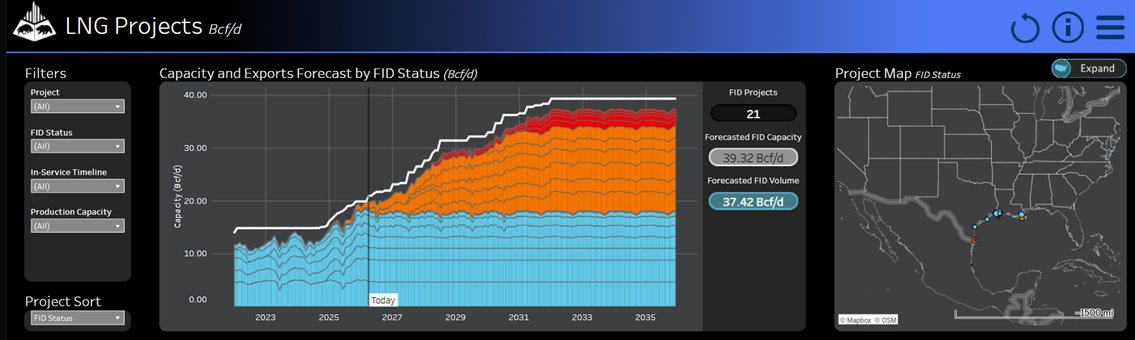
Buyers are locking in US LNG for 2030. Is anyone locking in the pipe to feed it?
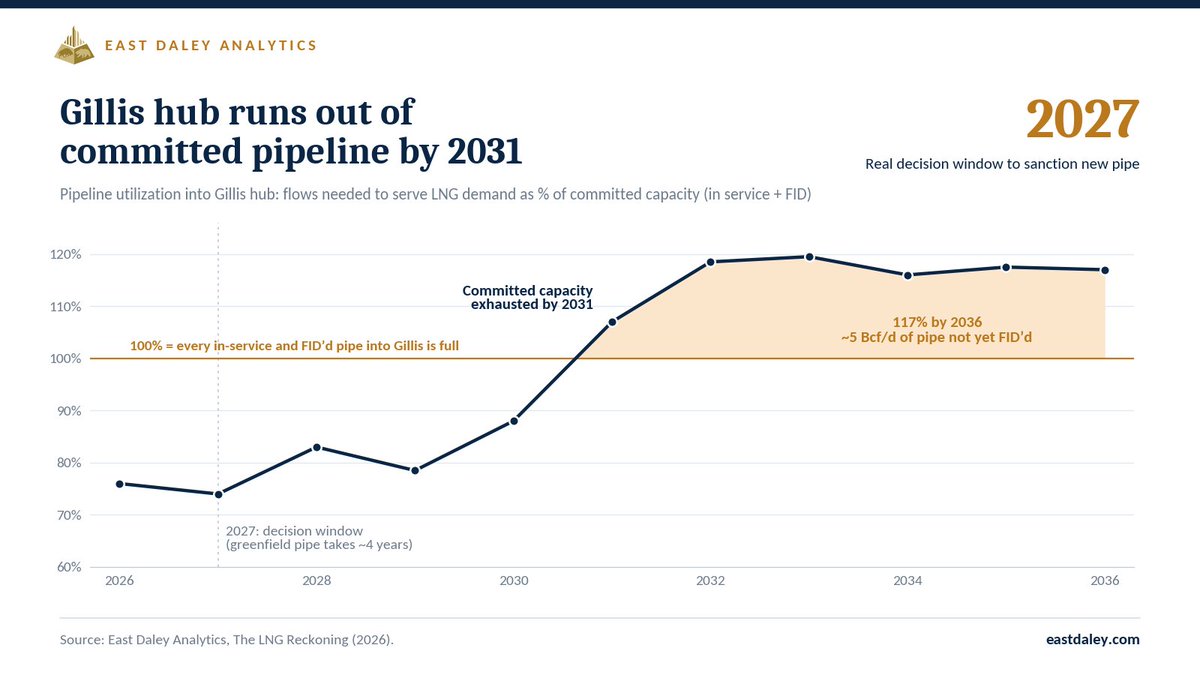
Flows into Louisiana’s Gillis hub exceed committed pipeline capacity by 2031, with ~5 Bcf/d still unsanctioned (East Daley). New pipe takes ~4 years, so the window is 2027.
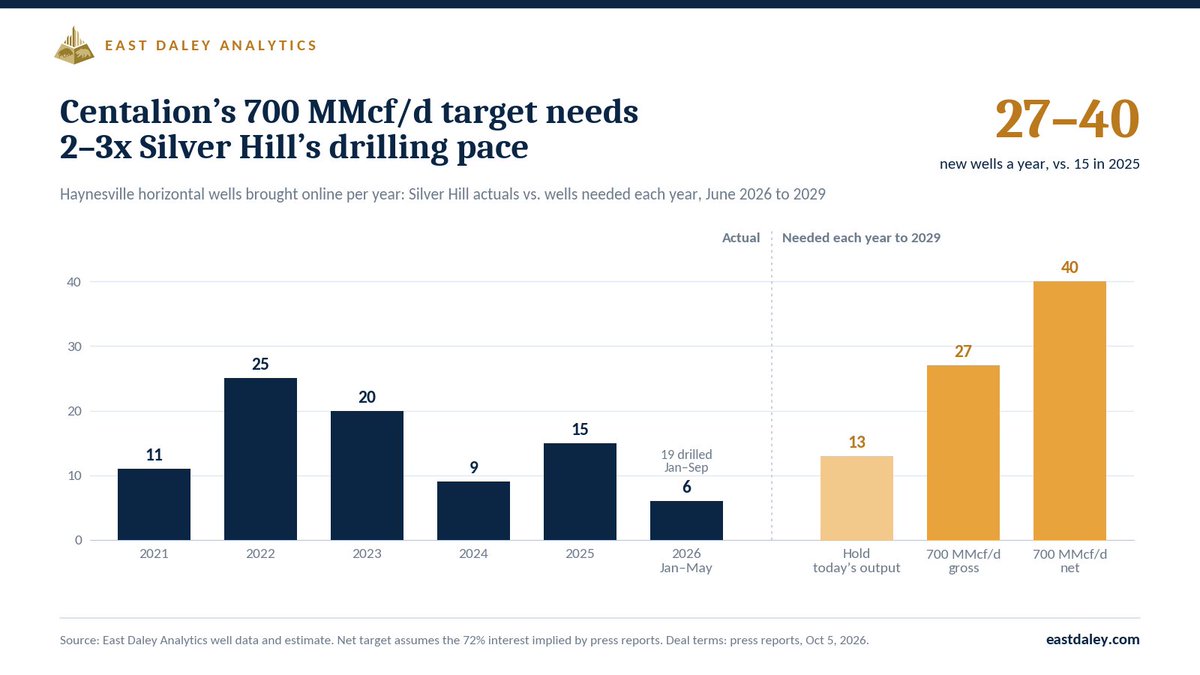
How many wells will Centalion need to drill in the Haynesville?
Centalion just bought Silver Hill's wells, acreage and gathering for ~$1.5B. The wells make 417 MMcf/d and fall fast. Holding flat means drilling ~13 wells a year; reaching 700 MMcf/d by 2029 means 27–40. Silver Hill brought 15 online in 2025.
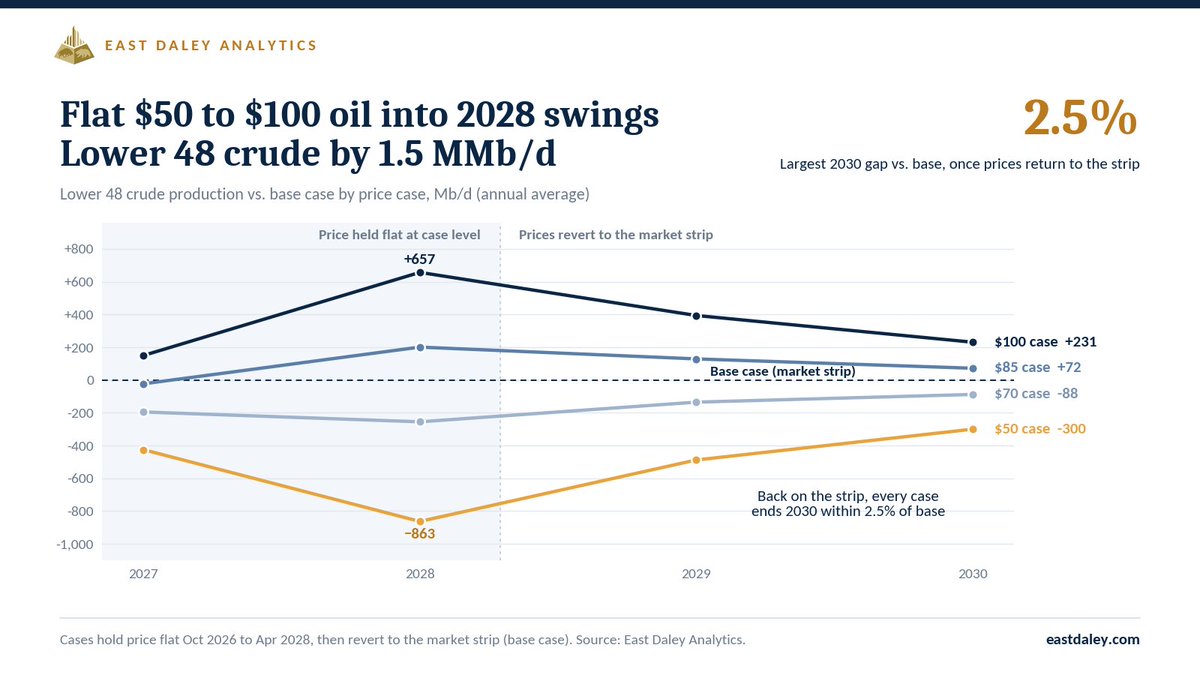
How much does oil price really move Lower 48 crude?
From our September webinar: holding oil flat at $50 to $100 through Apr 2028 swings 2028 output from -863 to +657 Mb/d vs. base.
Back on the market strip, every case ends 2030 within 2.5% of base.
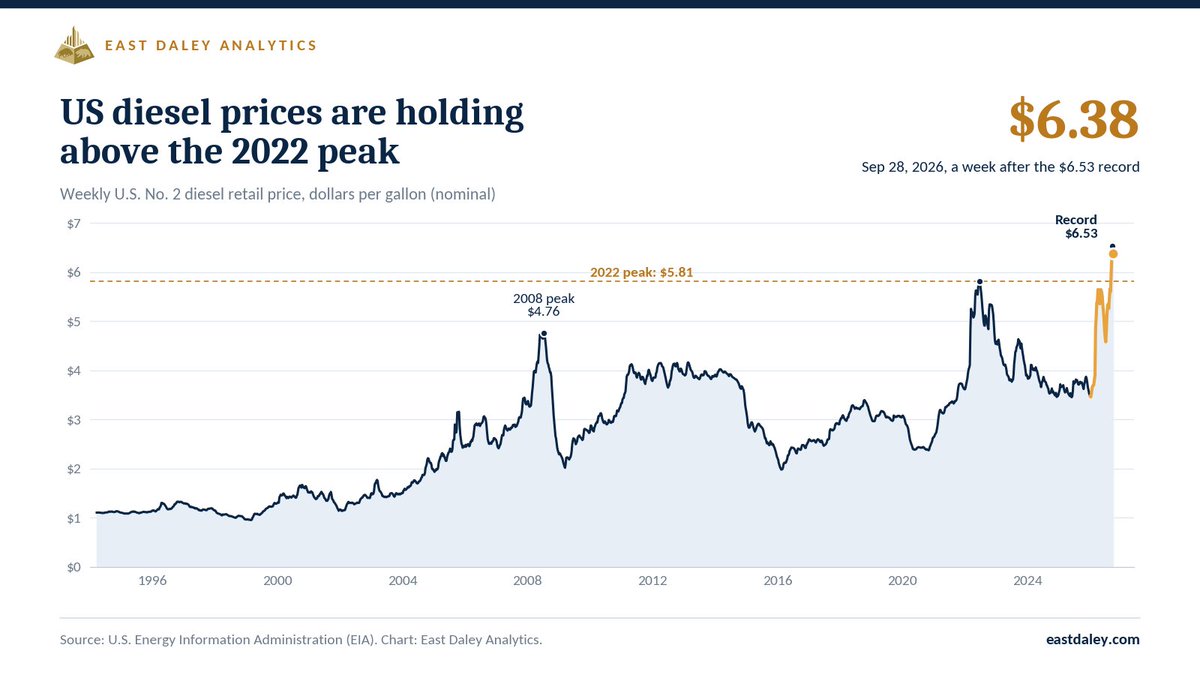
Would a US diesel export ban lower prices or just move the problem?
~68% of tracked US diesel exports YTD go to Latin America (East Daley / Vortexa). A ban could cut Gulf Coast prices, raise them south of the border and eventually force refiners to cut runs.
Kinetik didn’t just benefit from basis.
They were positioned for it.
Owning the pipe tied margins directly to Waha spreads.
Now the setup flips.
What’s the strategy when basis tightens?
https://t.co/3vI4JT9tDI
#natgas#Permian#midstream#energy#CommodityMarkets #EnergyForecast #PermianBasisCollapse #PipelineEconomics #WahaToHouston
Chevron + Microsoft = a new gas outlet.
2.5 GW (scaling to 5 GW) of behind-the-meter power in West Texas.
Up to 8.4 Bcf/d of potential demand.
Associated gas → contracted power revenue.
That’s a structural shift.
https://t.co/NW1kaSrtiF
#natgas#Permian#datacenters#enery
#ChevronStrandedGas #DataCenterEnergy #MicrosoftChevronPartnership #NaturalGasInfrastructure #PermianGasStrategy
A new strategy for Permian gas.
Stranded supply is being turned into long-term contracted power.
That could reshape demand across crude-weighted basins.
https://t.co/V1XAguvPbG
#NaturalGas#LNG#Midstream#EnergyMarkets#OOTT
More crude → more NGLs.
But fractionation is tight.
That’s the bottleneck now.
If it can’t be processed, it doesn’t reach market.
Infrastructure is deciding outcomes.
https://t.co/DoylnUIBSH
#NaturalGasLiquids#PermianBasin#EnergyMarkets#midstream#CrudeGrowth #FractionationConstraints #NGLDemand #NGLPipelines #PermianProduction
The bottleneck just shifted.
Not pipelines. Not production.
Processing.
More crude brings more NGLs. Fractionation is tightening.
That is where the market starts to feel pressure.
https://t.co/jp2DkzEzXj
#NaturalGasLiquids#PermianBasin#EnergyMarkets#oilgas#CrudeGrowth #FractionationConstraints #NGLDemand #NGLPipelines #PermianProduction
Kinetik’s margins track the Waha spread. Almost 1:1.
That relationship has been a tailwind since 2022.
Now it’s at risk.
New Permian egress compresses the spread → margins follow.
Same assets. Different outcome.
Watch Full Webinar https://t.co/VSrtY3Ecdi
#natgas#Permian#LNG #midstream #oilandgas #energy
From our energy expert @FryerJaxson:
Saudi Supply Disruptions Keep the Physical Market Tight: Attacks on Saudi #upstream, refining, and export infrastructure have removed meaningful capacity from the system. The implication is that even if headline risk cools, the physical market can stay tight for longer than futures imply because normalization is logistical and quality-driven, not instantaneous. East Daley’s view has been that the market clears through sequence and crude quality, not just flat-price headlines.
U.S. Producers Are Not Chasing the Price Spike: Even with political pressure to drill more, U.S. E&Ps are still behaving conservatively because the forward strip, not the prompt spike, drives capital allocation. The implication is that near-term export demand is more likely to be met by inventory draws than fresh production growth, which keeps the supply response muted and supports tighter balances for longer.
KMI Acquires Monument Pipeline: Kinder Morgan is buying the 225-mile Monument system for $505MM, adding a Katy-to-Houston Ship Channel asset with about 9 years of average contract life and strong utility/industrial exposure. The implication is that KMI is leaning harder into contracted, Houston-area demand growth tied to utilities, industry, LNG, and storage optionality rather than taking pure commodity risk.
Gas #Infrastructure Valuations Are Still Rich: Spire’s $650MM storage sale and Apollo’s purchase of 40% of Pembina Gas Infrastructure both reinforce the same message: the market is still paying up for contracted gas infrastructure with reliability value. The implication is that storage, pipes, and integrated gas networks remain scarce strategic assets in a market increasingly driven by optionality and locational demand.
FERC and the White House Are Actively Pushing Infrastructure Forward: #FERC plans to act on the large-load interconnection docket by June 2026, while the White House is also moving on pipeline and energy-security actions. The implication is that power demand growth, AI load, and hydrocarbon infrastructure are becoming more directly policy-linked, which should help some projects advance but also makes permitting and regulation a bigger part of the investment case.
#eastdaleyanalytics #EnergyMarkets #OilAndGas #CommodityMarkets #EnergyIntelligence #MarketSignals #GlobalEnergy #EnergyStrategy #EnergyInsights
https://t.co/yTgH7RYR6s
East Daley Analytics returns with our April Production Stream, focused on one thing: where value is forming in today’s market.
We connect production to outcomes. How #LNG demand is reshaping U.S. gas, where infrastructure is capturing value, and how shifting #fundamentals translate into financial performance.
If you care about where returns are forming and where they are at risk, this is the conversation.
Click here to register: https://t.co/ny50hanv5R
#NaturalGas #LNG #EnergyMarkets #Midstream #OOTT #EnergyAnalytics #GasMarkets #EnergyInvesting
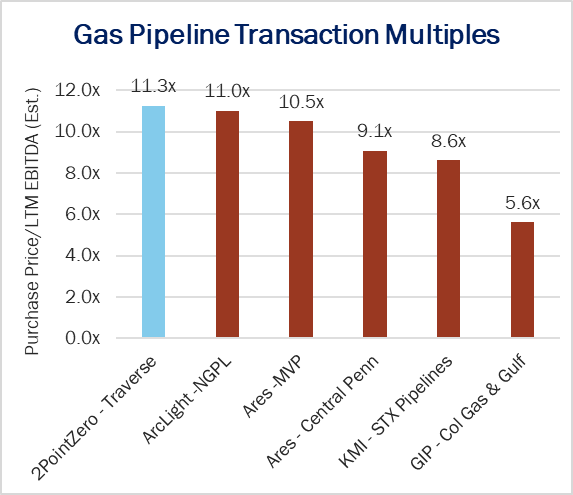
From EDA energy expert @FryerJaxson : Investors should watch the 2PointZero-Traverse deal as a possible signal that private capital is willing to pay peak multiples to gain exposure to US midstream. At $2.25B, the transaction values Traverse at about 11.3x 2025E EBITDA, a premium to recent comparable pipeline deals despite Traverse’s mix including ORS, a gathering asset that typically commands a lower multiple. East Daley sees limited upside in the portfolio, with Rover facing potential recontracting risk after 2033 and about $70MM of annual revenue exposure tied to weaker Dawn market pricing. The key question for investors is whether 2PointZero overpaid for a US foothold, or whether this deal marks a broader reset higher in infrastructure valuations.
#EBITDA #2PointZero #midstream #energydata
Most #equity research starts with guidance, comp tables, and management’s version of the story.
#EastDaley starts at the asset level, where #EBITDA is actually made or lost. We build from the ground up, linking wellhead activity, pipes, plants, contracts, and bottlenecks to company-level financial outcomes. That is the edge: earlier signals, better risk identification, and a clearer view of what is really happening underneath the numbers.
A good example is #Kinetik ($KNTK).
Our call is that KNTK still has near-term earnings upside, but the market is treating that upside as far more durable than it should.
Today, wide Waha-Houston Ship Channel spreads are supporting outsized marketing margin, and that should keep near-term results elevated as Permian takeaway remains tight. But that strength is a function of scarcity, not a new earnings base.
Once new egress comes online and Waha-HSC compresses, that margin pool should shrink quickly. The real downside likely shows up in 2027, when the basis dislocation gets arbitraged away and KNTK’s marketing earnings reset materially lower.
The setup is straightforward: near-term upside while spreads stay wide, but meaningful long-term downside as normalization takes hold.
Questions? Reach out to our expert @FryerJaxson
Appreciate the mention @qcintelcom "According to East Daley Analytics, there is spare capacity on Permian oil pipe systems destined for export terminals in Corpus Christi and Houston/Nederland in Texas.
That said, based on @ED_Analytics data, usage of major Permian lines bound for Corpus, being the top crude export hub in the US, is just 400,000 bpd short of the total capacity offered by Gray Oak, Cactus I, Cactus II and Cactus III networks." https://t.co/GCMC1Bdkub
Appreciate the mention from @jd_journalism with @NGInews, and the opportunity to contribute expert perspective through Jack Weixel. "...a warm March helped staunch a deeper drop in storage. #EastDaleyAnalytics senior director Jack Weixel said production data show U.S. output growing at roughly a 6% year/year pace through 2026, driven by incremental gains in #Permian Basin associated gas."
https://t.co/AAMU6xDx8Z
Market Insights from our experts: @FryerJaxson and @RentonJulian Commonwealth LNG has been in the news after Caturus last week announced full commerciality and the launch of project financing, on the way to a final investment decision (FID). The company is marketing a "wellhead-to-water" strategy, pairing the $12.5B LNG project with the pending acquisition of SM Energy's Galvan Ranch acreage in South Texas. It's a compelling narrative East Daley is familiar with. But in this case, the midstream link between wellhead and water is unclear to us. The main risk we see for Commonwealth is the lack of a defined header system. Nearly every other LNG facility on the Texas-Louisiana Gulf Coast has a dedicated header pipeline connecting to the Gillis or Katy hubs. #Commonwealth proposes to interconnect with the ANR and #Bridgeline pipelines. However, those systems are fully contracted long-term on that route, despite available physical capacity. Owning #upstream production doesn't solve for the supply problem if the molecules can't move to the plant on firm transport.
https://t.co/JOPl3XsKA4
From our energy experts @FryerJaxson and @RentonJulian
"Fallout from the Iran conflict has pushed #crude prices higher and renewed focus on oil-weighted basins like the #Bakken. We recently revised our Bakken outlook higher in anticipation of a recovery in drilling activity. While #producers have been cautious in the recent month, improved price signals should prompt a measured return to growth."
https://t.co/yTgH7RYR6s
#EastDaleyAnalytics #Crudeoilprices #Bakken #energyanalytics #OOTT
Higher oil prices don’t hit evenly.
Realized prices lag.
Hedges cap upside.
Earnings don’t move 1-to-1 with spot.
The headline spike is misleading.
The real story is underneath it.
Breakdown:https://t.co/gKCO0AgtIZ
#EOGResources#EquityEarnings#HedgingStrategy#OilPrices